Skip to content

Specialty Vehicle Outlet Insurance

An asking price cannot explain every detail that gives a collectible car its value. Your insurance needs a clear basis for settling damage, especially when the vehicle belongs to a consignor.

The Southern Agency can help you align your dealership's stock, transit, and liability requirements with current insurance terms.

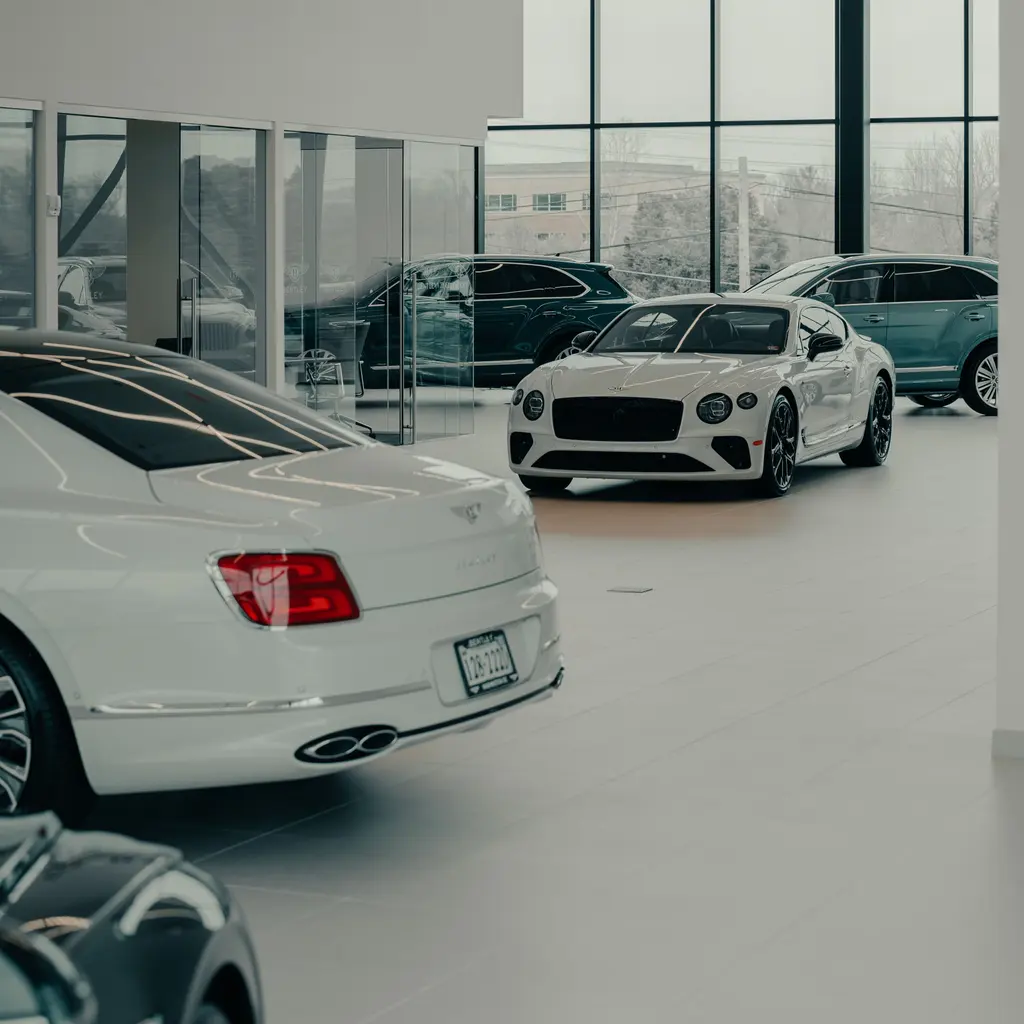
A white Bentley coupe and other luxury vehicles displayed inside a glass-walled showroom.

Industry overview

You trade in classic, exotic, custom or limited-production vehicles, handling inventory through ownership or consignment. Your daily work—detailing, moving cars for demonstrations, or transporting them to auctions—can lead to accidents, property damage, or disputes over vehicle condition.

The Southern Agency can review your dealership's valuation methods, custody agreements, and transport logistics to help you select appropriate insurance. For example, we can compare coverage for declared consigned stock against potential liability for a fire in your showroom or a data incident involving consignor information.

Risks worth discussing

Valuation does not match the vehicle or loss

Condition, provenance, modifications, and available parts can affect a repair or settlement dispute. The asking price, appraisal, inventory figure, and policy valuation method are not interchangeable; review partial and total losses, deductibles, and any salvage or resale-value terms.

Consigned cars are damaged or stolen

An owner may seek payment for a car held for sale, storage or work. Identify declared interests, authority, and actual custody terms, including whether payment depends on legal liability or direct property cover. Possession alone does not establish a full-value policy payment.

Loss during shows, auctions or transport

Loading, unloading, temporary storage, road movement, or theft can affect a car away from the showroom. Map who holds and insures the car at each handoff, then compare actual dealer-transit, carrier and site terms, values, and limits.

Demonstration injury and vehicle damage

A road demonstration can injure others or damage a dealer or consigned car. Review actual drivers, permissions, vehicles, and uses separately from the vehicle's value; liability, own stock damage and owner-use arrangements are different interests.

Storage, detailing or other work damages a car

Fire, water, or handling can damage a stored vehicle, while detailing or other work may affect finishes, components, or condition. Describe the actual tasks and providers; resulting damage, correcting work, a warranty, and a claimed reduction in value need separate review.

Proceeds diversion and transaction or data disputes

Changed payment instructions, stolen deposits or consignor proceeds and exposed finance information can involve different losses. Title, odometer, condition, or authenticity disputes also differ from an intrusion or accident; identify actual representations, funds and responsibilities.

Coverage worth discussing

Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.

Situations to think through

These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.

  1. Hypothetical: Classic damaged while loading for an auction

    Hypothetical: a consigned classic is damaged while being loaded onto a carrier for an auction. Applicable dealer-stock transit or expressly written vehicle-transport terms may address covered physical damage if the car, operation, route, and interest fit. Valuation, loading conditions, and limits matter; a generic inland-marine label or carrier certificate does not establish the consignor's full asking price or the dealer's recovery.

  2. Hypothetical: Consigned car stolen from the showroom

    Hypothetical: a collector's car held for sale is stolen from the showroom. Applicable declared consigned-stock physical damage or other express customer-car terms may address a covered theft, subject to owners, site, conditions, and payment basis. Holding the car, having an appraisal or carrying garage liability does not establish guaranteed agreed value or unconditional reimbursement.

  3. Hypothetical: Forged instructions divert consignor proceeds

    Hypothetical: an impostor posing as the consignor sends new bank details, and staff transfer sale proceeds to the wrong account. Applicable social-engineering or other fraud terms under an actual crime or cyber policy may address a covered money loss if the funds and circumstances fit. Breach response alone does not establish reimbursement. Review who authorized the transfer, who owned the funds, and the actual verification, reporting, and sublimit conditions.

Before you talk to an agent

What to have ready

Tick items as you gather them. Nothing here is saved or sent.

Questions to raise

  • Review each actual valuation method and how stock values are reported or updated. Bring condition, provenance, modification, and appraisal information without treating it as a guaranteed settlement. Compare partial and total loss, repair, deductibles, salvage, and any terms for a reduction in resale value; do not assume a personal collector policy or asking price defines dealer cover.
  • Separate owned, financed, consigned, and customer cars held for work, with any noncollector stock or automobilia identified. Read authority, custody, who insures and who receives payment at each stage. A consignment agreement and a liability promise do not establish direct physical-damage terms or every owner's interest.
  • Trace movement to shows, auctions, and buyers from release through loading, transport, temporary storage, and acceptance. Compare the dealer's vehicle-transit interest with the carrier's actual responsibility and limits and the event or auction arrangements.
  • Describe road demonstrations, drivers, owner permissions, personal or other use and actual detailing, repair or modification. Compare third-party claims with damage to the car and the work itself. Match possible visitor, road and work losses with primary and excess scope rather than deriving liability limits from stock price.
  • Map deposits, purchase payments, consignor settlements, and requested bank-detail changes, with actual systems and providers. Compare intrusion response, employee theft, impersonation, and other funds-transfer terms, including verification and notice conditions. Condition, authenticity, title, odometer or finance disputes need separate sales-process review rather than an automatic cyber or accident assumption.

Contract terms to check

  • Define consignment authority, ownership, vehicle identity, condition descriptions, permitted use, custody, release, and who insures or receives proceeds. Compare any agreed or stated figure with actual policy valuation and limits. A promised sale price or responsibility to the owner is not itself a covered full-value loss.
  • Allocate loading, transport, temporary storage and handover responsibilities among owner, dealer, carrier, auction or show and buyer. Compare route, timing, condition records, limits, and insurance interests with the dealer's own vehicle-transit terms. A carrier certificate does not amend either policy or guarantee the owner's recovery.
  • Set out what the dealer says about condition, provenance, title, and odometer information in the sale or auction terms. Define any warranty, correction or return-work promise separately. Compare alleged injury or damage with a financial dispute or refund, and check the actual services and loss covered by any errors-and-omissions wording.
  • Allocate payment instructions, deposits, consignor settlements, and provider access, including responsibility for verifying changed bank details and reporting suspicious instructions or incidents. Compare actual crime, social-engineering and cyber terms; an instruction that appears authorized is not proof that a money loss is insured.
  • Review actual inventory-finance, manufacturer or brand, and premises-lease requests, including property-lender and requested additional-insured liability interests. Check actual endorsements rather than certificates alone, and verify applicable licensing, bond, worker, and road obligations separately from private contracts. No brand or lender minimum establishes every rare-car or funds-handling loss.

What the agent conversation looks like

Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.

  1. ListenReview your operations, current coverage, and past claims.
  2. AssessIdentify potential hazards and discuss ways to reduce risk.
  3. BuildDiscuss policy and carrier options, premium costs, and audits.
  4. SupportReview changes and help you plan ahead as your needs develop.

Questions owners ask

Does an appraisal guarantee agreed-value settlement?

No. Read the dealership's actual valuation, reporting, and loss terms, including partial or total loss, deductibles and salvage. An appraisal or stated figure is information, not by itself a payment guarantee. Do not infer dealer settlement from the owner's personal collector cover or the asking price.

Does consignment automatically mean garagekeepers covers the car?

Identify the owner, why the car is being held and whose property interest or responsibility the policy actually insures. Consigned stock, customer vehicles held for work and the dealer's legal liability may involve different provisions. A consignment contract or generic custody heading does not establish direct physical damage or every owner's full value.

Will a generic inland-marine policy cover auction transport?

Confirm that the actual wording includes the vehicles and interests, loading, carrier, route, and temporary locations. Dealer stock physical damage may have its own transit provisions; a separate vehicle-specific arrangement needs its actual scope checked. A generic equipment label or a carrier certificate does not establish a collectible-car payment.

Does a demo collision have the same response as stock damage?

Injury or damage alleged against the dealer differs from physical damage to an owned or consigned car. Describe actual drivers, permissions, and uses, then compare dealership liability, stock, and owner arrangements. Neither rarity nor a signed test form establishes every interest or loss.

Will cyber coverage reimburse a transfer following forged instructions?

Compare actual crime, social-engineering, funds-transfer, and cyber terms. Staff following an impostor's instructions can involve different conditions from an intrusion or unauthorized bank transfer. Check insured funds, verification, reporting, and sublimits; covered breach response alone does not establish reimbursement of the money.

Does valuable inventory determine the excess liability limit?

Inventory damage and third-party liability are different interests. Compare possible visitor, road and work claims with actual underlying and excess scope, defense, and limits. A rare car's price is not the only measure of potential injury loss, and more liability limits do not insure the stock or every transaction promise.

Talk through your specialty vehicle outlet coverage

Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.

How can we help you get started?

Choose the quote that fits, and we’ll take it from there.

Have a question? Contact us