Skip to content

Business Service Center And Copy Shop Insurance

A customer may hand you the only copy of a photograph or document. Insuring the shop's copier does not answer how that original, or the information it contains, would be protected.

The Southern Agency can help you tailor your shop's coverage to your print equipment, customer records, and retail liabilities.

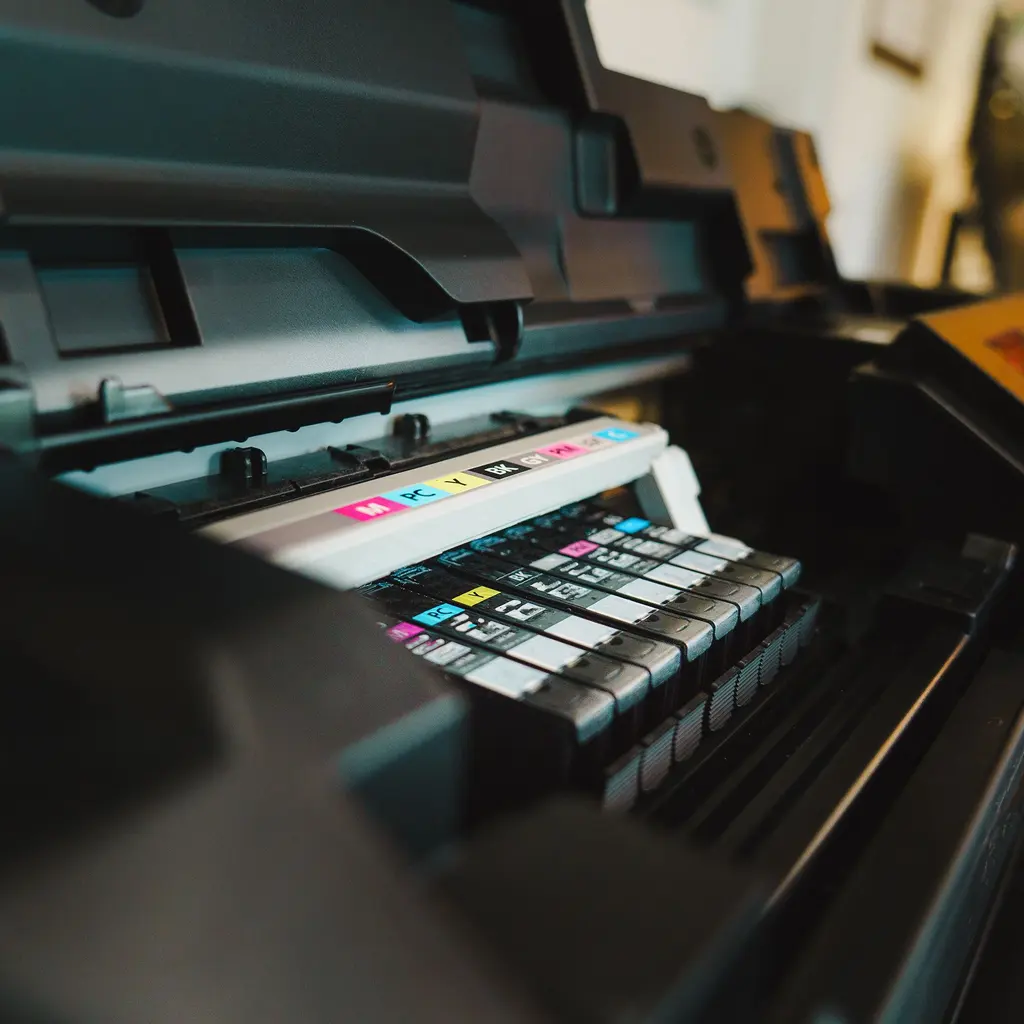
Color-printing equipment with an open ink-cartridge compartment.

Industry overview

You provide printing, scanning, and mailing services for walk-in and business customers. A sudden machine failure during a high-volume print job or a customer injury in your storefront could disrupt your workflow and lead to unexpected costs.

The Southern Agency can help you evaluate your storefront operations and customer handling procedures. We can discuss how to protect your machinery with equipment breakdown coverage and manage risks related to the sensitive customer materials in your care.

Risks worth discussing

Equipment breakdown halting production

A press, copier or finishing machine can fail and leave orders unfinished. Identify the cause, equipment and actual repair and income terms. A service call, paper jam, routine maintenance or software outage is not proof of a covered equipment breakdown or client-delay payment.

Customer slip-and-fall in the storefront

Cords, equipment and customer movement around counters or self-service stations can lead to falls. Review the actual premises, duties and facts of an injury. Liability and any medical-payments terms are not established merely by someone falling, and employee injury is a separate question.

Fire from equipment and paper stock

A fire can damage machines, paper, toner, and finished orders and close the shop. Identify property owners, values, locations, and insured causes, including actual lease interests. Replacement equipment, customer property, business income and client contract remedies do not necessarily share the same limits or conditions.

Damaged or lost customer originals

A photograph, artwork or document can be damaged during handling or scanning. Record what is accepted, its condition and ownership. Check physical customer-property cover separately from reconstructing records or digital files, and how the policy values a unique original rather than assuming it is ordinary shop contents.

Errors and missed deadlines on jobs

A wrong file version, misprint or late order can prompt a demand for reprinting and a claim for the client's financial loss. Confirm the job specification, proof approval, and promised timing. The shop's redo costs, refunds, penalties and alleged professional damages are not automatically the same insured loss.

Payment data and customer file exposure

Scanning, file transfer, self-service workstations, and payment systems can involve personal or confidential information. Identify records, access and outside providers and actual response duties. A confidentiality promise or cyber title does not establish every notification expense, lost file, fraudulent payment, or contractual remedy is covered.

Coverage worth discussing

Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.

Situations to think through

These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.

  1. Hypothetical: Press failure during a rush order

    Hypothetical: a digital press suffers an electrical failure during a rush order and the shop incurs repair costs and loses production. Applicable equipment breakdown may address covered damage and any included income or extra expense if the equipment, cause, timing, and conditions fit. Review waiting periods, limits, and the loss calculation; reprints, refunds and the client's late-delivery claim are not automatically part of that payment.

  2. Hypothetical: Customer trips at the counter

    Hypothetical: a walk-in customer trips on a cord at a self-service station and is injured. Applicable general liability may address a covered injury claim or included medical payments, depending on premises responsibility, facts, and terms. Injury alone does not establish legal liability or payment of every bill; staff injury requires separate review.

  3. Hypothetical: Ruined client artwork

    Hypothetical: original photographs left for scanning are physically damaged before collection. Cover for customer property in the shop's care may help pay for the damaged originals if the property, handling or processing and cause are included. Check custody, limits, and valuation, including any reconstruction basis. An E&O or shop-contents title alone does not establish payment for the client's entire claimed value or a missed event.

Before you talk to an agent

What to have ready

Tick items as you gather them. Nothing here is saved or sent.

Questions to raise

  • List owned and leased printers, computers and finishing equipment, stock, and finished orders with values and interests. Compare the actual settlement basis and limits, not an assumption that every machine or customer original receives full new replacement value.
  • Separate an insured breakdown from ordinary servicing, wear or other interruptions. Identify the machines and causes included and any repair, replacement, deductible, or maintenance conditions. A maintenance contract or the cost of a machine does not establish insurance response.
  • Compare the event that must occur before income cover applies, any waiting period, limits, restoration terms, and the records needed to measure loss. Consider how work could continue through another printer, but check any extra expense before committing to it. A missed order, portal problem or client deadline does not itself establish insured downtime.
  • Map customer originals, scans, stored files, payment data, and self-service or outside-provider access. Review actual cyber events, response permissions and costs separately from physical customer-property, file reconstruction, and fraud terms. Do not assume a confidentiality promise or one package covers all of those interests.
  • Use representative job specifications, file versions, proofs, approvals, and deadlines to compare printing E&O scope and possible client loss. Review claims, prior matters, reporting, and defense terms, including any limits shared across jobs. A small order price does not cap every alleged loss, but a policy limit does not guarantee every redo, refund, or contractual remedy.

Contract terms to check

  • Agree the requested output, approved file version, proof responsibility, quantities, finish, and deadline, with change and acceptance procedures. Compare reprint, refund, delay, and other remedies with actual professional terms. Proof approval or a promise to meet an event date does not establish every resulting loss is insured.
  • Record customer originals accepted, condition, custody, handling, return, and any shipping handoff. Compare responsibility for physical damage or loss and valuation with actual customer-property terms. A receipt, carrier arrangement or client's stated unique value does not itself change the insurer's payment basis.
  • Review equipment and premises leases for property, repair, insurance, and any liability endorsement requests. Distinguish the lessor's equipment interest from additional-insured liability. A maintenance agreement, lease or certificate does not establish all breakdown, customer-property or business-income terms.
  • Allocate client-file access, transfer, confidentiality, return, and retention duties and outside-provider responsibilities under the actual agreement and applicable requirements. A print, scan or mailbox service does not itself authorize every document-preparation, filing or advisory service. Review the actual services and permissions separately from assuming insurance will pay.
  • Read client or landlord requests for limits, additional-insured status, waivers, crime, fidelity, or a specified bond. Identify the instrument, parties, property, and conditions before relying on a certificate or bonded label. Provider insurance does not settle the shop's own duties, and theft allegations, access costs, and every contractual promise are not automatically covered losses.

What the agent conversation looks like

Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.

  1. ListenReview your operations, current coverage, and past claims.
  2. AssessIdentify potential hazards and discuss ways to reduce risk.
  3. BuildDiscuss policy and carrier options, premium costs, and audits.
  4. SupportReview changes and help you plan ahead as your needs develop.

Questions owners ask

What insurance does a copy and print shop usually need?

Compare actual storefront, machines and stock with customer originals, files, and services, including mailbox or shipping work if offered. A business owners policy can be a starting point, but review breakdown, income, printing errors, privacy, and customer-property terms rather than assuming every extension is included or must be bought separately.

Is my printing equipment covered if it breaks down?

Applicable equipment breakdown terms may address included mechanical or electrical damage. Identify the equipment and cause and check repair, replacement, and any income terms, including limits and waiting periods. A paper jam, maintenance need, or system stoppage alone does not establish insured breakdown, lost income or a client's delay payment.

Do I need coverage for customer documents we hold?

Identify physical originals, their owners, and values, processing, and custody stages, and digital files separately. Review actual customer-property, valuable-record, cyber, or professional terms for the particular loss. A contents or E&O title does not establish all property in your care, reconstruction, unique value or resulting client financial loss is included.

Why would a copy shop need cyber coverage?

Scanning, stored files, self-service stations or payment processing can involve customer information and response or liability costs. Applicable cyber terms may address included events and expenses, subject to systems, providers, consent, notice, and limits. Physical originals, every lost file, fraudulent payment, and contractual confidentiality remedy need their own terms checked.

Are missed deadlines or misprints covered?

Applicable printers' errors and omissions terms may address a covered service-error claim and defense. Review declared services, proof approvals, actual alleged loss, prior matters, notice, and limits. Reprinting, refunds, guaranteed dates, penalties, and a client's entire financial demand are not automatically insured merely because an order is wrong or late.

Does a business owners policy cover everything I need?

Read the actual property, liability, income, and optional extensions against your services and interests. It may already include some relevant terms or require changes, but the package name does not establish every machine cause, original, file, printing error, or shipment. Compare existing cover before assuming a separate policy is necessary or available.

Talk through your business service center and copy shop coverage

Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.

How can we help you get started?

Choose the quote that fits, and we’ll take it from there.

Have a question? Contact us