Skip to content

Private Mail Center Insurance

A customer's parcel can be in your care before a carrier ever collects it. Protection at the counter, during packing and after handoff needs to be understood separately.

The Southern Agency can help you align your retail and parcel-handling risks with appropriate property and liability coverage.

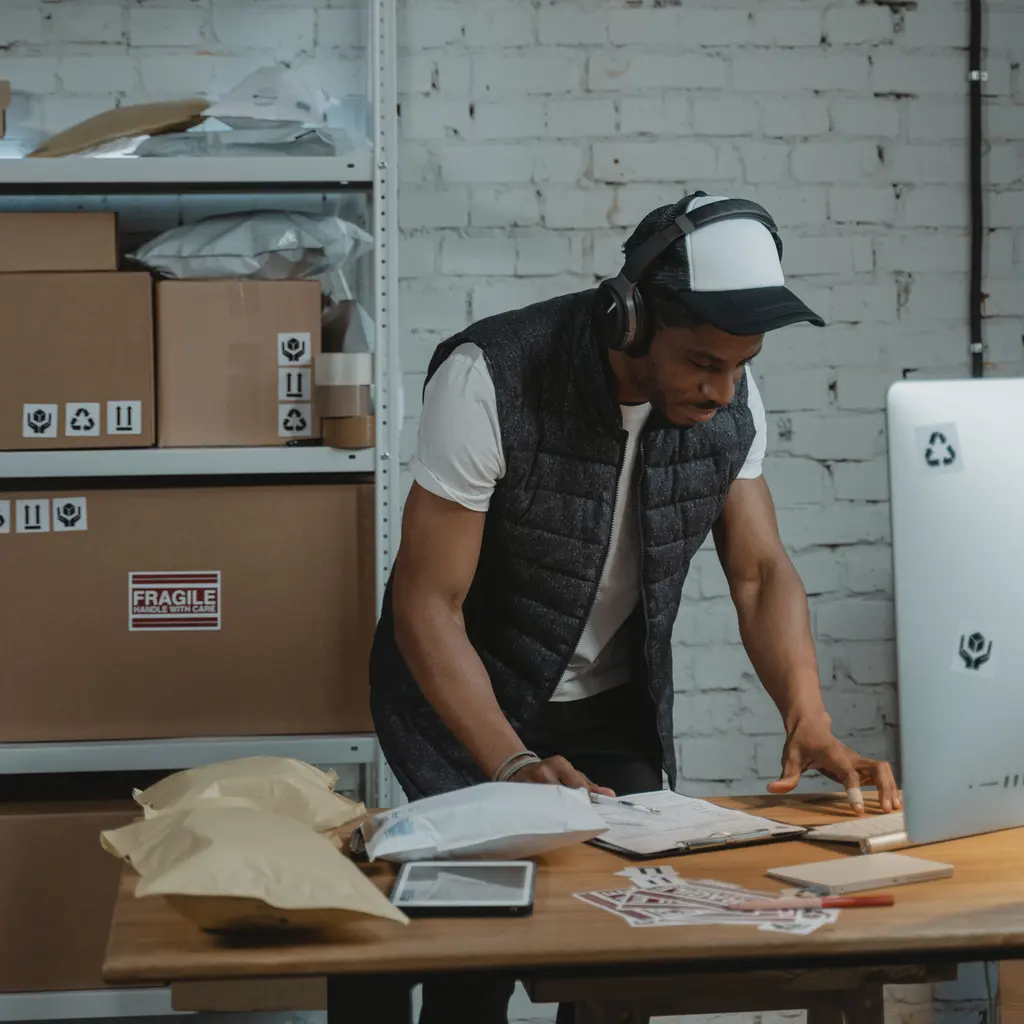
A worker preparing paperwork and packages at a shipping workbench.

Industry overview

You manage mailboxes, pack parcels, and handle shipping for your customers, creating potential liability for lost items or damaged shipments. Your storefront, equipment, and sensitive customer payment data require targeted protection against theft and privacy incidents.

The Southern Agency can help you review your retail and shipping services to select appropriate insurance. We can discuss how to protect your custody of customer goods, for example, by identifying whether your policy covers parcel damage while held versus during transit.

Risks worth discussing

Loss or theft of customers' packages

A parcel can be stolen, misdelivered or found missing while held for pickup. Those facts do not necessarily trigger the same protection. Identify the owner, item, value, custody stage, alleged responsibility, and evidence rather than treating every missing parcel as covered theft.

Customer slip-and-fall injuries

A fall at a counter, entrance or shared walkway can lead to an injury claim against the store and possibly others. Identify who controls the area and the insured location and role; an accident or lease promise alone does not decide liability or payment.

Property and equipment loss

Fire or water can damage fixtures, supplies, copiers, and postage equipment and close the store. Own or leased equipment, building responsibilities, and customer goods are different interests. Internal machine failure, wear, insured physical damage, and lost income also need separate terms.

Packing and shipping errors

A fragile item may arrive broken after packing, collection, or several carrier handoffs. Establish where damage occurred and whether the allegation concerns packing, handling, or transit. Repairing the item, refunding packing fees, and paying a customer's delay loss are different costs.

Cash and payment exposure

Cash, postage and customer payments can be stolen by an employee or outside offender, while deception may cause a staff-approved transfer. List the property and owner, account authority, and event; physical theft, unpaid balances, chargebacks, and computer fraud are not interchangeable.

Customer data and privacy

Mailbox identity records and payment information may be kept by the store, franchise system, or another provider. A loss or disclosure can create response duties and costs, but paper records, online incidents, provider events, confidentiality claims, and payment loss need the actual terms reviewed.

Situations to think through

These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.

  1. Hypothetical: Stolen held package

    Hypothetical: A high-value parcel awaiting pickup is stolen from the back room. Selected bailee or crime terms may help pay a covered parcel loss if that customer interest, theft event, and holding location are included. Confirm the item value, per-item and combined limits, proof and notice, and whether the form requires covered legal liability. A missing item with no clear cause may be treated differently.

  2. Hypothetical: Customer fall at the counter

    Hypothetical: A customer slips near the entrance, is injured, and brings a claim against the store. General liability, whether within an eligible BOP or another arrangement, may help pay defense and covered injury damages. Check the insured premises, store and any other named party, allegations and limits; a fall alone does not establish fault or payment of every medical bill.

  3. Hypothetical: Damaged shipment from poor packing

    Hypothetical: A fragile item packed by the center arrives broken and the customer claims the cushioning was inadequate. Selected customer-property or transit protection may help pay covered item damage only if the packing work, cause, and loss stage are included. Check carrier handoff records, the claimant, responsibility, valuation, and exclusions. Packing fees, shipping refunds and consequential delay costs are not automatically part of that payment.

Before you talk to an agent

What to have ready

Tick items as you gather them. Nothing here is saved or sent.

Questions to raise

  • Compare the highest-value item and maximum combined parcels held, including uncollected mail and goods awaiting carrier pickup. Review direct customer-property and legal-liability terms, what must be proved, property restrictions, and valuation. Acceptance of storage does not mean packing, forwarding, outside custody, or transit is insured.
  • Trace burglary, employee theft, mistaken release, and deceptive payment instructions separately. Identify whose property was lost and who can claim under the actual crime, customer-property, or carrier arrangement. Check access records, required proof, discovery, notice, and any lower limit before promising a customer full reimbursement.
  • Value owned and leased copiers, postage equipment, fixtures, and supplies separately from the building and customer items. Compare actual covered causes, internal breakdown, and purchased income or extra-expense terms, including waiting time and the store's own defined income. A shipping deadline or customer sales promise is not the income calculation.
  • Read the actual lease, franchise and carrier or customer service terms together. Identify insured parties, tenant duties, packing promises, custody handoffs, claim rights, valuation, and limits of responsibility, plus any required endorsements or waivers. A carrier transaction, customer receipt or certificate does not by itself show that the center's own packing or custody liability is insured.

Contract terms to check

  • Set out receipt, holding, pickup authorization, forwarding, packing, and carrier-handoff responsibilities for each service. Identify who contracts with the carrier, who may bring a claim, how item value is recorded and any agreed limit of responsibility. Do not promise every packing fee, delay, replacement value or lost contents will be reimbursed by your insurer or another party.
  • For a packing job, record the item's condition, materials and packing work agreed, customer instructions, special handling and acceptance of changes. Compare that work and the point of loss with customer-property and transit terms, not only premises liability. A customer approval helps investigate the allegation but does not decide negligence, cause, or coverage.
  • Read the actual lease and franchise insurance requirements for the named store, building and tenant interests, limits, insured parties, waivers and evidence. Check each requested endorsement against the policy before committing. A certificate does not amend the form, and a shared brand, landlord or franchisor policy does not automatically include this entity or every service.
  • Where staff or providers can access parcels, cash, records or secure areas, allocate custody, supervision, incident reporting and any actual crime, fidelity, or bond request. Identify the instrument, beneficiary, and loss addressed. A provider's insurance does not transfer every claim, and a bonding label or key-control promise does not insure every missing parcel or replacement lock.
  • Agree actual record-access, confidentiality, retention, and incident duties with mailbox customers, franchise systems, and processors, subject to applicable requirements. Obtain qualified advice on identification, postal and privacy obligations and how long records must be kept. Keep those responsibilities separate from insured response events, expenses, consent, and notice conditions rather than assuming one deadline or reimbursement applies to every incident.

What the agent conversation looks like

Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.

  1. ListenReview your operations, current coverage, and past claims.
  2. AssessIdentify potential hazards and discuss ways to reduce risk.
  3. BuildDiscuss policy and carrier options, premium costs, and audits.
  4. SupportReview changes and help you plan ahead as your needs develop.

Questions owners ask

Are customers' packages covered while in our care?

Selected customer-property or bailee protection may help pay covered parcel damage or loss. Check the details before promising reimbursement: whose goods and which property types, location, cause, and values are included? Some forms require your covered legal responsibility rather than paying for damage to the goods directly. Packing, forwarding, transit, unexplained shortage, and goods after carrier handoff need their own terms reviewed.

What protects us if a customer is injured in the store?

General liability may help pay defense and covered injury damages, whether included in an eligible BOP or arranged otherwise. Check the actual store, insured parties, services, area involved, allegations, and limits. Responsibility for a shared entrance or walkway matters; a lease clause or accident alone does not establish every party's liability or payment of all medical bills.

Do we need crime coverage?

Selected crime terms may reimburse specified theft or fraud loss. Start with whose cash, postage or parcels are insured and who may claim. Compare employee theft, outside burglary, and approved payments induced by deception, then check required proof, timing, and limits. Unexplained shortage, a lost key, or a chargeback is not automatically a theft claim. Review existing extensions before deciding whether separate crime coverage is needed.

Is customer data a concern for a mail center?

Identity and payment information can create response costs or privacy claims if disclosed or compromised, including records handled by a franchise system or processor. Selected cyber terms may help with specified response and covered liability. Check actual paper or electronic records, incident and provider scope, legal duties, response permissions, and notice; keeping records elsewhere or having notification duties does not decide which expenses the insurer pays.

What if a package we packed is damaged in shipping?

Establish the item's intake condition, packing work, custody transfers, and alleged cause. Selected customer-property and transit terms may help pay covered item damage if that operation and stage are included. Compare who can claim and what the carrier and center agreements address; a shipping receipt or recorded value does not by itself show that your own packing responsibility is insured. Fees, refunds and consequential delay losses need separate review.

Talk through your private mail center coverage

Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.

How can we help you get started?

Choose the quote that fits, and we’ll take it from there.

Have a question? Contact us