Skip to content

Locksmith Insurance

Customers rely on the lock you specify or fit after you have left the premises. Liability for that work is different from insuring the tools and key machines in your van.

The Southern Agency can help you review your mobile tools, security advice, and client access exposures to select the right insurance.

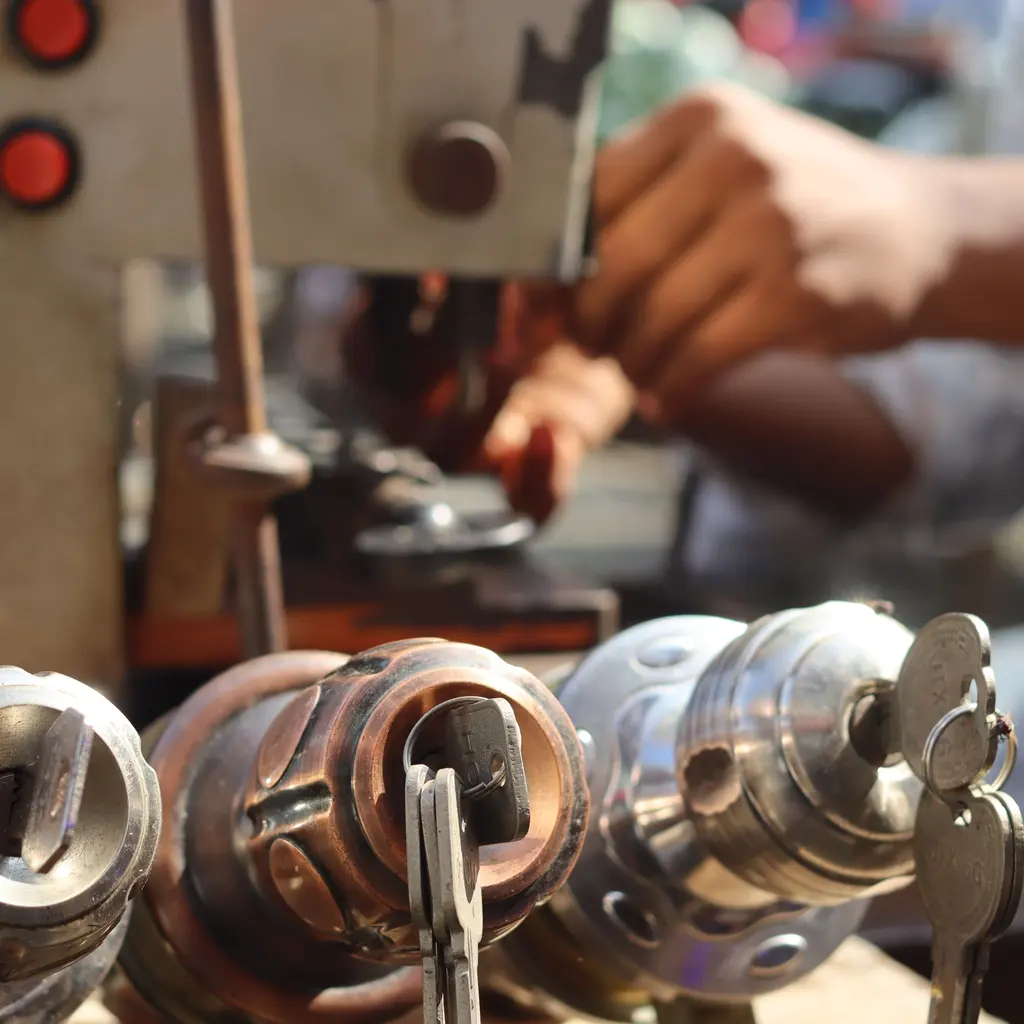
A locksmith working at a key-cutting machine behind several metal lock cylinders.

Industry overview

You open locked vehicles, premises or safes and may also specify or program electronic access. A damaged door frame and a claim that an installed lock enabled a burglary raise different questions from losing a key machine from your van.

The Southern Agency can help you review your services and mobile operations to choose insurance. We can compare liability for your security work with tool protection, proved client-theft losses and any specifically requested bond.

Risks worth discussing

Damage during forced entry

Opening or servicing a lock, vehicle, ignition or safe can damage the mechanism, frame or surrounding property. Record the authorized scope, pre-existing condition, part being worked on, and resulting harm elsewhere. An agreed replacement, correction or customer's repair demand is not automatically insured accidental damage.

Faulty installation and resulting burglary

A customer may allege that a specified or installed lock failed and contributed to a burglary. Identify the work, handoff, later changes, claimed loss, and evidence of cause. The break-in alone does not establish negligence, employee theft or coverage, and replacing the lock differs from paying for the customer's loss.

Access misuse and theft accusations

Keys, codes or access knowledge may be lost, disclosed or misused, or a technician may face an accusation. Identify actual people, authority, property, events, and proof. Physical key replacement, electronic reprogramming, a data incident, and proven theft are different loss and response questions.

Mobile tool and inventory loss

Key machines, picks, programmers, blanks and lock inventory may be stolen or damaged in vans, at jobs or at a shop. Separate owned or rented machines, customer items, stock, and access records by value and location. Vehicle damage, equipment loss, and missed calls do not all follow from one van or tool schedule.

Professional errors on security work

Advice, specification, programming or installation can lead to a claim that a system failed to secure premises or wrongly denied entry. Describe the actual service and any outside installer, platform, or monitoring role. Rework, warranty and security-performance promises are not automatically covered professional damages.

Vehicle accidents on service calls

Scheduled or emergency travel to lockouts and installations brings road-liability and vehicle-damage questions. Disclose ownership, drivers, and use, including staff cars or rented vans where relevant. Damage to the van, injuries to another road user, carried gear, and an injured technician's benefits need separate coverage checks.

Situations to think through

These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.

  1. Hypothetical: Damaged door during a lockout

    Hypothetical: a locksmith damages a commercial door frame while opening a jammed lock. Applicable general liability may help pay defense and covered property-damage liability. Identify the actual mechanism and frame area being worked on, separate surrounding damage and relevant work-property or custody terms. Permission to open the door and the customer's repair bill do not prove payment for the frame or an agreed lock replacement.

  2. Hypothetical: Break-in after a new install

    Hypothetical: a customer alleges a recently installed lock failed and enabled a burglary. Applicable professional liability, or general liability where the alleged harm is included, may help pay defense and covered liability. Check the service and claimed loss, evidence of cause, professional or security exclusions, and how and when claims must be reported. A burglary is not proof of installer fault or employee theft; replacing a defective lock or honoring a security guarantee is not automatically the same insured loss.

  3. Hypothetical: Stolen tools from a van

    Hypothetical: a van is broken into overnight and key machines and tools are stolen. Applicable inland marine may help repair or replace included equipment after covered theft. Check ownership, actual gear, values, site, unattended-vehicle and security terms, proof, deductible and limits. The van's own damage, lock inventory, customer items, stolen codes, and missed service calls need separate review.

Before you talk to an agent

What to have ready

Tick items as you gather them. Nothing here is saved or sent.

Questions to raise

  • Separate an accusation, actual employee theft, lost keys, electronic access changes, and a later burglary. Compare actual insured people and client-property interests, proof, notice, limits, and any separately granted defense or key-response protection. Customer trust or access knowledge does not establish a covered crime loss or make every owner or outside technician insured.
  • Check the actual authority, work and location for applicable qualifications, and read any requested bond rather than inferring a requirement from the trade name. Compare the specified beneficiary, obligation, claim, and repayment terms with insurance and any client-theft instrument. A certificate or bond does not authorize every service or guarantee every customer remedy.
  • List machines, programmers, tools, blanks, and lock stock by owner, peak value and van, shop or client stage. Compare theft and unattended-vehicle conditions, valuation, deductibles, and individual or broader limits. Separate van damage, customer items, access records, wear, breakdown, and lost work instead of treating all contents as mobile tools.
  • Describe advice, programming, installation, service and any monitoring. Compare professional and general-liability terms with actual client promises. Consider potential client loss and defense costs when choosing limits, not just the price of a lock. If cover is claims-made, check prior acts, claims, and reporting conditions when renewing, changing insurers, or ending work; continuation or an extension is not automatic.

Contract terms to check

  • Define who may authorize entry, the lock, door, vehicle, safe or system involved, existing condition and actual opening, replacement or programming scope. Agree how changes, damage, and customer acceptance are recorded, with qualified advice on authority and duties. An authorized destructive opening or agreed replacement cost is not automatically an insured accident.
  • Specify security advice, hardware, installation, testing, credential handoff, and any maintenance or monitoring duties, including outside providers and customer changes. Compare guarantees, indemnities, and claimed loss types with professional, completed-work, and property terms. A promise that premises will remain secure does not make every later burglary, refund or system correction insured.
  • Allocate who holds keys, records, customer property and devices; who may use or disclose them; and how an access or loss incident is reported and handled. Distinguish physical key replacement, credential reprogramming, data response and proven theft. Check the actual policy or instrument for the people, client interest, costs, proof, and notice involved rather than treating them as one crime claim.
  • Compare actual client requests for insured parties, waivers, limits, certificates, and any specific bond before agreeing. Identify the responsible employer, installer, outside technician, and recipient of protection. A provider's insurance or customer certificate does not amend your policy, automatically transfer all provider liability, satisfy every condition, or guarantee every endorsement is available.

What the agent conversation looks like

Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.

  1. ListenReview your operations, current coverage, and past claims.
  2. AssessIdentify potential hazards and discuss ways to reduce risk.
  3. BuildDiscuss policy and carrier options, premium costs, and audits.
  4. SupportReview changes and help you plan ahead as your needs develop.

Questions owners ask

Why might a locksmith need crime coverage?

Actual employee dishonesty or client-property theft may be relevant to the work, but access and an accusation do not establish a covered loss. Review included people, whose property is insured, who can claim, and proof, discovery, notice, and limits. Lost keys, a later burglary, rekeying, electronic changes, and defense costs need their own terms, not an assumption that every crime policy or bond pays.

What if I damage a customer's door or car?

Applicable general liability may help pay defense and covered property-damage liability. Identify the lock, door, frame or vehicle component being serviced separately from other damaged property, and check work-property, custody and professional terms. Customer ownership or permission to open it does not establish that repairing the worked-on item, replacing a lock or redoing work is insured.

Am I liable if an installed lock is later defeated?

The later break-in alone does not decide liability. Review your service, contract, handoff, later changes, evidence of cause, and actual claimed loss. Professional or general liability may help pay included defense and covered liability, but the insured security services, kinds of harm, exclusions, and reporting matter. A replacement, refund, guarantee or employee-theft allegation is not automatically the same claim.

Do I need a bond to be a locksmith?

Check the actual work and location with the relevant authority, and read any client condition. Do not infer a nationwide requirement from the trade name. If a bond is requested, identify its exact obligation, beneficiary, amount, claim conditions, and any repayment terms. A licensing or contract bond differs from client-theft or fidelity protection and does not prove every service or loss is insured.

Are my van tools covered if stolen?

Applicable inland marine may help repair or replace included equipment after covered theft. Check owned, rented or customer items, actual values and locations, unattended-vehicle or security conditions, proof, deductibles, and limits. The van, blank or lock stock, customer records, wear, breakdown and missed calls are distinct interests. Not every contents item must be individually scheduled or is automatically included.

Talk through your locksmith coverage

Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.

How can we help you get started?

Choose the quote that fits, and we’ll take it from there.

Have a question? Contact us