Skip to content

Telemarketing And Contact Center Insurance

A complaint about how your center made a call is different from a breach of the recording. Calling practices and customer-data protection need separate insurance attention.

The Southern Agency can help you consider campaign work, customer information, and your operator workforce.

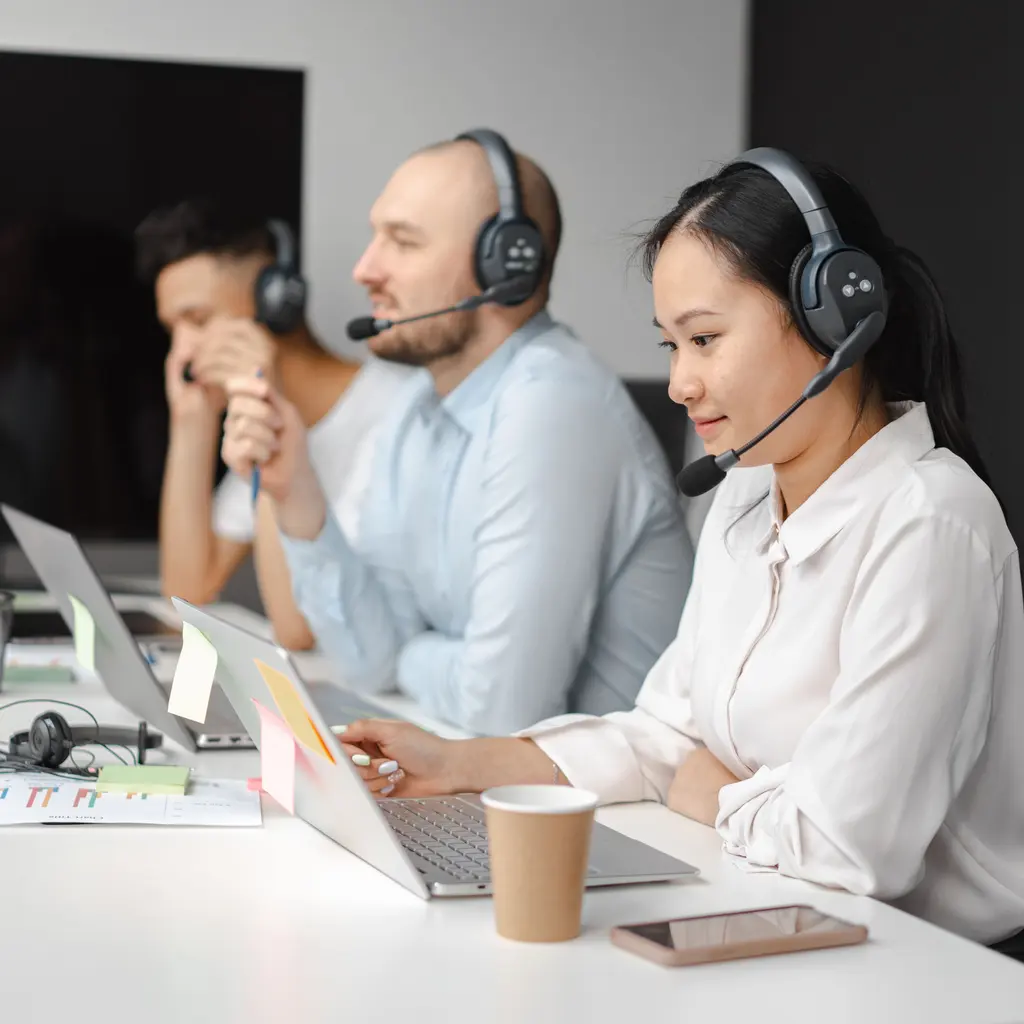
Contact-center staff wearing headsets and working at laptops.

Industry overview

You handle sales, collections or service campaigns for various clients. A failed phone system, an alleged calling-rule violation or a campaign error can create different types of risk for your center.

The Southern Agency can review your dialing methods, recording procedures, and campaign scopes to help you select appropriate insurance. We can help you identify if a claim relates to professional error, data privacy, or equipment failure, as calling-statute and recording terms may require separate, specific attention.

Risks worth discussing

Telemarketing and privacy regulation claims

Recipients may allege unlawful calls, misuse of their information or improper recording. Identify the actual communication, client, recipient, method, and jurisdiction. A statutory calling claim is not automatically a covered data-breach claim, and a privacy allegation or class-action label does not overcome an exclusion.

Customer data breach

A compromised account or platform may expose customer identities, payment details, or recordings actually accessible to it. Trace the records and provider involved rather than assuming every agent handles full payment data. Legal or client response duties and insurer-funded investigation, notification, and liability costs need separate review.

Errors in client campaigns or service

An incorrect script, order or account update can lead a client to seek reimbursement. Describe the service and authority given to staff and identify the loss alleged. Professional liability does not establish payment of every refund, service credit, campaign budget, or guaranteed sales result.

Business interruption from outages

A failed switch, internet connection, or hosted dialer can stop calls. Establish the cause, affected equipment or provider, duration and the center's own income or extra expense. The fact that a client's campaign stopped does not establish the center's business-income trigger or insure every client delay claim.

Large-workforce employment claims

Agents or supervisors may allege discrimination, harassment, wrongful termination, or unpaid wages. Identify the employer, employment or contractor roles, duties, and work locations. EPL and workers' compensation address different losses; wage-and-hour, benefits and contractual staffing promises are not automatically part of either response.

On-site property and equipment exposure

Fire, water or a power event can damage phones, workstations, and servers. Identify who owns or leases them, the sites and any remote or client property. The cause, location and actual property or breakdown terms matter; neither all water damage nor every electronic failure is included.

Situations to think through

These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.

  1. Hypothetical: Privacy and calling-rule allegation

    Hypothetical: Recipients allege a client's automated campaign called them without the required permission and sue the center. Liability terms that specifically include the declared work and statutory allegation may help pay covered defense and damages. Check the actual calling-statute and privacy exclusions; they can remove that response even when the complaint is framed as negligence or invasion of privacy. A client-approved list is not proof of permission or coverage, and statutory remedies and penalties need their own terms and legal review.

  2. Hypothetical: Breach of customer payment data

    Hypothetical: A compromised agent account exposes customer card details and personal records, leading to a forensic investigation and notification decisions. Included cyber response may help pay covered investigation and response costs, and included liability may help with a covered privacy claim. Check the affected records, provider, consent, notice, and limits. A legal or client notification duty does not establish every expense is insured; bank or card assessments need their own terms.

  3. Hypothetical: Telephony outage halts campaigns

    Hypothetical: A power event damages the center's phone switch and stops campaigns for several days. Included property or breakdown protection may help with covered repair, and an applicable income or extra-expense part may help with the center's defined loss. Establish the damage and cause, equipment and site, waiting period, limits, and restoration requirements. An undamaged internet or hosted-platform outage, lost client sales, and service-credit promises are not automatically the same covered loss.

Before you talk to an agent

What to have ready

Tick items as you gather them. Nothing here is saved or sent.

Questions to raise

  • Describe the actual inbound and outbound services, client markets, dialing methods, scripts, recording, and any collection work. Have qualified advisers assess applicable calling, recording, and privacy duties. Compare each allegation with the insuring terms and exclusions, including the Telephone Consumer Protection Act or other statutory-communications wording. A professional or cyber title is not evidence that these claims are included.
  • Match data response to records and recordings actually handled, access permissions, storage, and providers. Compare investigation, notification, restoration, privacy liability, and any bank or card-assessment terms and limits. Separate legal and client duties from insurer-funded costs, and do not treat cyber response as protection for every payment theft or transfer.
  • Trace phone, dialer, internet, and power dependencies before comparing interruption protection. Distinguish covered property damage, breakdown, security events, and other provider or software failures. Check the center's income and extra-expense calculation, waiting period, limits and restoration conditions separately from client lost sales, performance promises, and credits.
  • Review headcount, agent seats, payroll, turnover, employer and worker status, supervisor roles and work locations rather than assuming every center has one large hourly floor. Compare workers' compensation and EPL separately, including actual wage-and-hour, benefits, contract, and work-injury limitations.
  • Read the client and platform agreements before selecting limits or promising compliance. Identify declared services, insured entities, client roles, shared limits, defense costs, and any requested endorsements. Check prior work, known claims and continuity when campaigns, entities or policies change. If the form is claims-made, review the applicable prior-work date and claim and reporting conditions before a change.

Contract terms to check

  • Specify the center and client entities, services, markets, and responsibilities for scripts, contact lists, permissions, recording, changes, and suppression requests. Obtain qualified review of applicable law and actual authority; client approval, an indemnity, or an insurance requirement does not make every communication lawful. Compare the campaign and alleged act with the declared services and statutory-communications exclusions.
  • Allocate responsibility for collecting, accessing and storing customer records, recordings, and payment details, including actual platform and subcontractor roles. Address incident reporting, permitted disclosure, investigation, notification, and restoration, and compare consent and notice with the insurance terms. Legal, client and card-processing obligations can differ from the expenses and assessments a policy includes.
  • Read uptime, recovery, escalation, liability caps, service credits and performance promises against the actual property, breakdown, cyber, and interruption parts. Identify the center's own loss separately from a client's sales or campaign budget. Outsourcing the dialer or connectivity, or receiving a provider credit, does not itself insure every outage or remove every contractual responsibility.
  • Check each coverage, limit, insured-party, waiver, property-interest, and evidence request before committing. Identify the relevant endorsement and shared limits rather than relying on a certificate, and distinguish the center's liability from a client's independent acts. Review provider or fidelity instruments where requested; the label or a provider's insurance does not transfer every claim. Confirm availability and endorsement wording before promising to meet a client's request.

What the agent conversation looks like

Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.

  1. ListenReview your operations, current coverage, and past claims.
  2. AssessIdentify potential hazards and discuss ways to reduce risk.
  3. BuildDiscuss policy and carrier options, premium costs, and audits.
  4. SupportReview changes and help you plan ahead as your needs develop.

Questions owners ask

What are the biggest insurance concerns for a contact center?

Start with the actual services and allegations: campaign or account errors, unlawful communications, exposed customer records, interrupted calling systems, and workforce claims. Compare the parties, loss and trigger for each. A center handling inbound support, collections or recorded sales calls should describe that work rather than assume a generic call-floor policy includes all of it.

Does insurance address calling-rule or privacy claims?

Only the actual terms can establish that. Specifically included liability may help pay covered defense and damages if the work and allegation are included in the form, but statutory-communications exclusions can remove the response. A cyber privacy section may instead require an included data or security event. Read any policy exclusion for Telephone Consumer Protection Act claims or other communications laws, along with conduct provisions, remedies, and limits. A client-approved campaign or privacy label is not proof of cover; legal duties need separate qualified advice.

Why do we need cyber coverage?

A compromised system or account can expose the customer records, payment details, or recordings the center actually handles. Included cyber protection may help pay covered investigation, response, restoration, and privacy or security liability. Match data, systems, providers, consent, and notice with the terms. Not every notification, card assessment, calling-rule allegation, diverted payment, or platform outage is included.

What happens if our phone systems go down?

Establish the cause and the loss. Included property or breakdown terms may help repair damaged equipment; an applicable income or extra-expense part may help with the center's defined interruption loss. Security, software, utility, and outside-provider failures need their own triggers checked. Compare waiting periods, limits, and restoration requirements. Lost client sales, refunds, and uptime credits are not automatically the center's insured loss.

Do our clients require us to carry insurance?

Read the service agreement and private coverage, limit, party, waiver, and evidence requests. Compare them with policies and endorsements before promising compliance. A certificate does not amend coverage, and being insured for one liability interest does not settle every independent client act, statutory claim, or data obligation. Confirm availability and the exact endorsements and limits before committing to the client's request.

Are our agents covered for workplace injuries?

Workers' compensation may help pay medical and qualifying wage benefits for an included worker's covered work injury. Review the actual employer, employee or contractor status, duties, payroll, and work states, including remote roles. State requirements and benefits need qualified review. A high call volume, contractor label or employer policy elsewhere in a group does not establish that every agent, location, or repetitive-strain condition is insured.

Talk through your telemarketing and contact center coverage

Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.

How can we help you get started?

Choose the quote that fits, and we’ll take it from there.

Have a question? Contact us