

Guest slips and trips on the floor
Crowded aisles, spilled drinks, cords, and play areas for young children create slip-and-fall exposure throughout the arcade.
Try a different word, or check the spelling.
Your games can earn electronically while the counter still holds cash and redemption prizes. Property and crime protection need to distinguish cabinets, funds, and prize stock, with records that can establish a loss.
The Southern Agency can review who owns your machines, what guests can do on the floor and how you track cash and prize stock.
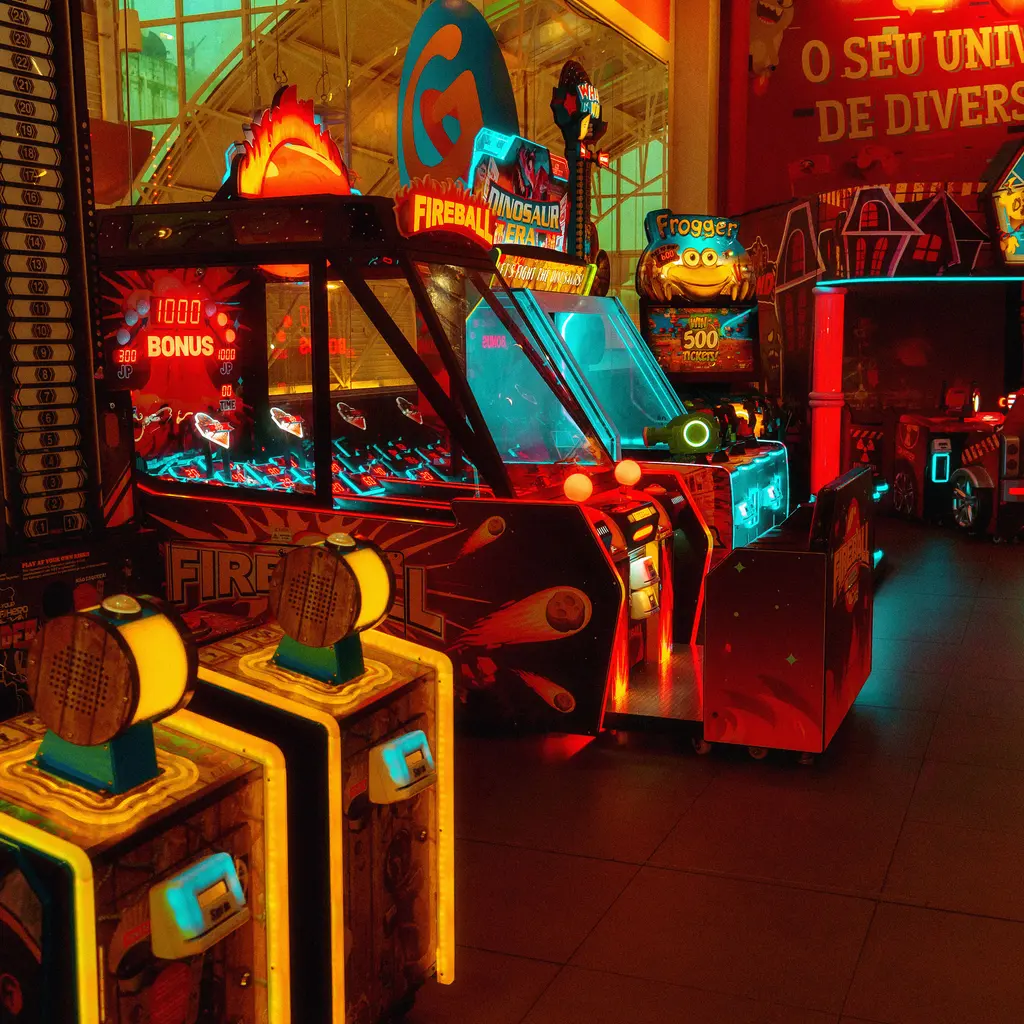
You bring people together to play electronic and redemption games, where an injury on your floor or a breakdown of your machines can quickly disrupt your business.
The Southern Agency can review your specific mix of video and redemption games to help you select insurance.
Crowded aisles, spilled drinks, cords, and play areas for young children create slip-and-fall exposure throughout the arcade.
Video, redemption and claw machines can be damaged by electrical events or vandalism, or stolen. Losing several cabinets can mean both replacement costs and fewer games earning revenue.
A surge or breakdown can disable several machines at once. The revenue loss may depend on how much of the floor can keep operating while repairs are made.
Cash at the counter and prizes awaiting redemption can be stolen by an intruder or insider. A discrepancy in token or play-balance records can also make the size and cause of a loss harder to establish.
Children may be injured around games or play areas. A dispute can concern supervision as well as the condition of the premises, particularly during organized parties.
Card-based games and gift cards can involve customer or payment records. A breach can lead to investigation and notification costs.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Hypothetical: a guest slips on a spilled drink near a popular game and sues over the resulting injury. General liability may pay defense costs and covered damages. The injury alone does not decide whether the arcade is legally responsible; that depends on the facts.
Hypothetical: a surge damages the electronics in several game cabinets while the rest of the floor stays open. Equipment breakdown may pay covered repairs if the machines and failure qualify. Lost income requires its own protection and a measured loss, taking continuing game revenue and any waiting period into account.
Hypothetical: thieves break in overnight and take cash and prize inventory from the counter. Crime insurance may pay an insured money loss, while property or crime coverage may address the stolen prizes. Different limits and proof requirements may apply to cash and prize stock.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Guest claims, damaged machines, lost income, and theft are different needs. A package may address some of them, but ask what it includes for the arcade's games and other activities. Employee injury and any payment-data exposure need attention too.
Property insurance may pay for covered damage or theft, while breakdown protection addresses qualifying internal failures. Bring current replacement values and lease obligations so the review includes machines the arcade owns and those it must insure for someone else. Limits and valuation terms affect the payment.
It is worth reviewing when an electrical or mechanical failure could take several games out of service. Confirm which machines and failures qualify, then review any lost-income protection and waiting period. Other games may keep earning, so an income claim is not automatically the full floor's revenue.
Compare employee-theft protection with cover for money stolen by an outsider and for prize inventory. Check limits at the counter, in storage, and during deposits, as well as the records needed to support a loss. An accounting shortage alone does not identify the cause or establish a covered theft.
The lease may specify liability limits and additional-insured status for the landlord. Bring its insurance schedule and amendments before agreeing to terms. Confirm the endorsement rather than relying on a certificate. A contract request does not mean every provision can be arranged.
An injury claim may be covered, but the policy needs to fit how the arcade operates. Ordinary game play, motion devices, climbing features, and parties with staff supervision can raise different questions. Describe who supervises children and any outside party operator.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.