

Robbery and cash exposure at branches
Cash held in tellers' drawers, vaults, and ATMs makes branches a target for robbery and theft losses.
Try a different word, or check the spelling.
Your customer's account, the cash in the branch and the bank's own property are different interests. Crime, cyber and banking-service liability need coordinated terms without being mistaken for deposit protection.
Bring branch and ATM interests, cash-transfer authorities and the services you retain or outsource.
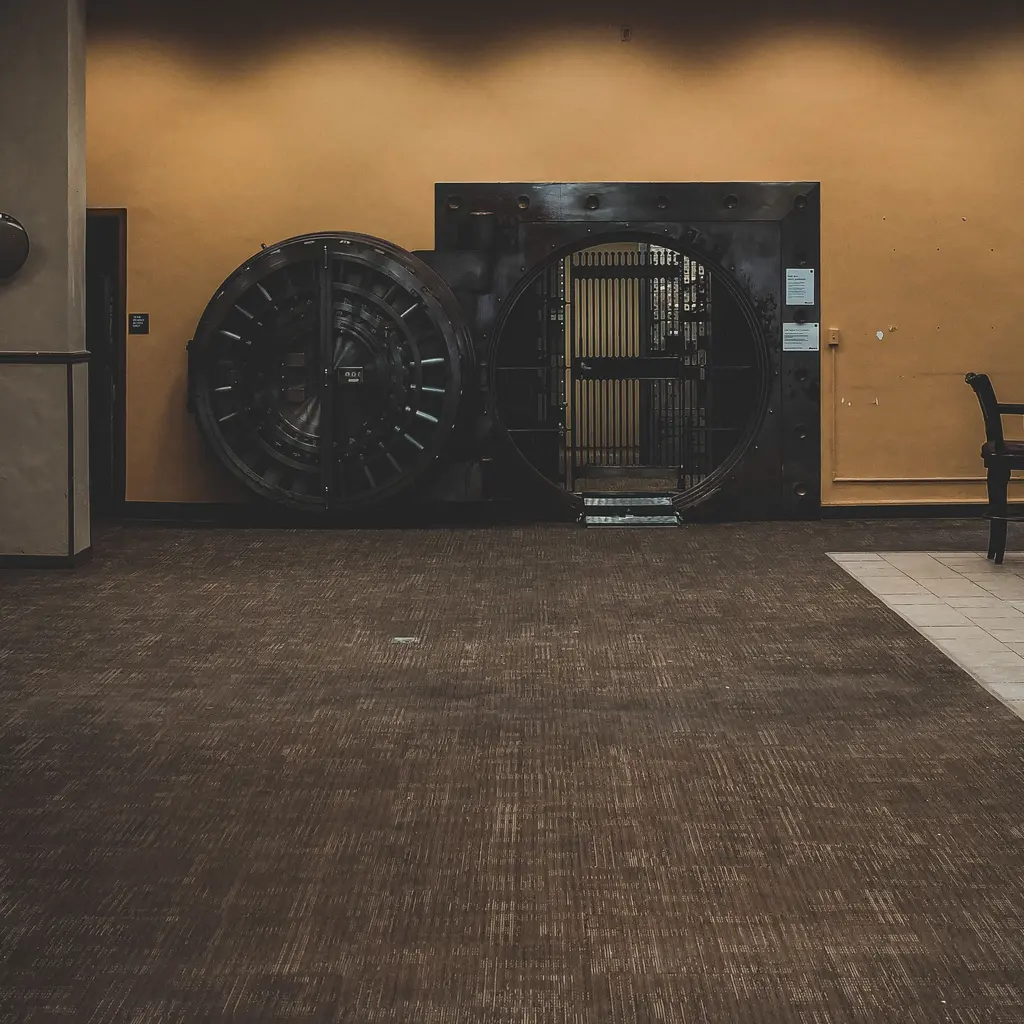
Your bank welcomes the public into branch lobbies and manages substantial amounts of cash and customer data. This combination of public traffic and financial-service operations creates risks ranging from slip-and-fall incidents to complex cyber and fraud exposure.
The Southern Agency can review how your branches, cash services and digital channels work together. We can compare financial-institution bond, cyber and banking-service liability terms with your actual funds interests and customer duties, then examine property, staff and governance protection without treating these policies as deposit insurance.
Cash held in tellers' drawers, vaults, and ATMs makes branches a target for robbery and theft losses.
Public foot traffic through lobbies, entrances, and parking creates slip-and-fall and other premises liability exposure.
Large sums passing through the bank invite embezzlement, forgery, and social-engineering fraud against accounts and funds.
Customer account and payment information makes a network compromise a serious breach, notification, and liability exposure.
Shareholders, regulators, and borrowers may challenge lending oversight, capital decisions, and compliance.
Mistakes in loan administration or financial advice can lead to errors-and-omissions claims from customers.
Branch and back-office staff face injury exposure, and a large workforce raises harassment and wrongful-termination potential.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Suppose a robber takes cash from teller drawers during branch hours. Review the bond's on-premises robbery grant, insured funds interest, limits and discovery/notice requirements. Repairing damaged counters or a vault door is a different interest from replacing the stolen cash.
Suppose a customer slips near the entrance and alleges that tracked-in water was left unaddressed. General liability may address the covered claim after the conditions and the bank's premises duties are established. Any no-fault medical-payments provision is separate from the customer's full demand.
Suppose an impersonated customer instruction leads staff to send funds to an attacker's account. Establish whose money was lost and how the instruction was received and verified. Actual transfer-fraud or social-engineering terms, limits and conditions determine possible recovery; a computer-fraud heading or breach-response benefit alone does not settle it.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Banks commonly hold property, crime, general liability, cyber, D&O, professional liability, and workers' compensation. The mix depends on size and operations, subject to underwriting.
Crime or financial-institution coverage may respond to robbery and theft of cash, depending on the specific policy, endorsements, and facts of the loss.
Yes. Because the public enters branch lobbies, general liability is commonly needed for customer injuries and property damage, subject to policy terms.
A financial-institution bond/crime grant may address defined theft/fraud loss; cyber may address defined data/security events, response and liability. Customer funds, voluntary transfers, and vendor systems need actual terms reviewed. Neither policy label establishes credit/default or deposit protection.
Directors face claims from shareholders, regulators, and borrowers over governance and lending. D&O may respond to defense and liability, depending on the policy and facts.
Yes. Branch count, cash exposure, assets, and loss history are common rating factors. Coverage and pricing depend on underwriting.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.