

Robbery and branch cash exposure
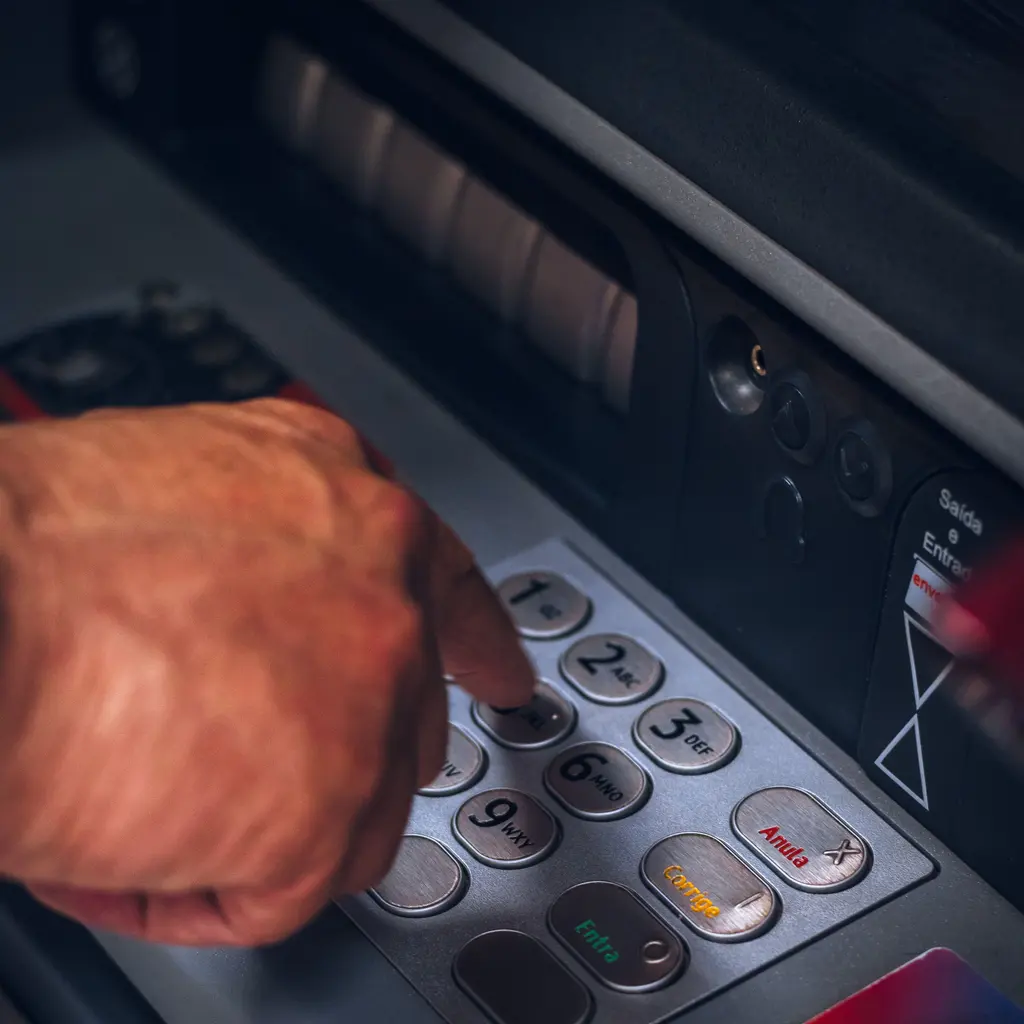
Cash in teller drawers, vaults, and ATMs makes depositor-facing branches a target for robbery and theft losses.
Try a different word, or check the spelling.
Your mortgage concentration can make loan-quality disputes a different concern from theft at a branch. Lending-error, financial-institution bond and property protection need their actual terms, rather than one broad label for the association.
The Southern Agency can help review your financial-institution, lending, and branch-premises insurance needs.
You operate branches, maintain vaults and ATMs, and process consumer loans and residential mortgages. A breach of sensitive data, a robbery, or a mortgage-origination error can lead to complex financial and regulatory claims.
The Southern Agency can review your actual mortgage duties, branch traffic, and data handling to help select appropriate insurance, such as comparing professional liability for lending errors against premises liability for branch traffic.
Cash in teller drawers, vaults, and ATMs makes depositor-facing branches a target for robbery and theft losses.
A residential-lending concentration creates errors-and-omissions and repurchase exposure when disclosures or underwriting are defective.
Depositor funds and mortgage proceeds passing through the thrift can be embezzled or diverted. Compare the actual loss with financial-institution bond or crime grants; a fraudulent loan or uncollectible balance is not automatically a fidelity loss.
Depositor and borrower information makes a network compromise a serious breach, notification, and liability exposure.
Examiners, shareholders, and members may challenge lending concentration, capital adequacy, and compliance decisions.
Public traffic through branch lobbies, entrances, and parking creates slip-and-fall and premises liability exposure.
Branch and lending staff face injury exposure, and the workforce raises harassment and wrongful-termination potential.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A defect in a funded mortgage prompts a repurchase or borrower claim. A professional liability policy may respond to defense and liability, depending on policy terms and the facts. Separate actual borrower allegation/defense from loan buyback, credit principal, and warranty fulfillment.
Cash is taken during a branch robbery. A crime policy may respond to the stolen funds, subject to the specific policy, endorsements, and exclusions. Review actual bank bond/on-premises cash grant, ownership, limits, and discovery/notice.
A compromise exposes depositor and borrower data, triggering notification costs. A cyber policy may respond to breach response and liability, depending on policy terms. Review actual depositor/borrower data and insured vendor event, response consent, and notification duties.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Compare financial-institution bond/crime, property, professional, cyber, management, premises and worker interests against actual services, funds and branches. The policies address different losses. Have qualified advisers confirm applicable charter and regulatory obligations; a generic insurance list does not demonstrate compliance or protect loan principal.
Identify actual charter, services and mortgage concentration. Commercial banks can perform the same lending/branch functions; the label does not establish guaranteed repurchase cover or an examiner-prescribed insurance program.
Review actual funds/covered persons, applicable charter/regulatory obligations, and bank bond wording/limits with qualified advisers. Generic crime is not proof of compliance, every fraud loss or depositor protection; lending default and repurchase duties are separate.
Crime coverage may respond to robbery and theft of cash, depending on the specific policy, endorsements, and the facts of the loss.
It stores depositor and borrower data. Cyber coverage may help with breach response and liability if systems are compromised, depending on the policy.
Branch count, deposits, lending concentration, data, and loss history are common rating factors. Coverage and pricing depend on underwriting.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.