

Product defects in mission-critical equipment
Components and systems supplied for defense use can fail in service, creating product liability and completed-operations exposure with serious consequences.
Try a different word, or check the spelling.
Your plant may hold government-entrusted property while your team accepts design, integration, or servicing duties. Property, product and professional protection should fit those interests and defense end uses, separately from warranty work, recall costs, and late-delivery penalties.
The Southern Agency can compare your product, design and data risks with the insurance requested in your actual contracts.
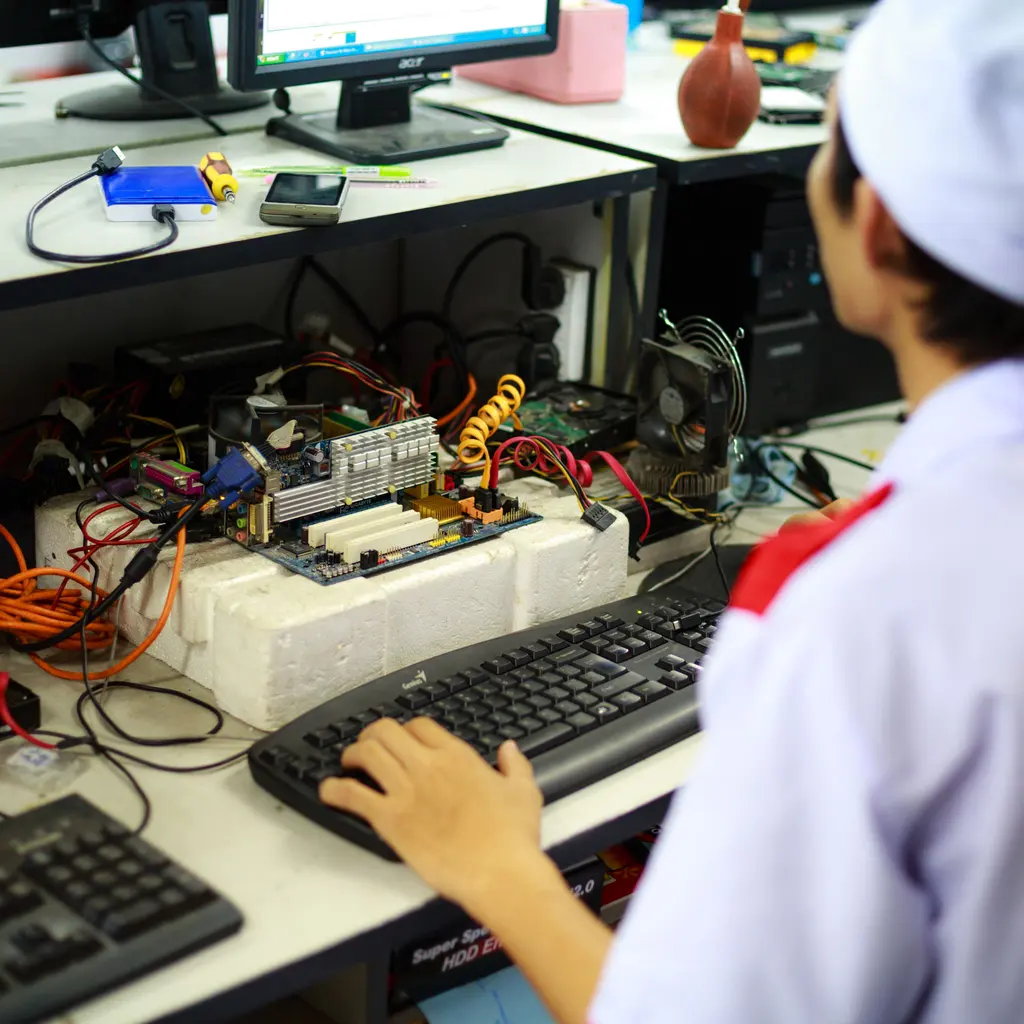
Your firm designs, manufactures, and services components or systems for defense agencies. A design error, defective product or data breach carries high stakes, often governed by strict federal acquisition and export regulations.
The Southern Agency can review your production operations and contract obligations to help you select appropriate insurance. For instance, we can help assess whether your product liability coverage matches the specific defense-related end-uses of your equipment.
Components and systems supplied for defense use can fail in service, creating product liability and completed-operations exposure with serious consequences.
Engineering, design, and integration responsibility creates professional errors-and-omissions exposure when deliverables fall short of specifications.
Export-controlled and sensitive technical data make the firm a cyber target, with regulatory and contractual fallout from a compromise.
Plant, specialized machinery, and inventory face fire, breakdown, and business-interruption exposure that can halt contract delivery.
Machining, moving components and servicing equipment can injure staff. Plant work and field assignments can involve different employers, duties and locations that need to be described in the workforce review.
Your prime or subcontract may specify insurance, indemnity and duties passed down to other firms. Compare those actual clauses with the issued policies; a contract requirement does not itself create coverage.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A supplied component fails in service and the customer alleges damage to other equipment. Products liability may help with covered defense and damages where the component and defense end use are accepted. Separate the alleged third-party harm from replacing your component, warranty work, recall and mission or delivery penalties.
An intrusion exposes controlled engineering files and prompts forensic, notification and regulatory inquiries. Cyber terms may help with covered response and liability where the data, systems or provider event are included. Compare reporting, consent and loss provisions; compliance corrections, every fine and all contractual costs are not automatic benefits.
An internal failure stops a critical production machine and delays a contract delivery. Equipment breakdown may help repair covered damage, with lost income or extra expense only under applicable purchased terms. Identify the cause, restoration period and business loss separately from the customer's delivery penalties.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Products terms may address covered third-party injury or property damage caused by accepted equipment. Professional terms address covered allegations involving insured design or engineering services. Identify both roles if you perform them; replacing a failed component or meeting a specification is not automatically a benefit under either policy.
A breach of controlled technical data can trigger regulatory and contractual consequences. Cyber coverage may help with breach response and liability, depending on the specific policy and facts.
Your actual prime or subcontract may set insurance and indemnity duties, including requirements passed to other firms. Bring those clauses for comparison with operations, insured parties and endorsements. The contract or certificate does not itself establish available coverage, compliance, immunity or protection from every penalty.
Commercial property and equipment breakdown may help with physical loss and machinery failure, and business income coverage may respond to resulting downtime, depending on policy terms.
Confirm that the defense end use and completed products or services are accepted. Injury or damage to others differs from your defective item, warranty, redesign, rework, removal or recall. Mission and delivery penalties also need separate terms; handing over the equipment does not establish coverage for every later demand.
Underwriters weigh product type, design responsibility, facility values, data-security controls, and claims history. Pricing and availability depend on underwriting.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.