

Plant failures
Electrical and cooling failures can damage equipment or stop operations. Hardware repair, extra expense, and lost income need applicable terms.
Try a different word, or check the spelling.
Housing a customer's server does not by itself make you responsible for processing its data. Your facility protection should identify the ownership and services accepted, with hardware repair, extra expense and income interests distinguished from tenant financial demands or a cyber incident.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
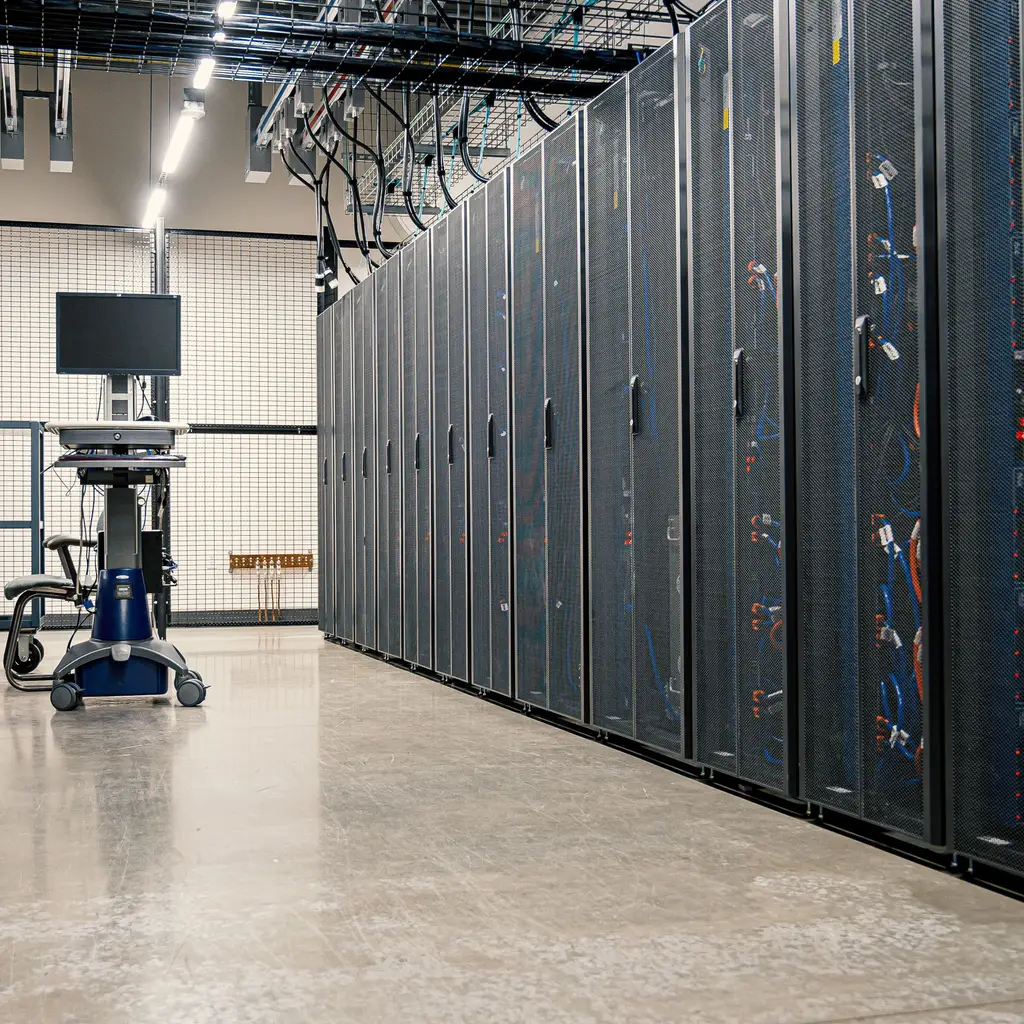
You protect critical power, cooling, and computing infrastructure for your own use or for customers. A power switchgear fault or cooling failure can damage equipment and trigger expensive operational outages.
The Southern Agency can review your infrastructure, hardware ownership and actual customer services with you. We can compare accepted property/breakdown causes, restoration time and purchased income/extra expense with tenant interests and service claims, rather than assuming an uptime promise is a property benefit.
Electrical and cooling failures can damage equipment or stop operations. Hardware repair, extra expense, and lost income need applicable terms.
Fire, water, and location-specific catastrophe exposures can affect concentrated values. Flood and earthquake are not automatically included.
Tenant-owned hardware and financial-loss claims may sit outside ordinary owned-property/GL terms. Housing servers alone does not establish data-processing responsibility.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
An insured electrical failure causes shutdown. Breakdown and included income/extra expense may address eligible costs; customer SLA penalties are not ordinary business-income benefits.
A chiller failure overheats equipment. Resulting hardware damage requires suitable terms and ownership interests; data restoration and customer losses are separate questions.
A discharge damages servers. Property may pay an insured water/suppression loss, subject to cause and exclusions; the tenant's assets need an appropriate insured interest.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Not automatically. It addresses defined insured income loss, while customer claims and contractual remedies have different terms.
Do not assume it. Review location-specific perils and applicable exclusions, limits, and deductibles.
Only where the policy includes the interest. Ownership and custody must be identified.
No. Insured breakdown, resulting loss, and interruption conditions must be met; maintenance and wear differ.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.