

Passenger injuries
Boarding, travel, and exit can each produce a claim. Auto and premises liability need a consistent boundary.
Try a different word, or check the spelling.
A standard vehicle value may not rebuild your stretch conversion. Review the custom fittings and passenger use on the policy, not just the make and model.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
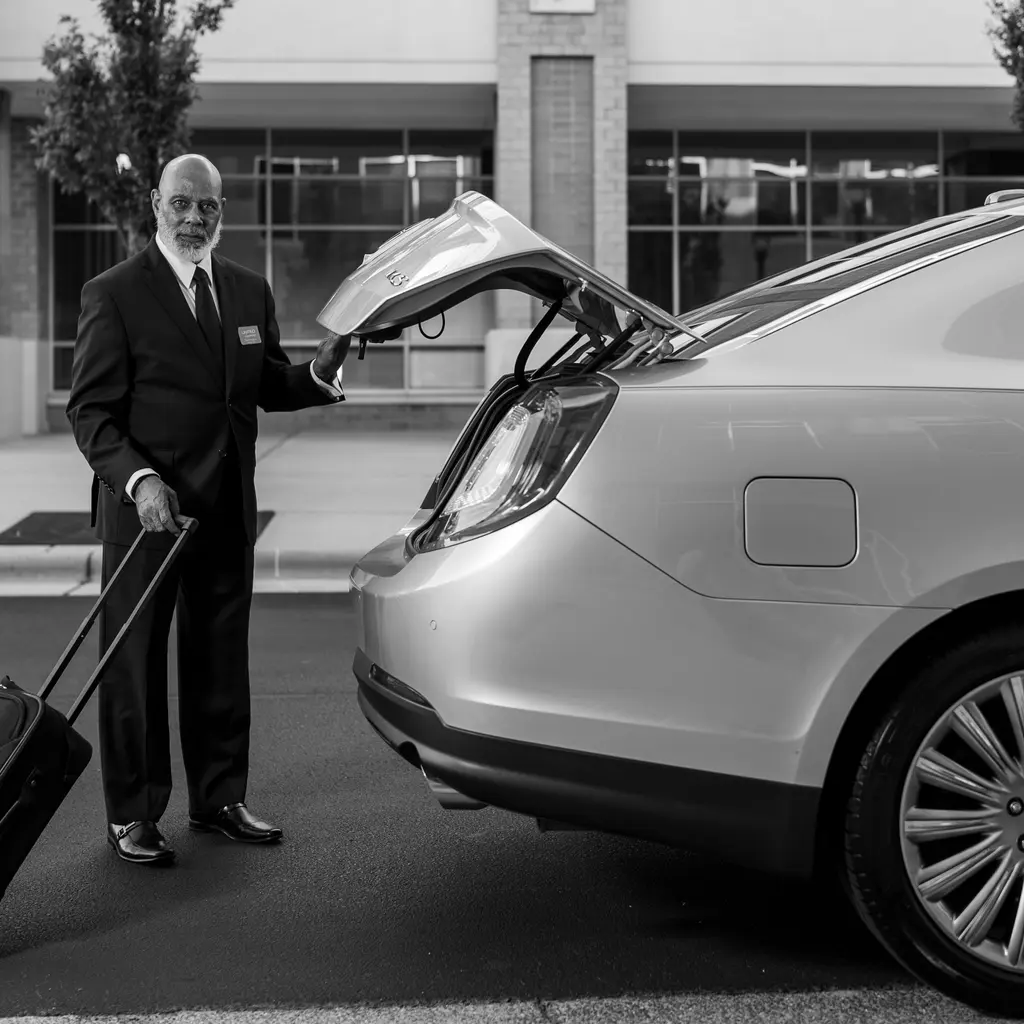
You provide chauffeured transportation for events, which means your business relies on high-value vehicles and the reliable movement of passengers. An accident involving these customized vehicles can cause significant service gaps and liability claims.
The Southern Agency can review your fleet, chauffeur responsibilities, and trip types to help you select appropriate insurance. We can help you clarify how your policy covers passenger-for-hire risks compared to ordinary vehicle use.
Boarding, travel, and exit can each produce a claim. Auto and premises liability need a consistent boundary.
Stretch conversions and fitted interiors can cost more to restore than a standard vehicle's stated value suggests.
Serving drinks, allowing passengers to bring them and arranging a third-party bar can create different liability questions.
A missed wedding booking can produce refund demands. Stored payment and itinerary data create a separate privacy exposure.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
The limousine collides with another vehicle while carrying a wedding party, and passengers claim injuries. Accepted passenger-for-hire auto terms may address covered defense and damages. The insured vehicle, trip use and liability facts matter; a missed-event refund is a separate demand.
An injured person alleges your chauffeur improperly served alcohol to a passenger. Accepted liquor terms may address covered defense and damages, depending on the actual service and exclusions. This does not establish negligence or the same response when passengers bring their own drinks.
Vandals damage the fitted interior of a parked stretch vehicle. Purchased physical damage may address an included vandalism loss. Confirm conversion and custom-equipment values, valuation and deductible; insuring only the base vehicle can leave the restoration cost unmatched.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Passenger-for-hire auto is central, with physical damage, employee injury, and non-auto liability reviewed around the fleet's services.
Describe who supplies and serves it. Liability law and insurance treatment can differ from a passenger simply bringing drinks.
Review valuation, conversions, and custom equipment on the physical-damage policy; ordinary market value may not match restoration cost.
Yes. Tell the insurer about hours, passenger capacity, and event types. Excess limits cannot cure an excluded operation.
Consider it when handling itineraries, account access, or payment information, including duties retained when using a reservation vendor.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.