

Authenticity and downstream loss
A mislabeled or defective part can damage a customer's product. Replacing a lot, lost production, and intentional misrepresentation may be excluded.
Try a different word, or check the spelling.
Replacing a suspect component lot is different from a claim that a part damaged your customer's finished product. Component insurance needs the actual authenticity and product exclusions considered, with static-sensitive stock and each domestic, air, or ocean shipment treated on their own terms.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
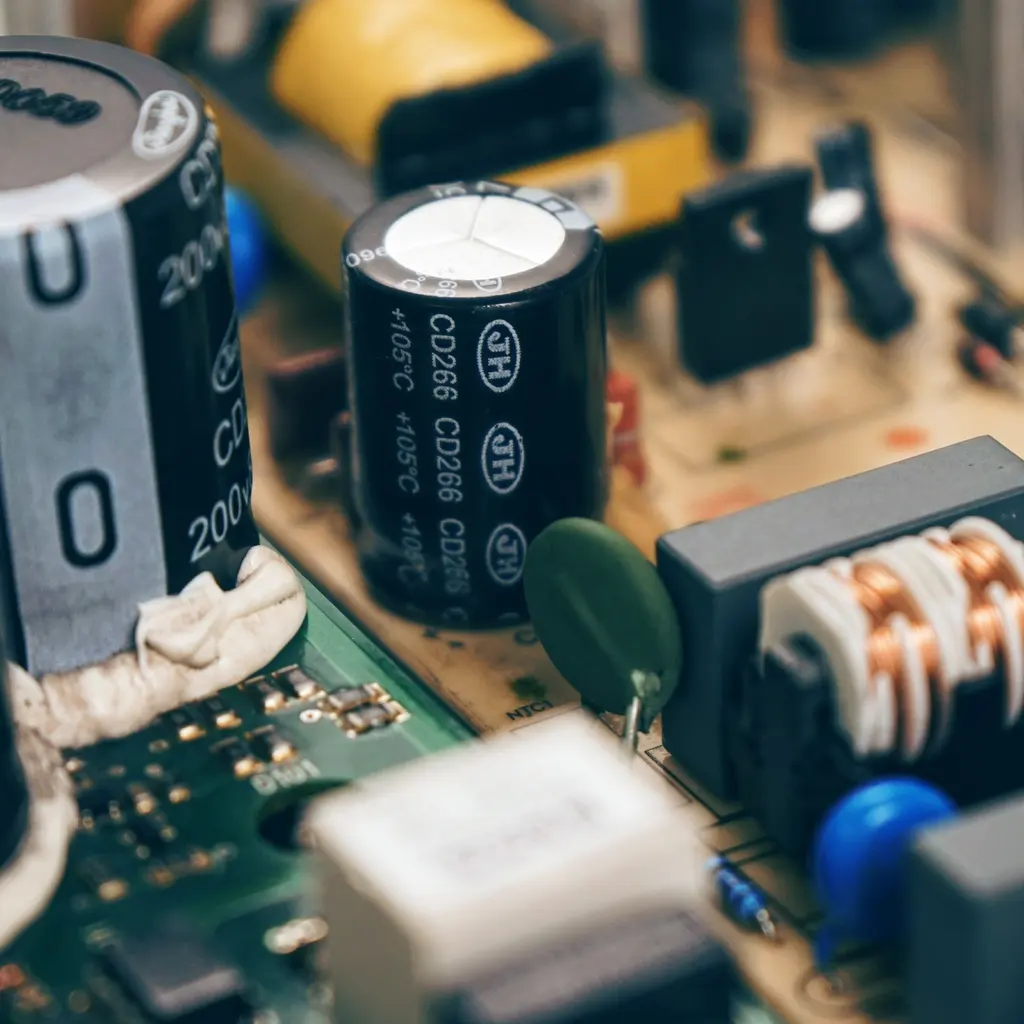
You distribute electronic components whose identity and lot history matter when a customer reports failed boards or assemblies. Static, moisture and handling can also damage valuable stock before delivery. International parcels and changing supplier payment instructions add different transit and funds-loss questions.
The Southern Agency can review your sourcing, stock controls and shipping stages alongside the parts and uses you supply. We can help compare product claims with suspect-lot replacement, insured stock damage and payment diversion, without treating those losses as one coverage.
A mislabeled or defective part can damage a customer's product. Replacing a lot, lost production, and intentional misrepresentation may be excluded.
Static, moisture, and handling can damage stock. Inherent defect, gradual deterioration, and price obsolescence are not automatically covered.
Domestic, air, and ocean shipments need suitable territorial terms. Unauthorized transfers and willingly authorized fraudulent payments may be treated differently.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
Ready to compare options?
Get a quote for Electronic Parts and Equipment Distributor Or call 1-800-777-1TSAThese hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A manufacturer alleges counterfeit parts damaged boards. Product cover may address a covered physical-damage claim, but replacing suspect stock, pure production loss, and knowing conduct need separate review.
A forged instruction redirects payment. Crime/cyber pays only if an applicable agreement includes the transfer, insured funds, and authorization facts; fraud alone does not establish cover.
Components are stolen during international shipment. Appropriate cargo cover may address the insured interest if territory, mode, security, and value fit; domestic transit terms may not.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
No. The payment loss must fit a specific theft/social-engineering agreement, not merely involve email.
No. Alleged damage, knowledge, exclusions, and insured products determine the response.
Only where the territory, mode and insured interest are included; ocean stages may need marine cargo terms.
No. The cause and sensitivity-related exclusions must be reviewed.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.