

Product and selection allegations
A supplied apparatus can be alleged defective or unsuitable. Injury/property damage, professional advice, and warranty refunds have different coverage triggers.
Try a different word, or check the spelling.
The same reel count can represent a different value as wire prices move. Your electrical-stock limits need those actual peaks, while selection advice, apparatus damage, and a contractor's unpaid account belong to different insurance questions.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
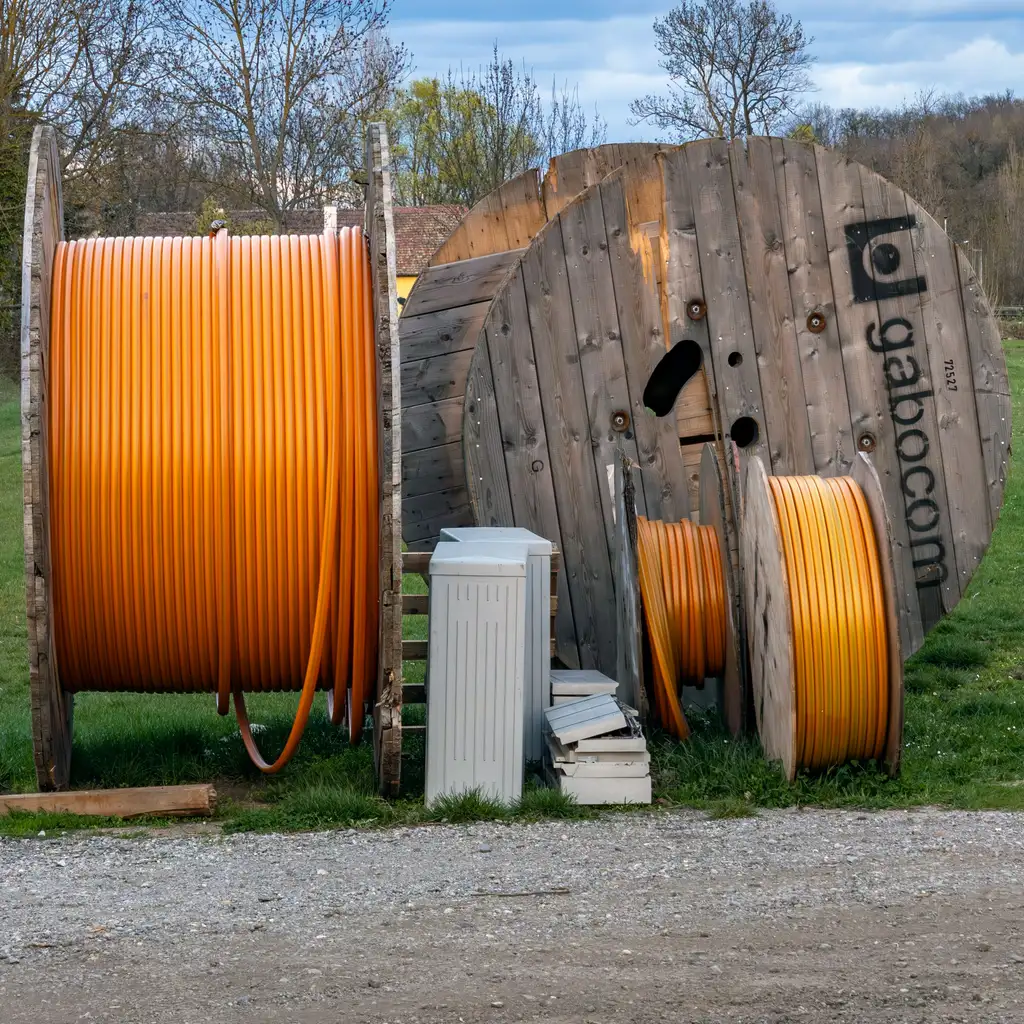
You supply electrical apparatus, wire and job-site materials to contractors and facilities. A dropped reel can damage stock during loading, while a breaker alleged to cause a fire can draw your business into a claim after delivery.
The Southern Agency can review your counter, delivery, and storage practices to help you select insurance covering your stock and potential liability arising from the apparatus you supply.
A supplied apparatus can be alleged defective or unsuitable. Injury/property damage, professional advice, and warranty refunds have different coverage triggers.
Reels and apparatus can be dropped or stolen. Stock totals can change with quantities and prices, making valuation and peak review important.
Will-call buyers, forklifts and delivery trucks create premises, loading, and road risks. Contractor credit default is a separate business loss.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A buyer falls near the collection area. GL may address a covered injury claim, subject to responsibility and incident facts.
A supplied breaker is alleged to contribute to a fire. Products cover may address covered resulting damage; replacing the breaker or paying a performance guarantee needs separate terms.
Wire is stolen during a jobsite stop. Suitable transit/theft cover may respond if ownership, security, and unattended-vehicle conditions fit; auto physical damage alone does not insure the wire.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Not necessarily. An unsuitable recommendation without covered damage can be an economic service dispute.
Ordinary credit default is not automatically a theft/fraud loss.
Not by themselves. Review values for actual physical-loss terms.
No. Liability, coverage, and any medical-payments conditions determine response.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.