Skip to content

Major Airline Insurance

The reservation record stays in your systems long after a passenger leaves the aircraft. Data protection and management liability need their own attention alongside the airline's flight and ground risks.

The Southern Agency can help you align your enterprise insurance policies with your specific station network and operational workforce.

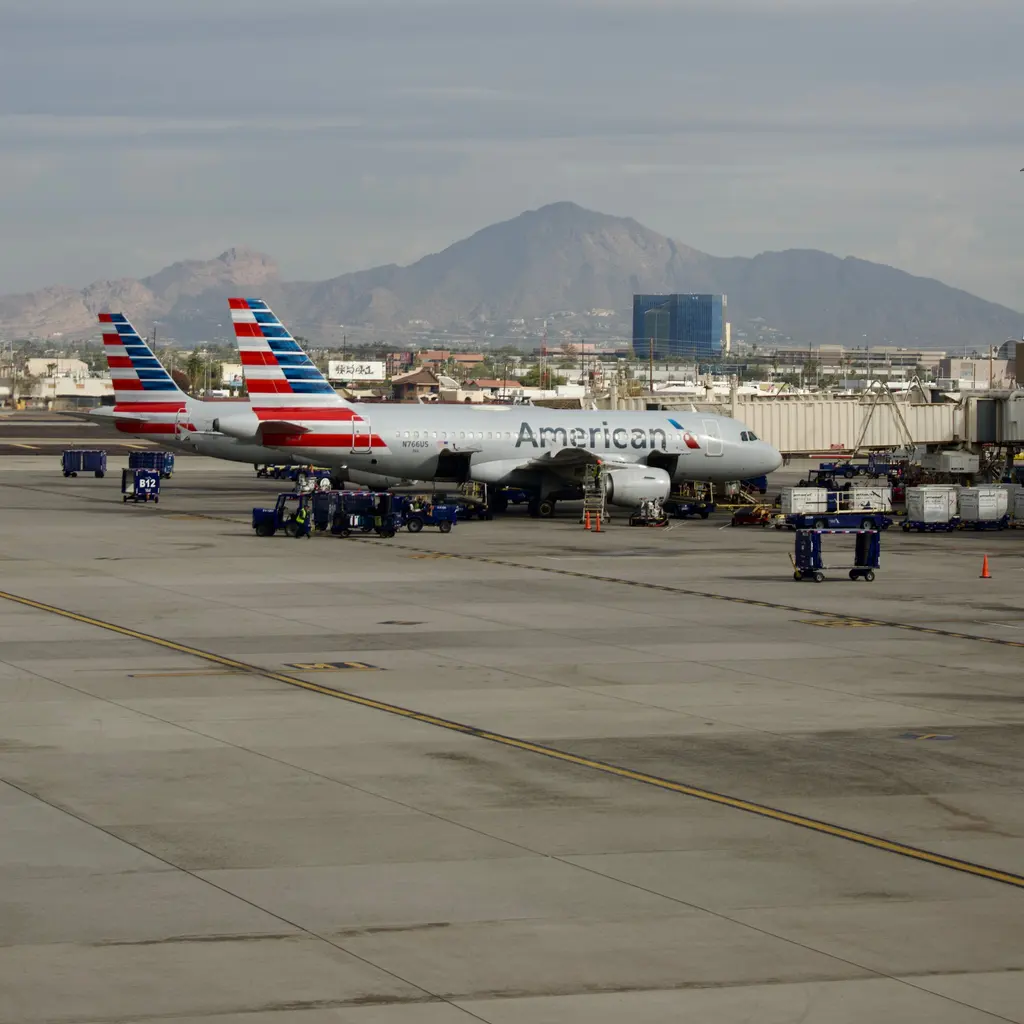
Passenger jets at adjoining airport gates, with baggage carts and ground equipment around them.

Industry overview

You run scheduled passenger flights through stations, maintenance bases and ground-service providers. Alongside aircraft and passenger risks, a reservation breach, an employment complaint or a claim against the board needs its own examination of the people, systems and decisions involved.

The Southern Agency can review your network structure and governance to help select appropriate insurance for your enterprise operations. For example, we can assist in distinguishing between employee-injury benefits and liability coverage for management decisions.

Risks worth discussing

Reservation and loyalty data

Passenger, payment, and loyalty information may be held by the airline and outside providers. A compromise can create investigation, notification, and privacy-claim costs, with responsibilities depending on the data and incident.

Workforce and employment claims

Termination, discrimination, and harassment allegations can arise across flight, maintenance, ramp, and customer-service roles. Identify the employing entities and locations rather than use an assumed workforce total as the coverage boundary.

Governance and management liability

Directors and officers can face claims over strategic, financial, and disclosure decisions. The alleged act, insured capacity, claimant, and company’s indemnification obligations matter; a business loss is not automatically a management-liability claim.

Terminal and ground operations injuries

Passengers and visitors can be injured at terminals, gates or ramps. The activity and the airline, airport or handler’s duties matter to premises and aviation liability; a ground location alone does not determine the policy.

Network-wide property and fleet risk

Hubs, maintenance bases, ground vehicle fleets, and equipment across the system create broad property and auto exposure.

Crime and financial-controls exposure

Employee theft or fraudulent payment instructions can divert company funds. The actor, ownership of the loss, transfer method, and terms for theft and fraud matter; not every fraudulent instruction is insured on the same basis.

Coverage worth discussing

Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.

Situations to think through

These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.

  1. Hypothetical: Passenger data breach

    Hypothetical: an intrusion exposes passenger records, prompting notification and regulatory-response costs. Cyber insurance may pay covered response expenses and privacy-defense costs. Regulatory investigations, penalties and payment-card demands are separate questions under the policy and applicable law; the breach does not make every resulting cost insured.

  2. Hypothetical: Shareholder management claim

    Hypothetical: investors allege the board mismanaged a strategic decision and seek damages. D&O may pay covered claims against insured directors or officers, or the company where included. Defending that allegation is different from reimbursing the airline's unsuccessful investment.

  3. Hypothetical: Terminal injury claim

    Hypothetical: a passenger is injured in a gate area operated by the airline and seeks damages. Applicable premises or aviation liability may pay covered defense costs and damages, depending on the activity and responsible parties. The gate-area address alone does not establish which coverage responds.

Before you talk to an agent

What to have ready

Tick items as you gather them. Nothing here is saved or sent.

Questions to raise

  • Identify insured entities and operations across the network, including outside handlers, maintenance providers, and leased sites. Match aviation and other primary policies with any intended excess rather than treat enterprise size as a limit formula.
  • Map ticketing, payment, and loyalty data and providers, incident responsibilities, and the causes of possible system outages. Separate response and privacy claims from ordinary refunds, card assessments, and lost bookings.
  • Describe ownership, investor profile, board roles, and company indemnification. Compare individual, reimbursement and entity interests in D&O; route and capital decisions do not make every business loss an insured claim.
  • List employing entities, flight, and ground roles, locations, and payroll. Employment-practices claims, employee injury benefits, and labor or benefit obligations need their respective terms.
  • Trace cash, deposits, and vendor payments, including who can authorize transfers and verify changed instructions. Match employee theft, computer fraud, and impersonation to the policy’s crime grants rather than rely on the word fraud.

Contract terms to check

  • Airport, gate, terminal, ground-handler, and maintenance agreements should identify control, duties, property interests, and the parties’ insurance requests. A certificate does not add coverage or establish that every agreed indemnity is insured.
  • Read partner, catering, and other service agreements for responsibility, incident reporting, and performance or reimbursement promises. Separate a service obligation from the trigger for an insured liability or income loss.
  • Data-provider and payment agreements should identify incident duties, retained information, and any assessments or reimbursement demands. Fraudulent payment and privacy-response costs may involve different policies and conditions.
  • Compare the entities, people, and legal obligations in board-indemnification and employment arrangements with D&O, EPLI, and employee-injury terms. No contract or policy heading establishes that every corporate or labor obligation is covered.

What the agent conversation looks like

Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.

  1. ListenReview your operations, current coverage, and past claims.
  2. AssessIdentify potential hazards and discuss ways to reduce risk.
  3. BuildDiscuss policy and carrier options, premium costs, and audits.
  4. SupportReview changes and help you plan ahead as your needs develop.

Questions owners ask

What coverages matter most beyond aircraft for a major airline?

The relevant functions include cyber response and privacy liability, management claims, employment practices, employee injuries, facility damage, and direct theft or fraud losses. Match them to the airline’s operating entities and duties. They complement aircraft hull and aviation liability; this list does not prove a complete flight program or rank the right limits.

Why is cyber coverage critical for a large carrier?

Reservation, payment, and loyalty systems and their providers can hold passenger information and support bookings. Cyber insurance may pay covered response, restoration, and privacy-claim costs. Provider outages and lost booking income must meet the insured-event and interruption conditions. Card demands and regulatory proceedings are separate coverage questions.

How does management liability apply to an airline board?

D&O may pay covered defense and liability costs for claims about insured management acts. Identify the individuals, company indemnification and any entity-claim cover. A shareholder allegation is different from the airline’s own operating loss; neither a failed investment nor a corporate penalty automatically establishes an insured D&O claim.

Is a large workforce a distinct exposure?

Actual employing entities, roles and jurisdictions matter, not a universal headcount for a major airline. EPLI may address covered employment allegations, while workers’ compensation addresses insured employee injuries under applicable law. Neither policy heading establishes every provider worker, payroll dispute, benefit obligation or international activity is covered.

Why include crime coverage?

Employee theft and specified fraud can cause direct financial loss in cash and vendor-payment flows. Crime insurance may pay an insured loss, but impersonation, computer fraud and voluntarily authorized transfers must fit the covered loss types and transfer conditions. A cyber incident or fraudulent instruction alone is not proof that stolen funds are covered.

How are limits set for an enterprise-scale carrier?

Describe the actual operations, entities, exposures, and contract requests, then compare primary limits, retentions, and intended excess. Separate aviation from management, employment, cyber, and other liabilities when checking layers. Network size or a large umbrella number is not a formula for adequate limits or evidence every underlying policy is included.

Talk through your major airline coverage

Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.

How can we help you get started?

Choose the quote that fits, and we’ll take it from there.

Have a question? Contact us