

Oven and kitchen fire
High-heat ovens, fryers, and accumulated grease and flour dust create significant fire and burn exposure.
Try a different word, or check the spelling.
A product from your counter may also reach customers through wholesale orders. Liability for ingredients and declared allergens needs to follow those sales channels, separately from replacing goods or repairing the oven.
The Southern Agency can help you evaluate your bakery's kitchen and storefront exposures.
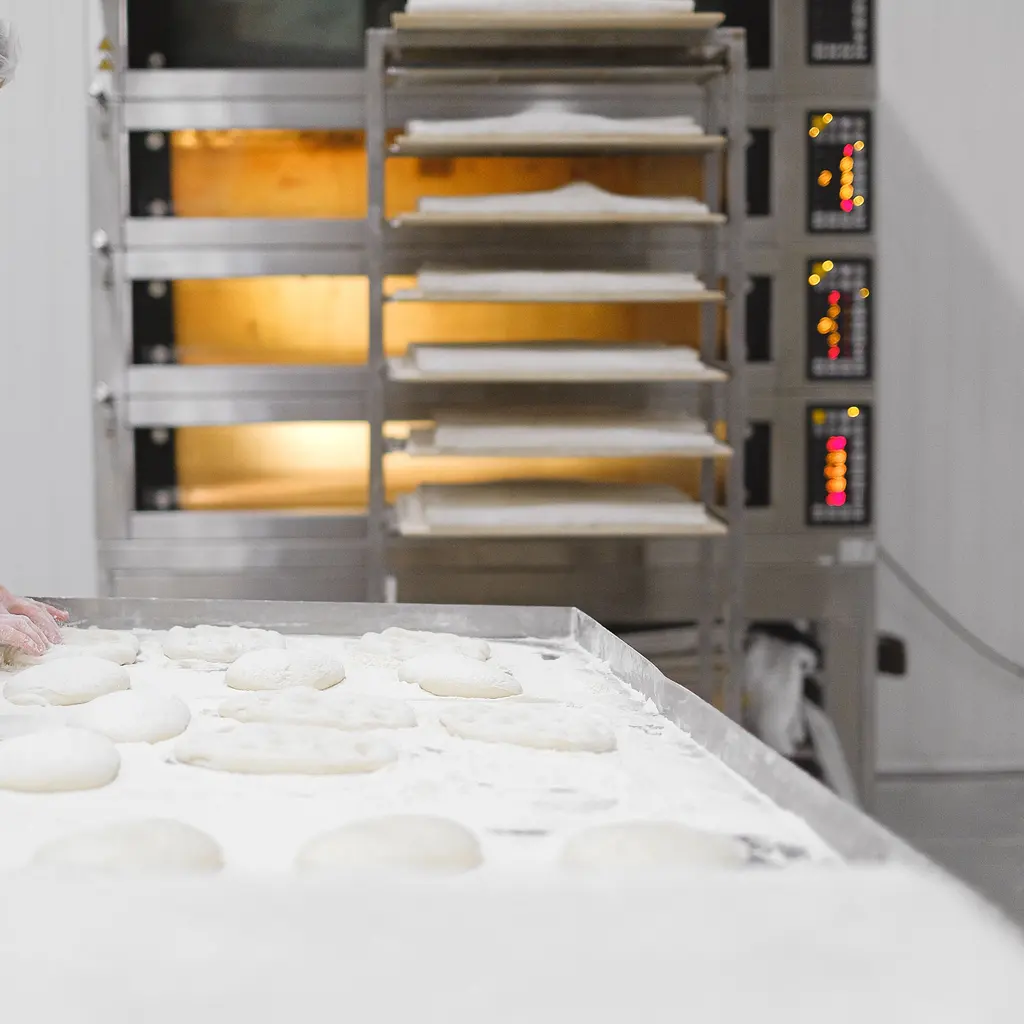
You bake and sell goods, often managing a production kitchen and a customer storefront simultaneously. Allergen-related incidents, oven fires or staff injuries are common risks that can affect your ability to sell daily.
The Southern Agency can review your retail and wholesale baking processes to help select appropriate insurance, such as coverage for allergen-related liability and equipment breakdown for your ovens and cooling systems.
High-heat ovens, fryers, and accumulated grease and flour dust create significant fire and burn exposure.
Undeclared nuts, wheat, dairy or eggs and ingredient cross-contact can lead to allergic-reaction claims across counter, custom-order and wholesale sales.
Improper handling or storage of perishable fillings and dairy can lead to illness claims from customers.
Walk-in retail traffic on floors that may be wet or dusty creates premises liability exposure.
Failure of ovens, mixers, or refrigeration can spoil ingredients and halt production for hours or days.
A power or equipment outage can spoil perishable stock and finished goods quickly.
Workers using ovens, mixers, and slicers face burn, cut, and repetitive-motion injury risk.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A customer has an allergic reaction to a pastry containing nuts that were not clearly disclosed. Product liability coverage may respond, depending on policy terms and the facts of the incident. Products cover may address covered harm; pulling every pastry or refunding unaffected orders needs separate review.
A fire starts at an oven and damages the kitchen and storefront. Commercial property coverage may respond to repairs, depending on policy terms and protective controls. Review covered fire, protective conditions, and restoration/income terms; refunds and every cancelled order are not automatically paid.
A refrigeration failure spoils perishable fillings and finished goods overnight. Equipment breakdown coverage may help with the loss, subject to policy terms and the cause. Check covered breakdown, stock inclusion, utility cause, and limits; ordinary aging or deterioration is different.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Yes. Allergen reactions, contamination, or foreign objects in baked goods can cause injury claims, so product liability is commonly needed, subject to policy terms and underwriting.
Undeclared allergens in baked goods can cause allergic reactions and injury claims. Clear labeling helps, and product liability may respond to reactions, depending on the specific policy and facts.
Equipment breakdown coverage may help with repair and spoiled perishable stock when ovens or refrigeration fail, depending on policy terms and the cause of loss.
A BOP can bundle property and liability for many bakeries, though producers often add product liability, workers' compensation, and other coverages. The right mix depends on operations.
General liability commonly responds to customer slip-and-fall claims on the premises. Coverage depends on policy terms, the facts, and underwriting.
They can, since selling to other businesses widens product distribution and may add contractual requirements. Coverage should be reviewed as wholesale grows, subject to underwriting.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.