

Nut and allergen reactions
Nuts and other allergens run through the product line, so cross-contact or labeling failures can cause severe reactions and claims.
Try a different word, or check the spelling.
Your gift assortment may leave through the front door or a mail-order parcel during the same holiday rush. Product protection needs to fit what you make or resell, with shipping damage and temperature-sensitive stock considered separately.
The Southern Agency can help you align your insurance program with your allergen-heavy product line, production equipment, and seasonal business cycles.
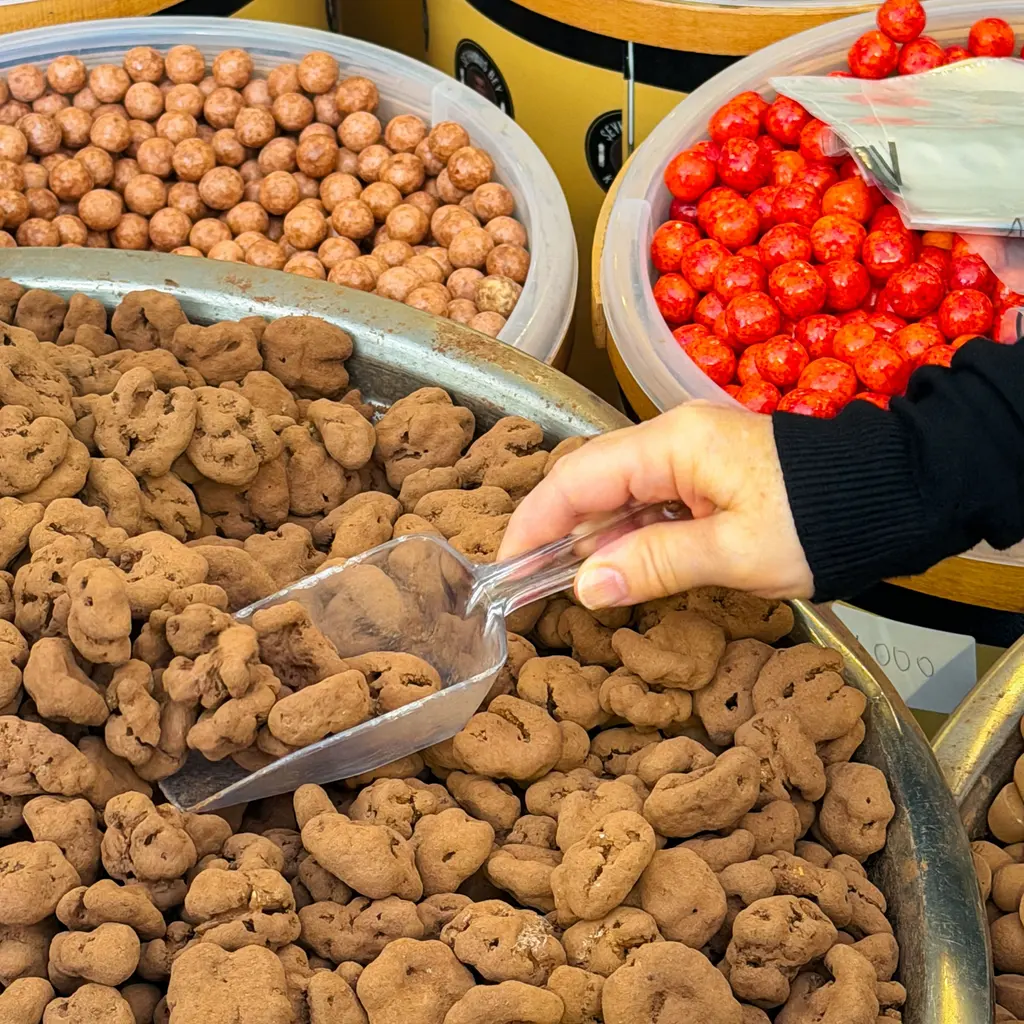
You sell candies, nuts or gift assortments that you may make, repackage or buy in. Allergen communication follows those products; if you cook sugar or roast nuts, heat and equipment add production risks. A cooling failure near a holiday rush can affect stock and the sales window together.
The Southern Agency can help you review your production equipment, retail traffic, and seasonal inventory to select appropriate insurance, such as workers compensation for your production staff or product liability for your assortments.
Nuts and other allergens run through the product line, so cross-contact or labeling failures can cause severe reactions and claims.
Cooking sugar, tempering chocolate, and roasting nuts create burn and fire hazards for staff and the premises.
Holiday spikes pack sales, inventory, and shipping into short windows, magnifying the impact of any disruption.
A walk-in retail counter exposes the shop to slip-and-fall and other customer injury claims.
Failure of cookers, tempering machines, roasters, or refrigeration can halt production and spoil temperature-sensitive stock.
Chocolate and perishable items can be ruined by heat or refrigeration loss, especially in peak seasons.
Mail-order and gift shipping can lead to spoiled, damaged, or mislabeled product reaching customers.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A customer reacts to a candy that contacted nut equipment without clear disclosure. Product liability coverage may respond, depending on policy terms and the facts of the incident. Covered injury differs from withdrawing assortments and refunding orders.
A nut roaster overheats and starts a fire that damages the production area. Commercial property coverage may respond to repairs, depending on policy terms and protective controls. Check fire/protective conditions, equipment values, and restoration terms.
A refrigeration failure spoils chocolate inventory just before the holidays. Equipment breakdown coverage may help with the loss, subject to policy terms and the cause. Check covered cooling event and stock limits; bloom or late gifts alone do not establish cover.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Nuts run throughout the product line, and cross-contact or labeling failures can cause severe reactions. Product liability may respond to such claims, subject to policy terms and underwriting.
Holiday peaks concentrate inventory, sales, and shipping, so limits should reflect peak values. The right approach depends on operations and underwriting.
Equipment breakdown coverage may help with repair and spoiled temperature-sensitive stock when refrigeration or cooking equipment fails, depending on policy terms and the cause.
It can, since shipping perishable and gift product adds spoilage and fulfillment exposure. Coverage should be reviewed as shipping grows, subject to underwriting.
A BOP can bundle property and liability for many shops, but product liability and workers' compensation are often added. The right mix depends on your operations.
General liability commonly responds to customer slip-and-fall and similar claims on the premises. Coverage depends on policy terms, the facts, and underwriting.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.