

Combustible sugar dust explosion
Fine sugar dust generated in drying and handling is highly combustible and can cause devastating explosions and fires without strict controls.
Try a different word, or check the spelling.
Your campaign concentrates a large part of the year's production into a limited window. Machinery repairs and campaign-income protection need to fit that timing, without treating rejected sugar or every missed production day as insured.
The Southern Agency can help you align your property and liability protections with your seasonal production needs.
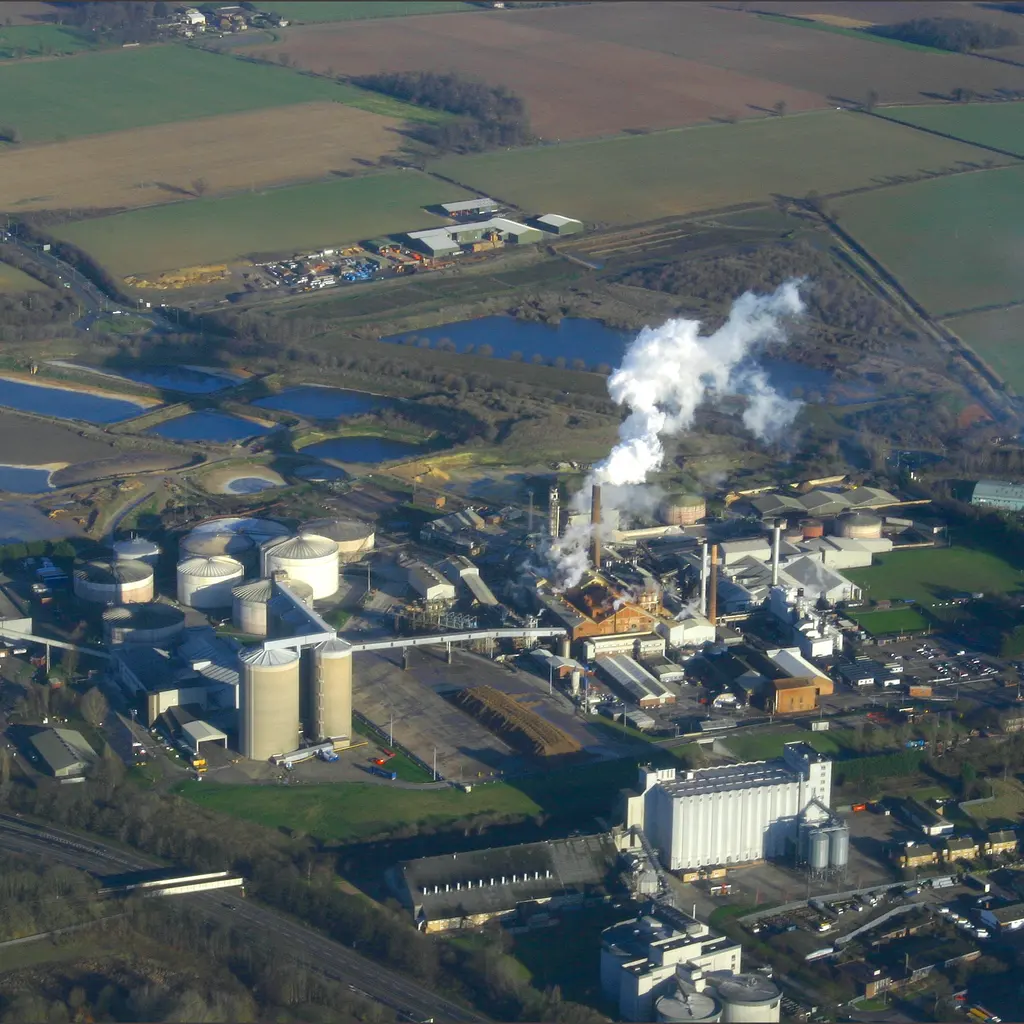
Your facility processes sugar beets into refined sugar through an intensive campaign, utilizing high-pressure boilers and complex machinery. If a boiler fails or combustible dust ignites, your entire production schedule could be stalled during a critical campaign window.
The Southern Agency can review your operational risks, such as your dust control and machinery maintenance, to help you select appropriate insurance. For instance, we can help assess whether your equipment breakdown coverage includes income protection for downtime experienced during peak production months.
Fine sugar dust generated in drying and handling is highly combustible and can cause devastating explosions and fires without strict controls.
High-pressure boilers, evaporators, and centrifuges can fail catastrophically, halting production and causing major property damage.
Concentrated processing seasons mean any downtime during a campaign can disproportionately reduce annual output and revenue.
Lime, chemical processing, wastewater, and air emissions create environmental liability subject to regulatory enforcement.
Refined sugar shipped to food manufacturers carries contamination and recall exposure affecting downstream customers.
Workers operating slicers, conveyors, and processing equipment in hot, dusty conditions face serious injury exposure.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Accumulated sugar dust ignites and causes an explosion and fire in the drying area. Property coverage may respond to damage, depending on policy terms, exclusions, and the facts of the incident. Check covered explosion/fire, protective conditions, and stock values; pollution remediation and every campaign loss are separate questions.
A high-pressure boiler fails at the height of the processing season. Equipment breakdown and business income coverage may help with repairs and lost production, subject to the specific policy and exclusions. Confirm covered equipment event, income inclusion, seasonal values, and restoration/time deductible; missed supply penalties are not automatically insured.
A discharge exceeds permitted limits and triggers a regulatory response and cleanup. Environmental liability coverage may respond to pollution costs, depending on policy terms. Check release/cleanup and permit/noncompliance exclusions; fines or routine compliance improvements are not automatically payable.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Compare property, equipment breakdown, environmental, product liability, workers' compensation, and general liability for the factory's operations. The mix depends on processes and scale, subject to underwriting.
Property coverage may respond to dust-explosion damage, but strong dust controls heavily influence underwriting. Coverage depends on the specific policy, exclusions, and the facts.
Because production is concentrated, downtime during a campaign is especially costly. Business income coverage may help with lost production, depending on policy terms and exclusions.
Often yes. Wastewater, lime, chemicals, and emissions create pollution exposure, so environmental liability is commonly considered, depending on operations and underwriting.
Trace sugar lots into customer ingredient runs; a downstream buyer bill is not automatically covered. Products liability concerns covered harm to others. Withdrawal and first-party contamination/recall costs need a specifically eligible event, products and purchased expenses; ordinary spoilage, rework or a quality rejection is not automatic cover.
Equipment breakdown coverage may help when boilers, evaporators, or centrifuges fail, covering repairs and resulting losses, subject to policy terms and exclusions.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.