

Cash and chips
Robbery, employee theft, and fraud can affect gaming funds.
Try a different word, or check the spelling.
Your security team works with gaming crowds, while the cage handles cash and chips under different controls. Guest liability and crime terms need to distinguish those duties, without assuming every security allegation or gaming obligation is insured.
Identify cash and chip interests, security employers, player-data custody and systems shared by gaming and lodging.
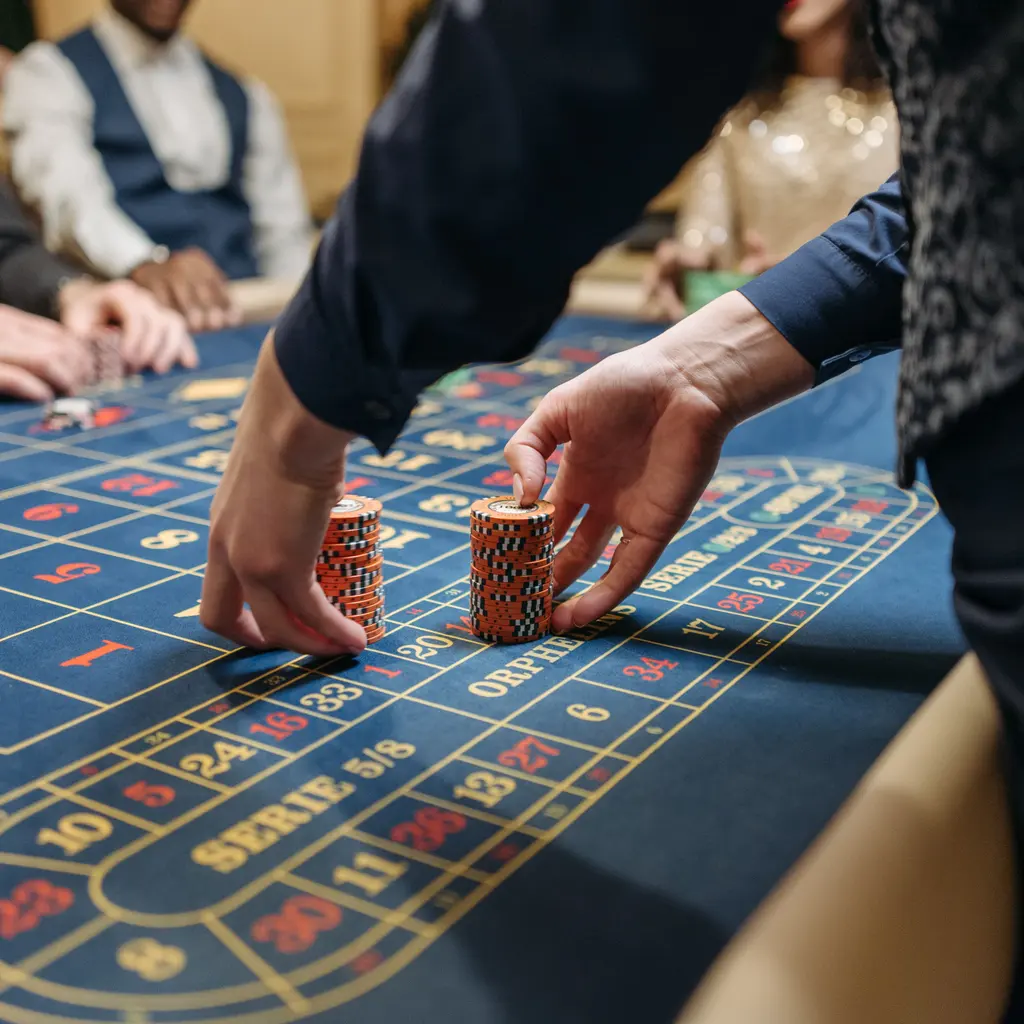
Your casino hotel combines gaming, rooms, food service, and entertainment. Cash moves through cages and payouts while your guest and player systems retain information across several operations.
The Southern Agency can review your crime, privacy, and liability risks to help you select appropriate insurance. We can discuss how to protect your buildings and machinery against a single event that disrupts both lodging and gaming.
Robbery, employee theft, and fraud can affect gaming funds.
Gaming-floor crowds and security incidents can lead to injury allegations.
Membership and payment systems can expose personal information.
Alcohol service and a varied workforce introduce distinct claims.
Fire or system failure can affect rooms, gaming, and kitchens.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Suppose an employee scheme diverts cage funds. Review the covered dishonest act, insured money or chips, loss valuation and discovery or reporting provisions. A cash discrepancy alone does not establish theft, and guest funds or chips are not automatically valued as the venue's currency.
Suppose an intruder accesses player accounts. Cyber terms may address a covered security event and eligible investigation, notification or privacy claims. Identify actual retained information and provider duties; payment assessments, stolen account balances and gaming-regulator obligations need separate grants.
Suppose a guest alleges injury during a gaming-floor security intervention. Identify the actual security employer, conduct alleged and any assault or security exclusions under liability terms. The venue being named does not prove negligence or mean excess limits restore an excluded activity.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Gaming introduces cash and player-data interests beyond ordinary hotel rooms.
Crime covers specified dishonest acts and property, not every unexplained gaming loss.
Cyber may address qualifying incidents; payment assessments depend on express wording.
Continuous alcohol service needs a description of each operator and location.
Income recovery depends on a covered trigger and the insured revenue interests.
Additional limits must be compared with security, assault, and other underlying exclusions.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.