

Outside access
Walkways, pavement, and lighting can contribute to injury allegations.
Try a different word, or check the spelling.
An unavailable room can reflect wear, an internal equipment failure or damage to the building. Your property, breakdown and income terms need to distinguish those causes alongside protection for exterior-access premises.
Review the actual room-access layout, outdoor lighting and staffing, then the causes that could interrupt rentable rooms.
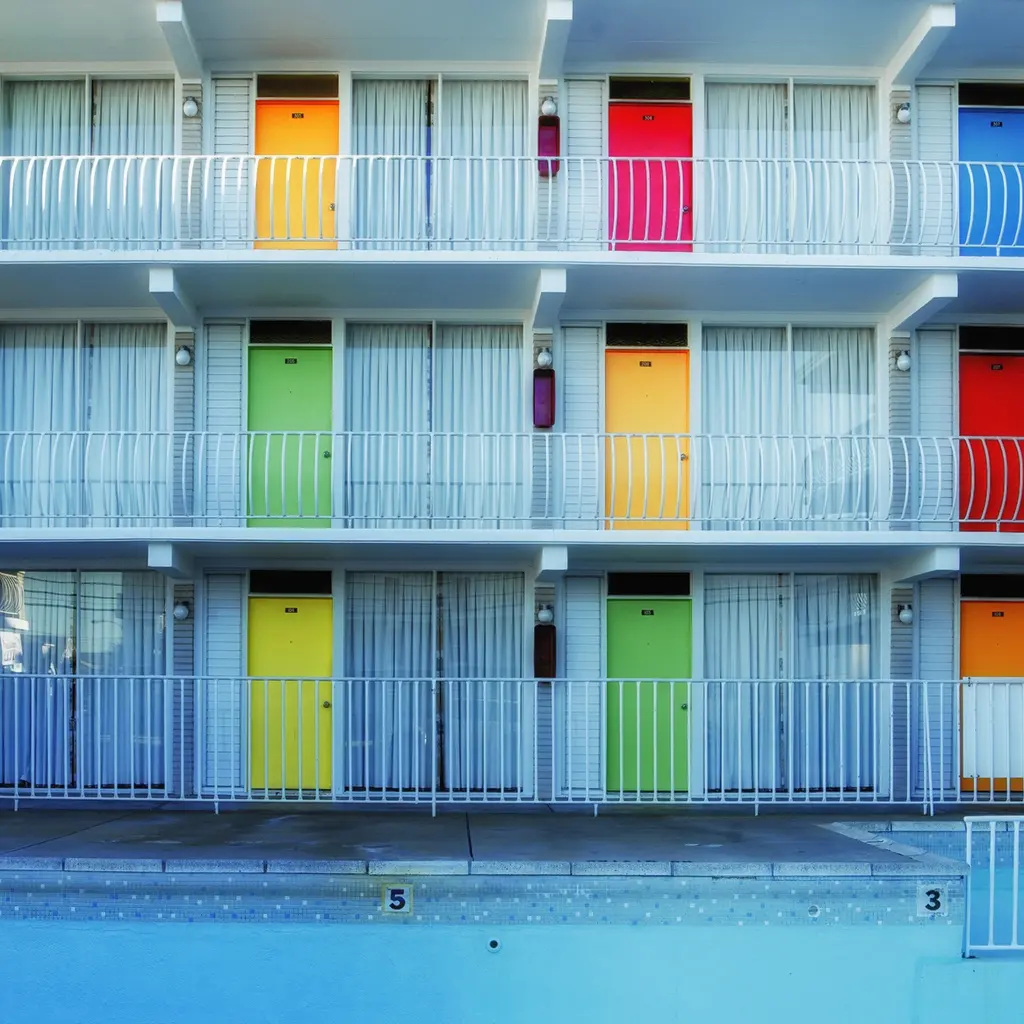
If your motel has exterior-access rooms, guests move between parking, walkways and their doors without a central corridor. Lighting, surface conditions and actual overnight staffing matter when a guest alleges an unsafe route or inadequate security.
The Southern Agency can review your layout, guest access, and maintenance arrangements to help you select insurance. We can discuss premises liability and property protection for exterior-access rooms, alongside any accepted interruption benefits.
Walkways, pavement, and lighting can contribute to injury allegations.
Exterior entry and staffing arrangements may be questioned after an incident.
Roofs, plumbing, and electrical systems can suffer damage.
In-room HVAC or water-heating failure can take rooms offline.
Housekeeping injuries and desk-fund theft involve different cover.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Suppose a guest alleges that poor lighting or a walkway condition caused a fall outside a room. Review the condition, actual maintenance duties and accepted premises activities. A parking-space location does not alone establish fault or include every security or vehicle allegation.
Suppose wind damages several rooms and they close for repairs. Property terms determine eligible damage to insured buildings and contents; purchased income terms address qualifying earnings loss. Check cause, deductible and restoration period rather than treating all unavailable rooms or guest refunds as insured.
Suppose several room HVAC units stop working. Establish whether the cause is an accepted internal breakdown, external damage or maintenance issue before comparing repair and income benefits. Multiple unavailable rooms do not prove covered damage, and ordinary wear is not converted into a claim by adding income limits.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Exterior access and parking deserve emphasis, while actual added amenities still need disclosure.
Liability may address covered injury allegations; parking does not automatically insure every vehicle loss.
Property theft, vandalism, and crime are different provisions with different insured interests.
Income needs a qualifying covered cause and restoration period.
Employee duties and applicable rules determine compensation requirements.
Package availability depends on the actual building and operation; no universal eligibility or price is promised.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.