

Bunks and shared rooms
Ladders and crowded sleeping layouts can lead to injuries.
Try a different word, or check the spelling.
Your reception cash and a traveler's belongings in shared storage are not the same crime-insurance interest. Protection for custody, guest liability and communal facilities needs to fit the arrangements you actually offer.
Describe bunk layouts, self-catering access and locker or storage promises alongside staff and cash-handling duties.
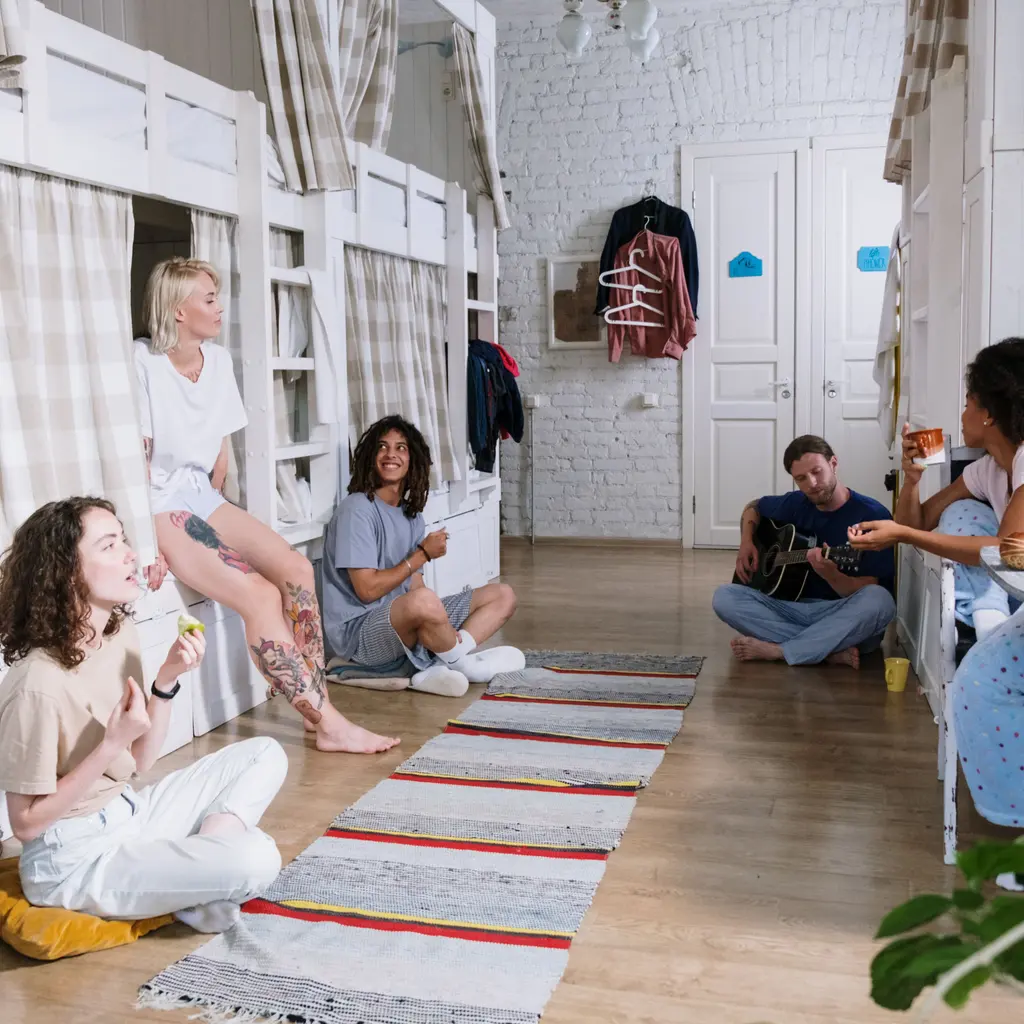
Your hostel hosts unrelated guests in shared sleeping, cooking, and social spaces. The density of dorm living means a bunk bed injury or a claim of missing belongings creates distinct insurance challenges.
The Southern Agency can review your layout and self-service amenities to help you choose appropriate insurance. We can help you distinguish between what the hostel is liable for and what is considered an individual guest's responsibility.
Ladders and crowded sleeping layouts can lead to injuries.
Guest cooking introduces burns and kitchen-fire exposure.
Shared storage can lead to theft complaints and custody disputes.
Showers, stairs, and lounges need premises review.
Desk funds and traveler information create separate crime and cyber interests.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Suppose a guest alleges that a loose bunk ladder caused a fall. Review the actual condition, inspection duties and communal sleeping arrangements accepted under liability terms. The bunk layout and allegation matter; an injury alone does not establish negligence.
Suppose a guest reports a missing bag while reception also discovers missing desk money. Identify each owner, any custody promise and the evidence of theft before comparing grants. Business crime cover for funds does not automatically reimburse guest belongings or an unexplained shortage.
Suppose a pan fire in the shared kitchen damages cabinets and nearby rooms. Property terms may address covered damage to insured interests, subject to actual guest-cooking acceptance. Guest injury, their belongings and purchased income for room closure need separate review.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Shared rooms, guest cooking, and data handling require distinct premises and financial interests.
Guest belongings are not automatically covered by a policy on business cash or furnishings.
Describe self-catering access and actual fire protection when reviewing property.
Crime concerns specified insured money and dishonest acts, not all shared-room losses.
Cyber response follows retained traveler records and processor responsibilities.
Staff size alone does not settle compensation requirements; actual roles and applicable rules matter.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.