

Libel, defamation, and privacy claims
Investigative reporting, opinions, and privacy-sensitive stories can prompt claims.
Try a different word, or check the spelling.
Your reporter's assignment, pressroom and delivery route place people and property in different settings for the same edition. Media, equipment, and fleet protection should follow those roles, with subscriber records and newsroom employment matters considered separately.
Bring actual reporting assignments, owned or contracted printing, carrier arrangements and the reader records your business holds.
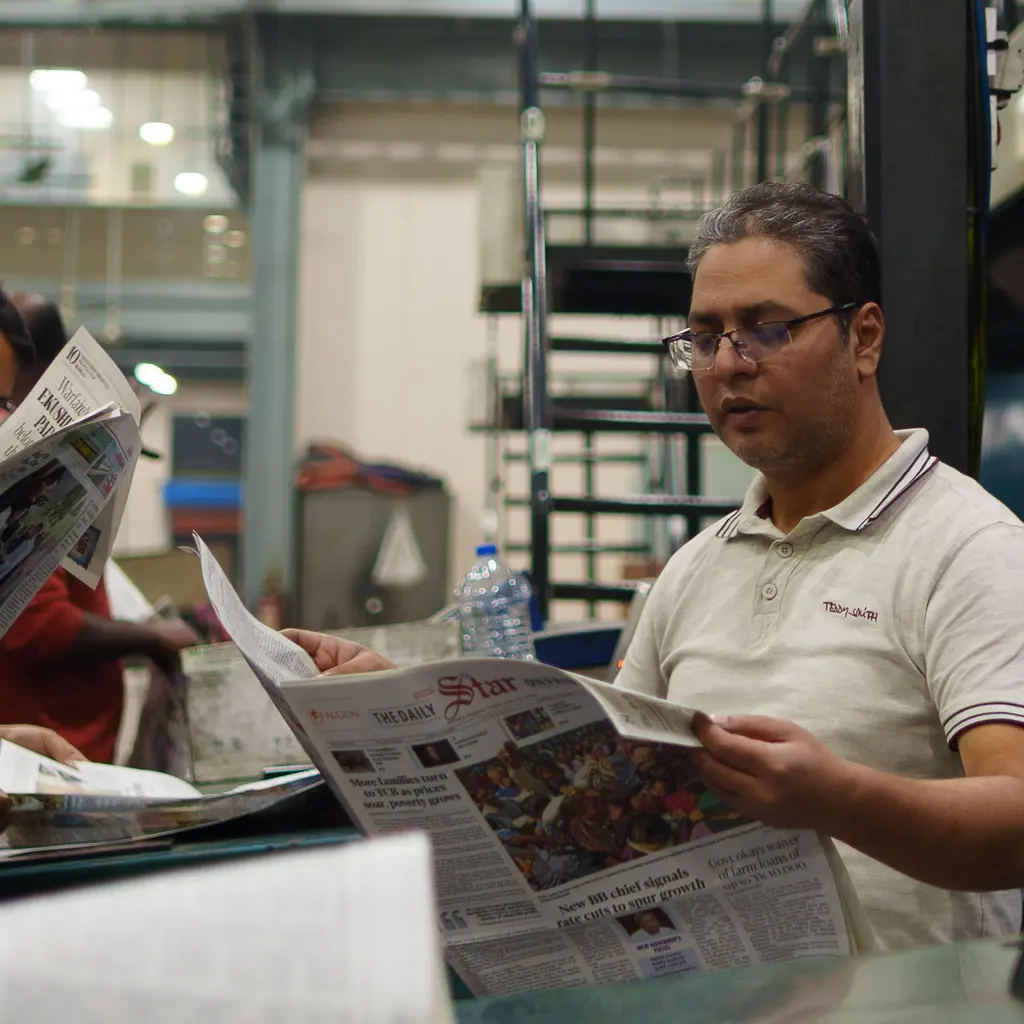
You gather news, coordinate advertisements, and manage tight deadlines for both print and digital publications. A libel claim or a fire in your press room can compromise your reputation and disrupt your distribution.
The Southern Agency can review your news-gathering and printing operations to help you select appropriate insurance. For example, we can discuss how professional liability may help with content-related claims, while equipment breakdown coverage may assist with repairs to your printing presses.
Investigative reporting, opinions, and privacy-sensitive stories can prompt claims.
Delivery vehicles and carrier networks create road and cargo exposure.
A fire or other physical loss can damage presses and production equipment.
Field reporters and photographers work in varied locations and conditions.
Subscriber and advertiser records may be exposed in a breach.
Hiring, management, and newsroom decisions can lead to employment claims.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Suppose a person named in an investigation alleges false statements and sues the publisher. An included publication and reporting role may qualify for defense and covered damages under media terms. Check the alleged content, exclusions and claims-made timing where applicable; a demand does not prove liability.
Suppose a vehicle crashes on a subscriber route. Identify whether it belongs to the newspaper or an independent carrier, then compare accepted use, liability and purchased vehicle-damage terms. Damaged papers and a missed delivery obligation are separate from auto liability or repairing the vehicle.
Suppose a fire damages a press and stops the print edition. Property terms may address covered equipment damage; purchased income depends on its trigger and restoration terms. Continued digital sales, alternative printing and extra production costs need actual facts rather than an assumption that all edition revenue is lost.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Media-liability coverage may defend a covered claim about published reporting and may pay eligible damages if liability is established. Review the publication, content, and policy timing.
Business-auto coverage may address company vehicles used for distribution. Confirm the vehicles, drivers, and use; carrier agreements may allocate other responsibilities.
Commercial-property coverage may pay for covered physical damage to listed presses at insured locations. Equipment-breakdown coverage has a different trigger for machinery failure.
Field assignments can involve changing locations, equipment, and working conditions. Describe the work and check the applicable property, auto, and injury terms.
Subscriber and advertiser data can create cyber exposure. Coverage may help with response costs after an event involving covered systems and data.
Prepare circulation, issue frequency, subject matter, delivery routes, press values, staffing, and subscriber data for an insurer’s review. The insurer decides whether to offer terms.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.