

Editorial content liability
Articles, profiles, and reviews can prompt defamation or privacy claims.
Try a different word, or check the spelling.
Commissioning a photograph does not settle every right to publish it. Review contributor permissions and media liability for the issue you actually release.
The Southern Agency can help you protect your editorial operations with coverage for content claims and mobile equipment.
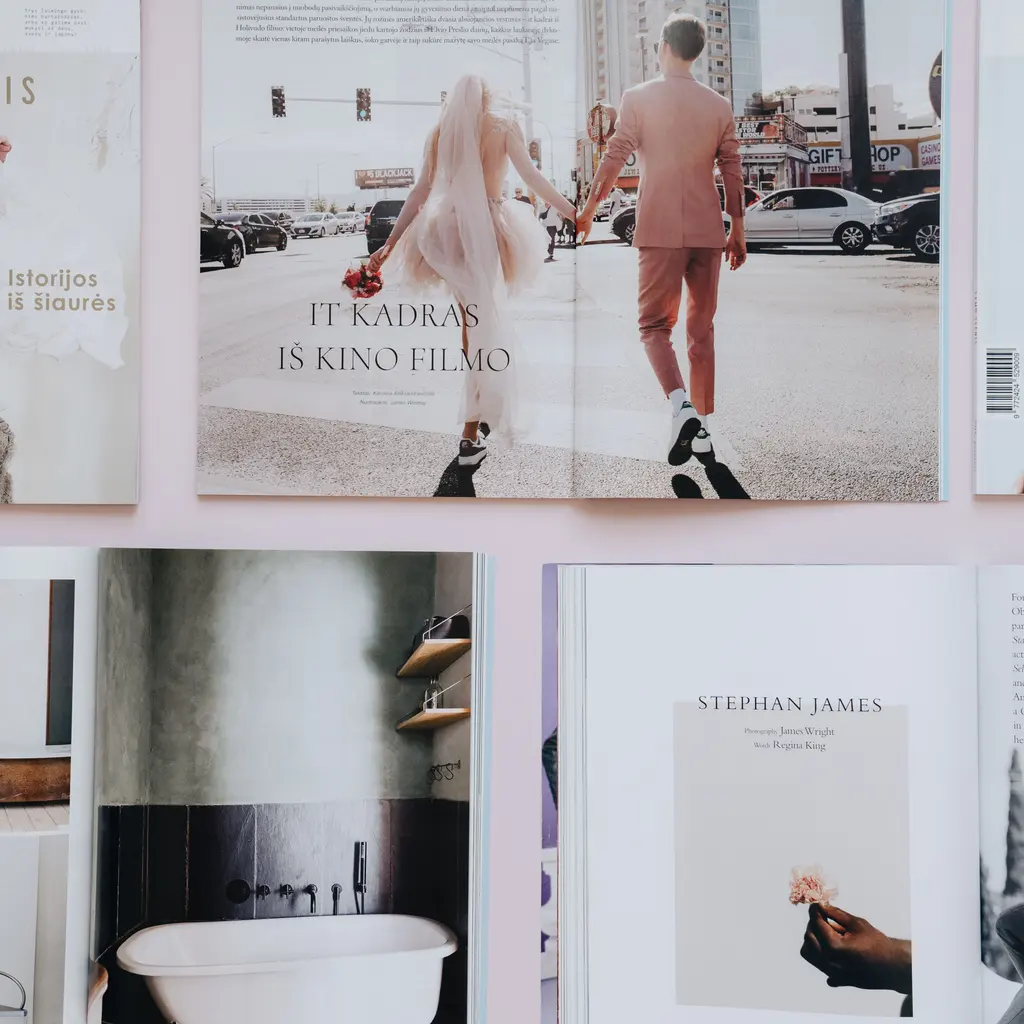
You plan magazine issues, work with writers and photographers, and publish content in print or online. A controversial profile can lead to a legal claim, and the theft of expensive camera gear at a photo shoot can delay your production.
The Southern Agency can help you review your editorial processes and equipment usage to select appropriate insurance. For example, we can discuss how media liability may help with covered content claims and how inland marine insurance can protect your gear used at photo shoots.
Articles, profiles, and reviews can prompt defamation or privacy claims.
An advertiser may dispute a claim or a misprinted promotion.
Using a photograph or article without the right permission can lead to a copyright claim.
Off-site shoots bring crew, equipment, and third-party locations together.
Subscriber and advertiser contact or payment data can be exposed in a breach.
Late issues, dropped ads, or production errors can lead to contract disputes.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A person featured in a profile alleges false and damaging statements and files suit. Media-liability coverage may defend a covered claim and may pay eligible damages if liability is established; the article, rights, and reporting terms matter.
Cameras and lighting are stolen during an off-site photo shoot. Inland-marine coverage may pay for eligible physical loss if the gear, location, travel, and theft terms fit the policy.
Attackers access subscriber payment records, triggering notification work. Cyber coverage may help with approved response costs if the data, systems, and event are covered.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Media-liability coverage may address claims about editorial or advertising content. Check that the form names the magazine, its content, and the relevant rights and services.
Freelancers can raise rights, permissions, and contract questions. Keep contributor agreements and confirm how the policy treats the magazine’s work and the contributor’s role.
Inland-marine coverage may protect cameras and gear at an off-site shoot. Check scheduled items, locations, transit, and theft terms.
Subscriber and advertiser records can create cyber exposure. Coverage may help with approved response costs when the data, system, and event fit the policy.
A misprinted ad can lead to a dispute or refund demand. Professional or media coverage may defend a covered claim; routine correction or refund costs are not automatically paid.
Prepare circulation, issue frequency, subject matter, off-site shoots, subscriber and advertiser data, revenue, and prior claims. An insurer determines whether it will offer terms.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.