

Fundraiser and event injuries
Festivals, dinners, and pancake breakfasts bring the public onto grounds where slips, falls, and crowd incidents can lead to claims.
Try a different word, or check the spelling.
Your club's next project may happen on someone else's property. Review the tools members use and the responsibilities you accept before relying on a clubhouse policy.
The Southern Agency can help you review volunteer projects, fundraisers, and board responsibilities.
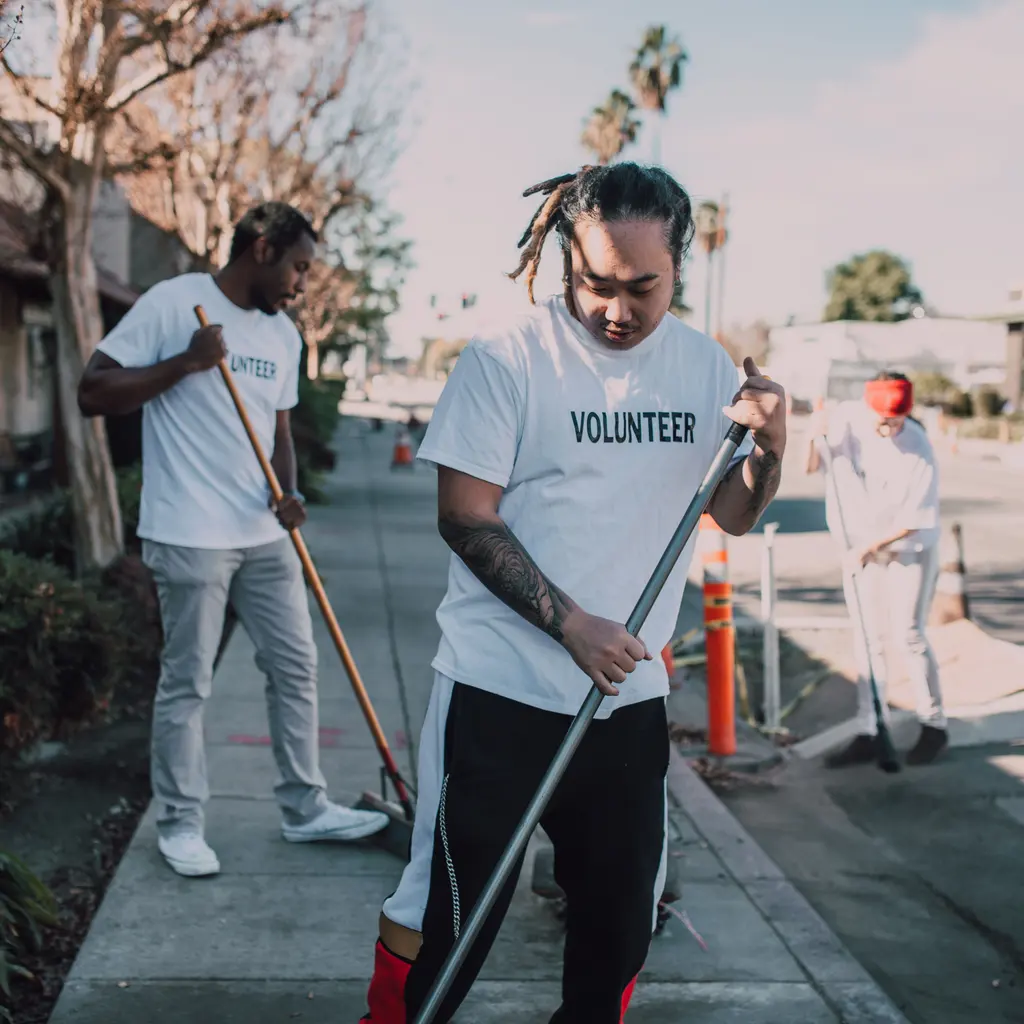
You organize events like festivals and pancake breakfasts that invite the public onto rented grounds, while volunteer projects involve tools and ladders. These activities carry risks of foodborne illness, visitor injury, and potential property damage.
The Southern Agency can review your club's activity calendar and fund-handling procedures to help you select appropriate insurance. For example, we can identify liability coverage for hosted fundraisers or crime insurance for event cash.
Festivals, dinners, and pancake breakfasts bring the public onto grounds where slips, falls, and crowd incidents can lead to claims.
Clubs preparing and serving food at events face foodborne-illness exposure affecting attendees.
Serving alcohol at dinners and festivals can expose the club to liability if an intoxicated guest later causes harm.
Hands-on projects using tools and ladders in the field expose members and third parties to injury.
Sponsoring youth activities and serving vulnerable populations raises abuse-prevention and supervision concerns.
Handling donations, raffle proceeds, and scholarship money creates exposure to theft or misappropriation.
Volunteer directors overseeing spending and scholarships can face mismanagement or breach-of-duty allegations.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
An attendee trips on equipment at a club festival and seeks medical costs. General liability may address a covered claim for an accepted event and insured club or chapter. Identify equipment duties and separate liability damages from medical-payment benefits.
Guests report illness after a club-prepared dinner. Accepted food or product terms may address covered injury claims once the cause and responsibility are established. Testing, spoiled stock, withdrawal and replacement meals are separate expenses, not automatic additions to an injury payment.
Cash is missing after a raffle. Crime may address a covered theft if the funds, handler and evidence fit, subject to discovery and notice terms. Unreconciled receipts alone do not establish theft; count and handoff records help explain what happened.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Hosting public events, serving food, and handling donations all create liability even for small clubs. General liability and related coverages may respond, subject to underwriting.
Describe who sells, supplies and serves alcohol, including any caterer, and bring the venue agreement. Compare accepted host-liquor or separate liquor terms with those duties. An occasional fundraiser does not automatically qualify for host protection or establish the club's legal and licensing obligations.
List the tools, ladders, ramps and property duties involved. Check liability for authorized volunteer acts separately from their own injury benefits, worker status and driving. Membership does not automatically accept every project, insure construction corrections or provide all three protections.
Distinguish sponsorship from custody or supervision, including partner and transport duties. Review accepted entities and people, abuse exclusions, separate limits, defense, prior matters and reporting. Screening or a general liability heading does not establish abuse protection or insure every alleged perpetrator.
Directors and officers coverage helps protect board members against scholarship and spending claims, depending on the specific policy and exclusions.
Bring fund-ownership, count, reconciliation and handler records. Review employee, volunteer and officer definitions, proof, discovery and notice. Theft, transfer fraud and approved deceptive payments have different terms; missing cash or an unexplained shortage alone is not proof of an insured loss.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.