

Training injuries with tools and equipment
Participants learning trades on shop tools and machinery may be injured, creating liability if supervision or safeguards fall short.
Try a different word, or check the spelling.
A trainee's move from your workshop to a host employer can change supervision and work-injury duties. Review both settings without treating every participant as an employee or every placement outcome as a promise.
The Southern Agency can help you consider training activities, participant arrangements, and any placement or clinical services.
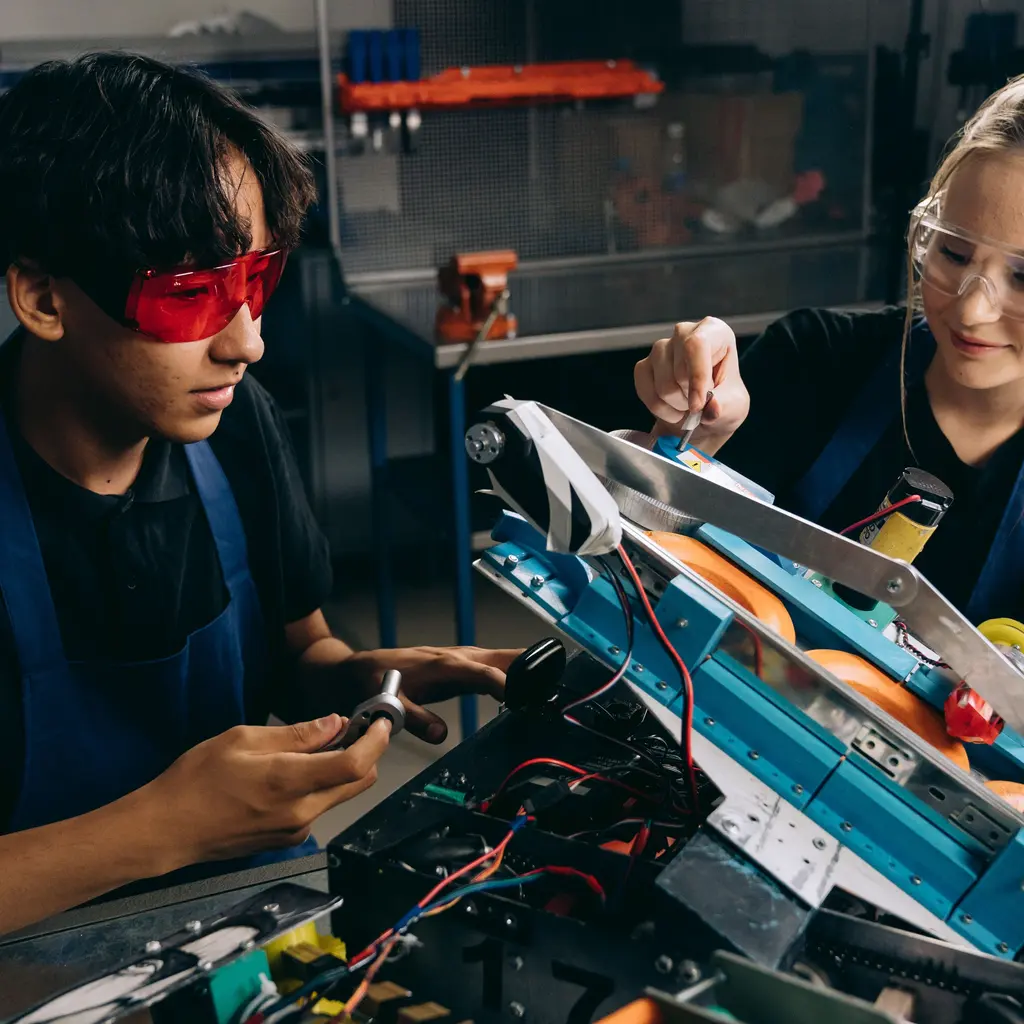
You help clients develop job skills and move into workplaces, which may involve shop tools, machinery or on-site coaching. A training injury or a disputed assessment can raise different questions about supervision, employment and professional advice.
The Southern Agency can review your vocational programs and site-coaching activities to help you select appropriate insurance. For example, we can help align general liability for your workshop with professional liability for placement services.
Participants learning trades on shop tools and machinery may be injured, creating liability if supervision or safeguards fall short.
Training machinery, computers, and shop equipment can be damaged or break down, disrupting programs and creating repair costs.
Assessing clients and placing them into jobs raises professional liability if outcomes or recommendations are alleged to cause harm.
Hands-on work with vulnerable clients creates exposure to neglect, mistreatment, or abuse allegations within the program.
Instructors supervising shop activities and assisting clients face their own injury exposure that drives workers' compensation claims.
Directors overseeing grants, contracts, and program compliance can face claims alleging mismanagement or fiduciary breach.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A participant is injured using a training machine and claims inadequate supervision. Accepted training liability may address covered defense and damages. Identify the machine and trade, participant or worker status and host duties, with professional and abuse exclusions reviewed. Medical benefits need their actual provisions; enrollment alone does not insure every trainee injury.
A training machine suffers an internal failure and classes stop. Equipment breakdown may address included repair costs if the machinery and cause qualify. Income and extra expense need their purchased triggers and restoration terms; routine wear, maintenance and all canceled classes are not automatically covered.
A client alleges a placement recommendation caused financial harm. Professional liability may address covered defense and damages for accepted assessment or placement work. Insured capacity, reporting and loss terms matter. Wages, retraining or refunds need their actual damages provisions; insurance does not guarantee a job.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
General liability addresses training and premises injuries, while professional liability may respond to claims tied to assessment and placement. The right mix depends on services and underwriting.
Review actual covered machinery/internal breakdown and separately purchased repair/income/extra-expense triggers, waiting/restoration, and limits. Wear, maintenance, a failure alone and all canceled classes are not automatically covered or promptly restored.
Identify actual trainee/employee/volunteer status, productive work, machine/trade, and center/host-employer duties. Compare actual accepted participant liability, worker/employer-liability, and accident terms with applicable rules; enrollment and a GL title do not establish every injury benefit.
Yes. Professional liability may respond to claims that placement or counseling guidance caused harm, depending on the facts, the specific policy, and exclusions.
Shop supervision and client assistance can expose instructors to work injuries. Legal requirements depend on actual employment facts and applicable state rules, not an insurer's willingness to offer terms. Describe instructors, contractors and host arrangements, then compare eligible benefits with the compensation policy.
Compare actual grant/venue/program insurance schedules and named entities with proposed forms. A certificate does not amend cover, and insurance does not itself establish licensing, grant compliance, or guaranteed repayment.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.