

Assault, battery, and use of force
Officers who detain or physically engage individuals expose the firm to assault, battery, and excessive-force claims, often a focus of client contracts.
Try a different word, or check the spelling.
A client may blame your patrol for a loss even when no guard used force. Review protection for the duties in your post orders as well as the way officers respond on site.
The Southern Agency can help you coordinate your liability and worker-protection programs for your mobile workforce.
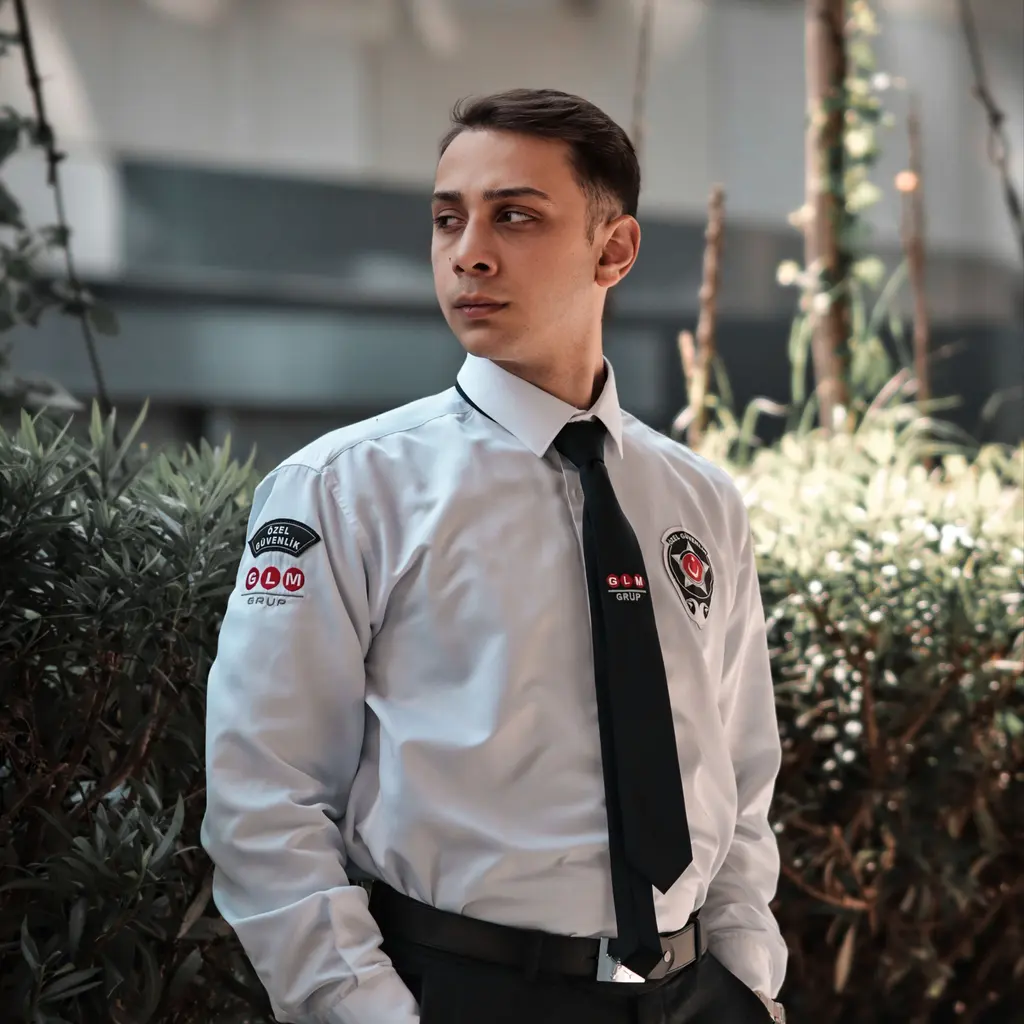
Your service deters theft and controls access by stationing guards and mobile patrols across various locations. Your firm is responsible for employees who interact with the public in unpredictable situations, creating exposure to use-of-force and failure-to-protect allegations.
The Southern Agency can review your deployment model, including patrol routes and guard post responsibilities, to help you select appropriate insurance. For instance, we can help assess how your liability policy addresses the specific conduct of your off-site workforce.
Officers who detain or physically engage individuals expose the firm to assault, battery, and excessive-force claims, often a focus of client contracts.
Detaining a suspected shoplifter or trespasser who is later cleared can lead to false-imprisonment and civil rights allegations.
When theft, vandalism, or injury occurs on a guarded site, clients may allege the officer failed to perform contracted duties.
Marked patrol cars running routes across multiple properties and shifts create ongoing auto liability exposure.
Guards face assault, falls, and overexertion while working at client sites, generating workers' compensation claims.
A high-turnover workforce with access to client property heightens exposure when screening or oversight falls short.
Client agreements frequently mandate specific limits, additional-insured status, and waivers that the firm must continuously satisfy.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A customer detained on suspicion of theft is cleared and alleges false arrest. Review liability coverage for the officer and retail assignment, including false arrest, force, assault and reporting terms. Detention authority requires separate legal review; the customer's clearance does not by itself establish coverage.
A warehouse client suffers a break-in and alleges your officer missed contracted rounds. Security professional liability may address a covered negligent-service claim if the assignment is included. Review contract and property-damage exclusions; replacing stolen inventory or refunding patrol fees is not automatic.
A guard is injured while intervening in a confrontation at a client property. Workers' compensation may provide medical and wage benefits for a qualifying work injury. Review the guard's employer, duties and applicable state rules, especially for contractors or off-duty officers.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Not automatically. Check assault and battery, firearms, reasonable force, detention and security-services wording for the assignments and people involved. Also ask how negligent hiring or supervision allegations are treated. Listing guard work on an application does not by itself change an exclusion.
It refers to professional liability that may respond when a client alleges officers did not perform contracted protective duties and a loss occurred, subject to policy terms.
Armed duties need explicit review under the liability and excess policies, including firearms and assault exclusions. Describe who carries weapons, on which assignments, and your training and supervision practices. Licensing and legal authority remain separate from insurance coverage.
Marked patrol cars are commonly insured under business auto, which may respond to accidents during routes. Coverage depends on policy terms and proper vehicle scheduling.
Bring actual post orders, indemnity, additional-insured, primary/excess, and waiver clauses. Compare actual accepted operations and endorsements; client demands and certificates do not themselves establish compliance or available insurance.
A large hourly workforce raises wrongful-termination and discrimination exposure, which employment practices liability may help address, depending on the policy and the facts.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.