

Prescription dispensing errors
Filling the wrong drug, dose, or missing an interaction can seriously harm a patient and lead to professional liability claims against the pharmacy.
Try a different word, or check the spelling.
Repairing a vaccine refrigerator does not replace the medicines that depended on its temperature. Stock spoilage needs its own accepted causes, medication values and limits, not simply a repair benefit for the machine.
The Southern Agency can help you review pharmacy services, retail duties and temperature-sensitive stock.
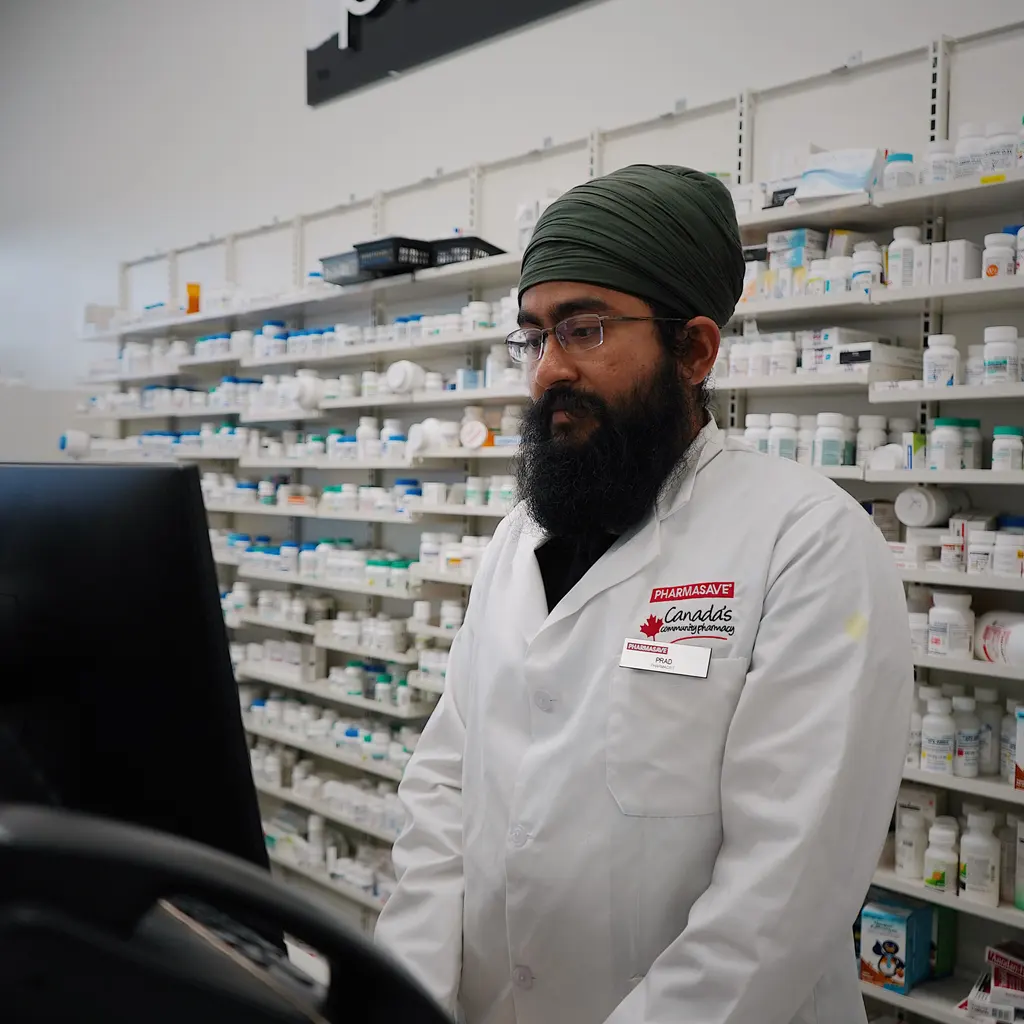
You combine prescription dispensing with a front-store retail business, and may offer vaccinations or other clinical services. A dispensing mistake, spoiled refrigerated medicine or customer injury can involve different people, duties and insured interests.
The Southern Agency can review your pharmacy services and retail operations to help compare appropriate insurance. We can separate accepted dispensing and clinical liability from front-store claims, with refrigeration repair and damaged-medication terms considered on their own.
Filling the wrong drug, dose, or missing an interaction can seriously harm a patient and lead to professional liability claims against the pharmacy.
Compromised patient/prescription information and payment records can create response costs and privacy claims. The actual information, operator, and provider access matter; health-privacy and processor/PCI obligations need their own review.
Narcotics and high-value medications attract burglary, robbery, and internal diversion, with regulatory consequences for lapses.
Administering immunizations and basic clinical services adds bodily-injury and professional exposure beyond simple dispensing.
Vaccines and temperature-sensitive drugs can spoil if refrigeration fails, causing inventory loss and supply disruption.
Aisles invite slip-and-fall claims, and resold over-the-counter and consumer goods can be alleged to be defective.
Cash registers and desirable medications make the store a target for robbery and create employee-theft exposure.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Suppose a patient receives the wrong prescription, suffers harm, and brings a claim. Professional liability may help with covered defense and injury damages for insured dispensing services. Check the business and people insured, the service definition, claim/reporting triggers, exclusions, and limits. Any separate license-defense benefit is not the same as payment of the patient's claim.
Suppose attackers access patient health and payment records. Purchased cyber response terms may help pay covered forensic and required notification costs, with privacy defense/damages if a covered claim follows. Insured entities, actual data, reporting, approved response providers, retention, and limits matter; processor assessments and regulatory penalties require separate wording.
Suppose a refrigerator fails overnight and stored vaccines spoil. If the cause is an insured equipment event and purchased stock terms accept those vaccines, coverage may help with covered repairs and damaged inventory at the written valuation. Review separate limits, deductibles, and any purchased utility/service-interruption or income benefits.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Start with actual dispensing/clinical services and providers, front-store goods, medication values, data, and premises. Compare professional, product/premises, property, crime, equipment, and cyber terms to that map, with state/workforce needs reviewed separately. No single label or standard list confirms every business, service, or loss is covered.
It may help with covered defense and damages where an insured dispensing or counseling service is alleged to have harmed a patient. Check the pharmacy business and individuals, accepted procedures, claim/reporting triggers, limits, and exclusions. Do not assume vaccinations or other clinical work are included solely because a pharmacist is insured; practice authority and license-defense benefits also need separate review.
Insurance does not prevent a breach or replace privacy/security duties. Cyber terms may help with defined response costs and covered privacy claims after an insured event. Identify operators, actual data and provider access; review reporting, response requirements, retention and limits. HIPAA/regulatory proceedings, PCI assessments and processor demands need specific wording and any applicable legal limits.
Confirm the actual medications are insured property under the relevant property theft or purchased employee-theft/robbery terms, and distinguish them from cash. Ownership, valuation, locations, loss facts, documentation, limits, and security conditions matter. Unexplained shortages or diversion are not automatically the same insured event; regulatory responsibilities remain separate.
Investigate the cause and compare insured machines and purchased perishable-stock terms, including actual medication/vaccine acceptance, values, limits, and deductibles. Utility/service interruption and income may have separate triggers or limits. A failed refrigerator alone does not establish a covered breakdown, and wear or maintenance issues can differ from a resulting insured event.
A retailer can face a claim alleging a resold OTC or consumer product caused injury or property damage even when another company made it. Applicable product terms, sometimes part of general liability, may help with covered defense and damages. Identify actual imports/private-label goods and keep product harm distinct from dispensing/clinical services, refunds, replacement, and recall costs.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.