

Dispensing and counseling
Wrong medication, instructions, or interaction advice can allegedly cause harm. Additional services need disclosure rather than assumed inclusion.
Try a different word, or check the spelling.
Your counseling or additional patient service can involve different duties from dispensing the prescribed medicine. Pharmacy-specific professional protection should fit the actual staff and services, with diversion, unexplained shortages and temperature loss distinguished from ordinary retail stock or premises claims.
The Southern Agency can compare your pharmacy's staff and services with professional terms, alongside medication values, refrigeration and patient-record risks.
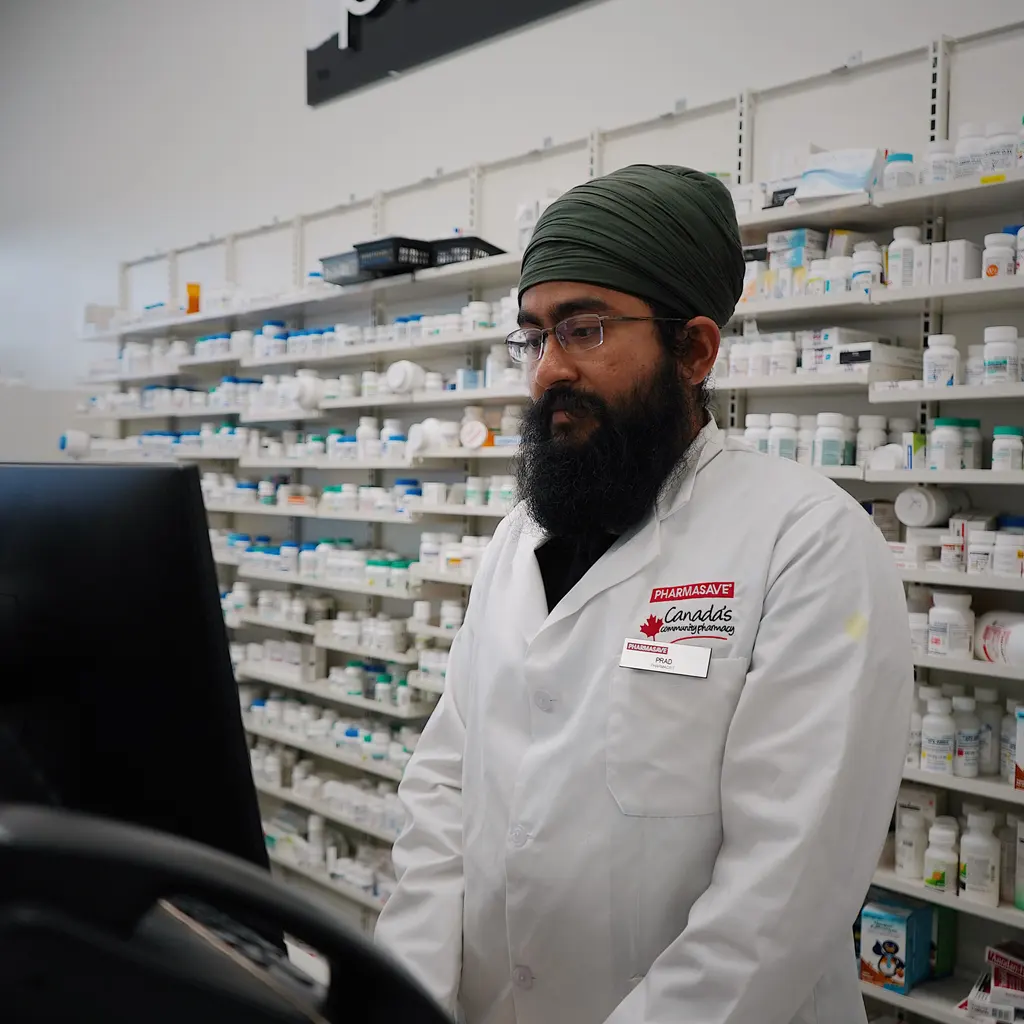
You fill prescriptions, counsel patients and sell retail products, often maintaining refrigerated medicine stock. A dispensing error or a refrigeration failure can result in patient claims and the loss of sensitive inventory.
The Southern Agency can review your dispensing duties, patient records and medication storage to help compare insurance. We can look at accepted pharmacy services and staff, then separate a patient's claim from the terms for stolen drugs, refrigeration repair or spoiled stock.
Wrong medication, instructions, or interaction advice can allegedly cause harm. Additional services need disclosure rather than assumed inclusion.
Robbery and employee diversion differ from unexplained shortages. Refrigerated products also depend on temperature control and documented loss causes.
Prescription and payment systems create privacy exposure. Employee injuries and customer falls involve different interests.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A patient alleges the pharmacy supplied the wrong drug and caused an injury. Accepted pharmacy professional terms may help with covered defense and damages if the dispensing service, business and staff fit. Review applicable claim and reporting dates and exclusions; the allegation is not proof of an error, and a retail premises policy is not a substitute for that review.
A robbery removes drugs and cash. Property and selected crime terms may address different insured interests; limits, security conditions, and inventory proof still apply.
An insured compressor failure affects temperature-sensitive medication. Breakdown and included spoilage cover may address eligible costs; routine expiry or unexplained temperature loss is not automatically covered.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
No. A customer fall and an allegation about dispensing or counseling involve different duties, even at the same counter. Compare accepted pharmacy services, insured staff and professional exclusions; a GL heading does not establish protection for patient-care claims.
No. Repairing an insured refrigeration breakdown and replacing spoiled medication need their respective terms. Compare the cause, accepted stock, temperature and monitoring conditions, valuation and limits. Routine expiry or an unexplained temperature reading does not itself establish a covered loss.
No. Evidence and the purchased theft agreement matter; inventory discrepancy alone may be insufficient.
It may help with covered investigation, response and privacy claims involving accepted records and systems. Follow the policy's reporting and response arrangements. Any regulatory defense, fine or penalty needs its specific terms and applicable law; insurance does not certify privacy compliance or guarantee payment of those amounts.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.