

Breakage of fragile merchandise
Glassware, ceramics, and ornaments are easily damaged by handling, display mishaps, fire, or water, eroding sellable inventory.
Try a different word, or check the spelling.
You choose fragile pieces for customers to pick up, compare and give as gifts. Store protection should distinguish accidental breakage from covered stock loss and browsing injuries, with the holiday inventory and cash peak reflected rather than a quiet-month value.
The Southern Agency can review your fragile goods, holiday stock peaks and customer-facing displays against the property and liability terms offered.
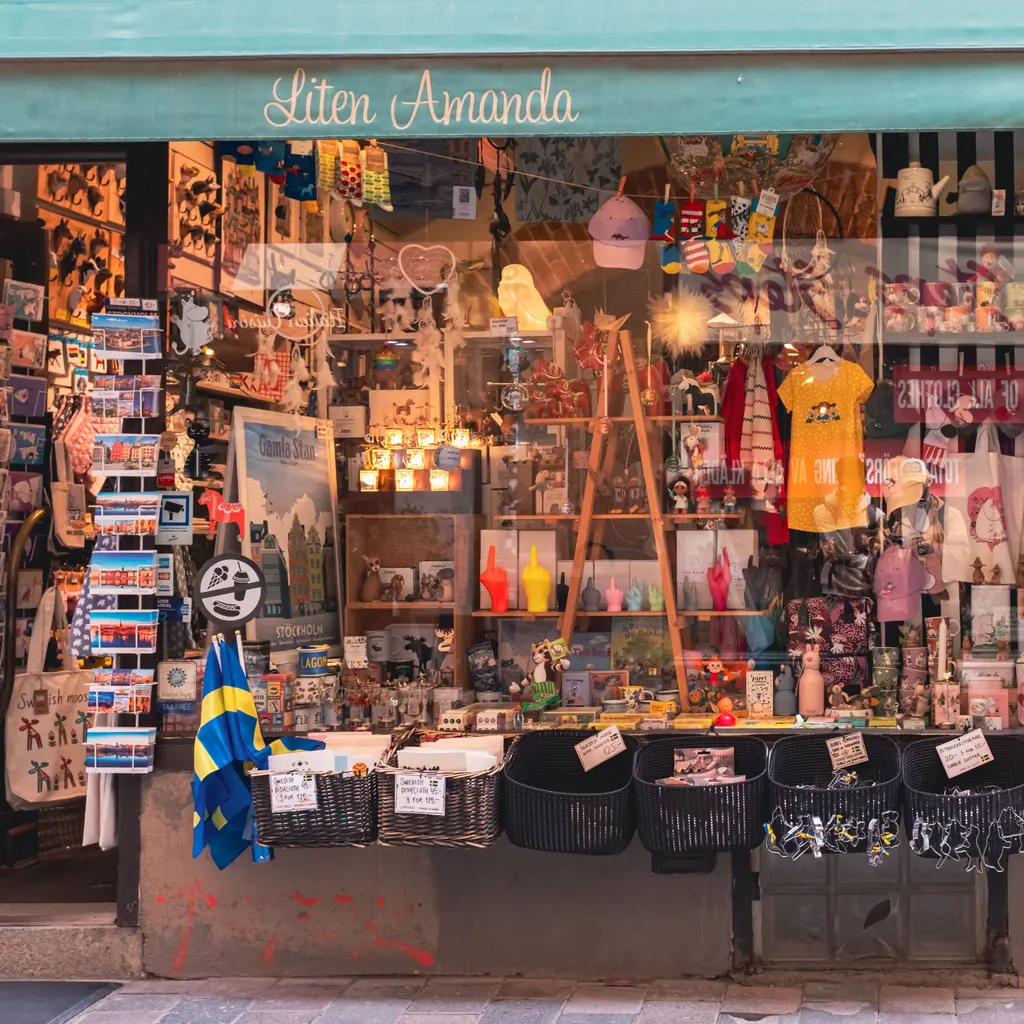
Your gift and novelty shop manages fluctuating stock levels, especially before holidays. A burst pipe could damage your display of ornaments, while a display collapse could leave a customer injured in your aisles.
The Southern Agency can review your specific inventory and store layout to help select appropriate insurance. For example, we can compare coverage for fragile ceramic stock versus liability for browsing customers.
Glassware, ceramics, and ornaments are easily damaged by handling, display mishaps, fire, or water, eroding sellable inventory.
Stock can multiply around holidays, so property limits set for a quiet month may fall short during peak gift-giving periods.
Tight aisles and crowded displays create trip, fall, and falling-merchandise exposure for browsing customers and children.
Small novelty items can be concealed and removed without payment, reducing inventory available for sale.
Holiday stock and receipts can concentrate more value at the premises. A break-in can remove merchandise and cash, so actual peak amounts and loss records matter.
Candles, toys, and novelty items sold to customers can cause harm and prompt product liability claims.
Card transactions at the counter create breach and privacy liability if point-of-sale systems are compromised.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Suppose a crowded display tips and injures a browsing customer, leading to a claim against the shop. General liability may help with covered defense and injury damages, depending on the cause, allegations, exclusions, and limits. Medical payments are a separate benefit; injury alone does not establish fault or payment.
Suppose thieves break in during the holidays and take stock. Applicable property theft coverage may help replace insured merchandise at the written valuation, subject to actual peak limits, proof, deductibles, and any security conditions. Compare any applicable crime clause separately for its own insured interests and proof. Do not assume two policy labels provide duplicate recovery for the same stolen stock.
Suppose a leak soaks shelves of cards and decor. Commercial property may help replace insured damaged stock if the actual water cause qualifies, using written valuation, limits, and deductibles. Purchased business income requires its qualifying interruption and loss/time provisions; wet merchandise alone does not establish a closure or every lost sale.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
A holiday stock peak can exceed limits based on a quiet month. Bring values and peak dates, then compare the offered valuation, limits, and any actual seasonal-increase conditions with that inventory. An increase must be provided by the policy and its conditions met; a seasonal retail description does not create unlimited stock protection.
Commercial property may help when breakage follows a covered cause. Some forms restrict broken statuary, chinaware or porcelain but include exceptions for glass and containers of goods held for sale. Compare the actual items, cause, form/endorsements, valuation, and deductible; neither fragile stock nor handling/display breakage has one universal coverage answer.
Keep inventory and incident records, and compare actual property theft terms with any applicable crime clauses. Merchandise shoplifting, burglary, cash robbery, employee theft, and unexplained shortage are different losses. Review insured interests, proof, locations, limits, deductibles and any security conditions rather than treating crime coverage or controls as automatic payment.
Applicable product terms, sometimes within general liability, may help defend a covered injury/property claim and pay covered damages. Describe actual candles, toys or other goods, warnings, and import/private-label roles, even when another company made them. Replacing faulty stock, refunds and recalls are different costs; compliance or a supplier's insurance does not decide every claim.
A BOP can combine eligible property and general liability with income benefits as provided by the offered package. Confirm actual products, stock values/peaks, premises, and channels are accepted, then compare fragile-article, theft, seasonal and income terms. Small size alone does not establish fit or replace separate data, vehicle or workforce review.
Identify actual payment, customer, and online-order information held by the shop and its providers. Cyber terms may help with defined response costs and covered privacy claims after an insured event, subject to reporting, response-provider approval, retention, and limits. Processing through a vendor does not settle every duty, and processor/PCI demands require specific terms.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.