

Stop-and-go vehicle movement
Backing, curbside stops, and loading access can lead to injury or property damage. Vehicle and unloading definitions affect the applicable liability policy.
Try a different word, or check the spelling.
Your liftgate, loose dolly and the freight it moves can need different property terms at the same stop. Local-delivery protection should fit those handling stages and vehicle boundaries, with driver or owner-operator duties and missed-window demands reviewed separately from physical cargo damage.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
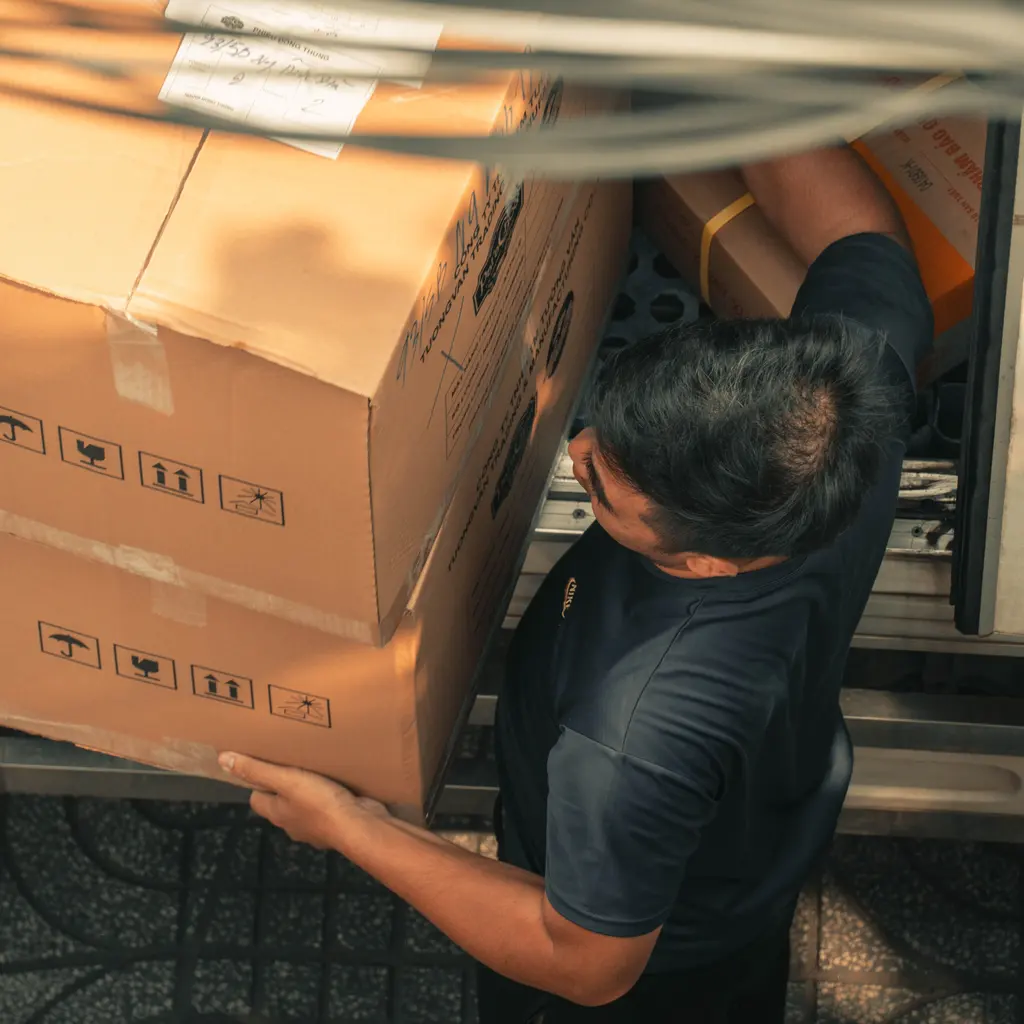
You perform short-haul deliveries, making frequent stops at docks and homes where maneuvering in tight spaces or lifting heavy freight can result in property damage or worker injuries. Effectively managing these varied stops is key to your operational success.
The Southern Agency can review your local routes, vehicle fleet, and loading procedures to help you choose insurance. For example, we can help determine how your cargo coverage applies to the different handling stages between your warehouse and the customer's door.
Backing, curbside stops, and loading access can lead to injury or property damage. Vehicle and unloading definitions affect the applicable liability policy.
Goods can shift, be stolen, or suffer handling damage. Vehicle physical damage does not insure freight automatically.
Drivers face lifting and liftgate injuries. Missed delivery windows and shipper refunds are different from insured physical damage.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A driver damages a customer's door while backing. Auto may address a covered third-party claim; damage to the truck itself requires applicable physical damage terms.
A pallet shifts and goods are damaged. Cargo may address an insured loss if handling, commodity, and securement terms fit; delay penalties are separate.
An employee is hurt unloading a parcel. Workers compensation may provide eligible benefits; a contractor's status cannot be assumed from the job title.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Do not assume it. Disclose the actual delivery use and inspect exclusions and endorsements.
Not automatically. Cargo cover must include the goods, interest, and stage.
No. Liability insured status and cargo/property interests are different.
No universal exemption should be inferred. Vehicle, goods, routes, and jurisdiction need qualified review.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.