

Hail and weather damage to lot inventory
A storm can damage multiple units at one location. Establish peak values and single-event limits, and read hail, wind, and flood separately; the word weather does not establish every peril included.
Try a different word, or check the spelling.
A unit can change owners or risk responsibilities as it moves from a staging lot onto a transporter and into a dealer's hands. Your vehicle-stock protection needs those handoffs and peak values, separately from road liability, floorplan duties, and the price expected on resale.
The Southern Agency can help you protect your vehicle inventory and manage the liability risks of your distribution network.
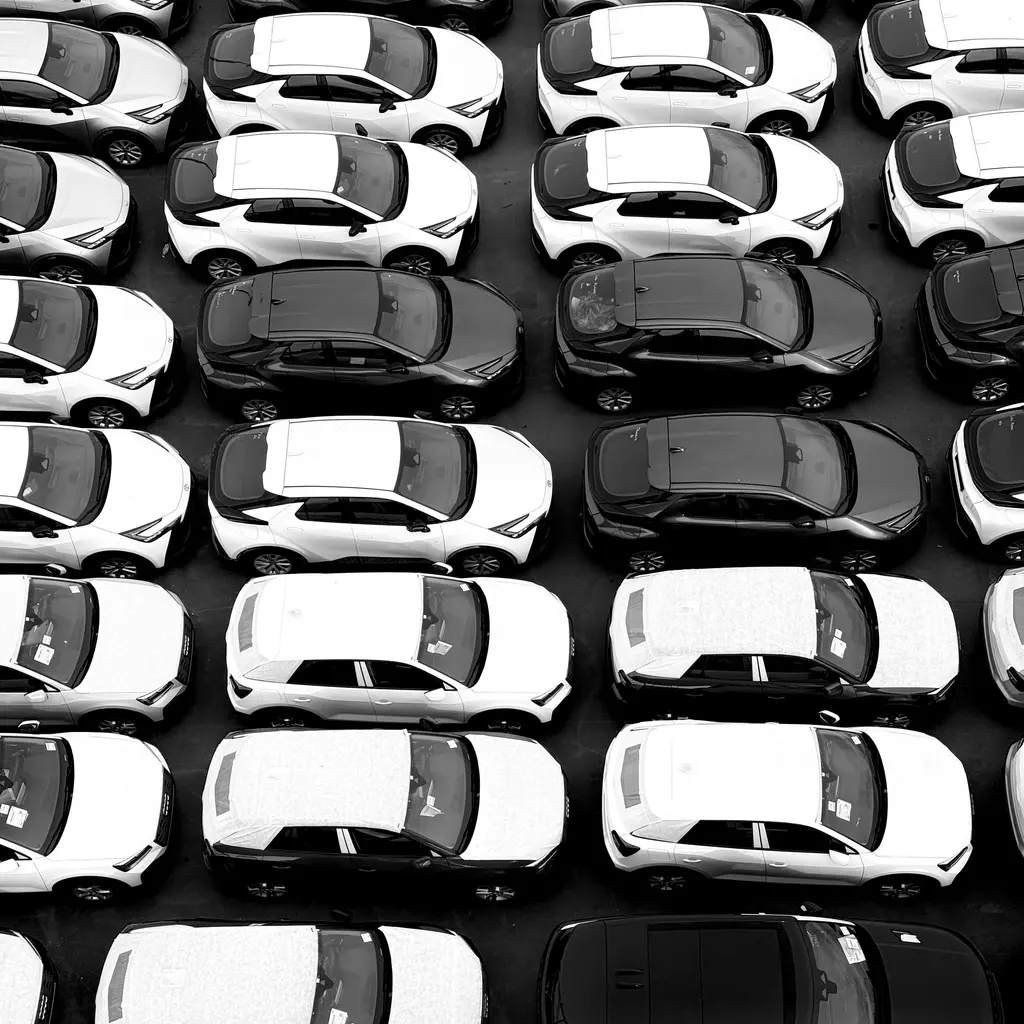
You transport vehicles from manufacturers to dealers, often holding them in staging lots or managing their transit. An accident during delivery or severe weather damaging your inventory can create substantial financial risk.
The Southern Agency can review your vehicle handling and delivery duties to help you select appropriate insurance, such as physical damage coverage for your inventory or liability for road operations, while clarifying how your specific loading and storage methods determine your protection needs.
A storm can damage multiple units at one location. Establish peak values and single-event limits, and read hail, wind, and flood separately; the word weather does not establish every peril included.
Whole-unit theft, stripped parts, and vandalism can involve different damage and proof. Bring inventory and key-control records, actual yard security, and any vehicle-stock theft conditions.
Scratches, dents or collision damage can arise on ramps, aboard transporters or while units are driven. Record condition at handoffs and identify the owner, risk transfer, and loading or unloading stage.
A driver moving a unit can injure someone or damage other property. Compare the driver, vehicle, ownership, and use with covered-auto designations; liability to others is different from repairing that unit.
Allocation, delivery and floorplan terms can assign damage, loss-payee and settlement duties. A disagreement over delivery, credit or resale price is not itself proof of an insured physical loss or liability claim.
Moving, fueling, prepping, and loading vehicles can cause strains, slips, and struck-by injuries. Describe actual duties, employers, contractors and work states rather than place every lot worker in one class.
A fuel, battery-material or fluid release can lead to contamination, cleanup demands and third-party claims. Identify the substance, site, and activity; routine handling, a permit obligation, and an insured pollution condition are different questions.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
Ready to compare options?
Get a quote for Automobile and Motor Vehicle Distributor Or call 1-800-777-1TSAThese hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A severe storm dents dozens of vehicles parked in the marshaling yard. Included vehicle-stock protection may help pay eligible repair under its valuation terms. Compare peak values, the event limit, and hail deductible. Flood is a separate peril, and repair of dents does not promise the full sale price or compensation for every reduction in resale value.
Vehicles are damaged in a carrier collision during dealer delivery. Direct transit protection may help pay eligible unit damage if the distributor's interest, route, and stage are included. Compare that grant with any claim against the hauler under its liability terms. Contractual risk transfer alone does not establish either payment or reimbursement of dealer delay penalties.
Several units are stolen after hours. Included vehicle-stock theft terms may help reimburse eligible vehicle loss. Inventory records, insured interests, valuation, security conditions, and notice determine the claim review; a stock count alone does not prove the cause or the amount payable.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Establish how the actual vehicles held for sale are included under vehicle-stock, open-lot or other inventory terms. Compare ownership and finance interests, locations, valuation, reporting, and peak/event limits. A building contents limit or auto liability schedule alone does not establish hail, theft, flood or collision protection for those units.
Auto liability may help with covered claims when the vehicle, driver, and use are included. Check owned, hired and non-owned designations and actual yard or road movements. Repair of the driven unit needs its own physical-damage or stock grant; an owned unit is not proof both parts are insured.
Direct vehicle-stock or transit terms may help pay eligible unit damage on included legs and handling stages. Compare insured interests, values, pack, or securement duties and handoffs. A claim under the carrier's cargo liability depends on its responsibility and terms, not simply the distributor's sale contract or the fact the transporter has auto insurance.
Many units can be affected by one storm at one yard. Read the actual hail limit, deductible, and event definition alongside peak values and temporary locations. Wind and flood have their own terms; a weather description does not make them the same insured cause or promise every reduction in resale price.
Identify fuels, battery types, fluids, prep or service activities and the locations where a release could occur. If included, pollution terms may help with eligible cleanup and third-party claims. Compare prior conditions, consent, notice and transport scope; routine handling, compliance work and fines are not established by the premises grant.
An actual manufacturer or dealer agreement may set required limits, indemnities, or insured-status terms. Bring the complete requirements and compare them with issued policies and available options before accepting the obligation. The agreement does not force an insurer to provide matching terms or insure every contractual payment.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.