

Delicate equipment and custody
Imaging and operatory units can be damaged in storage, delivery, or setup. Owned stock, customer property, and installed equipment can need different terms.
Try a different word, or check the spelling.
Delivery, testing and a practice's acceptance can change where protection for a dental unit begins or ends. Your device insurance should follow those stages and any calibration or training you provide, rather than assume generic transit or E&O includes every installation or medical-device allegation.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
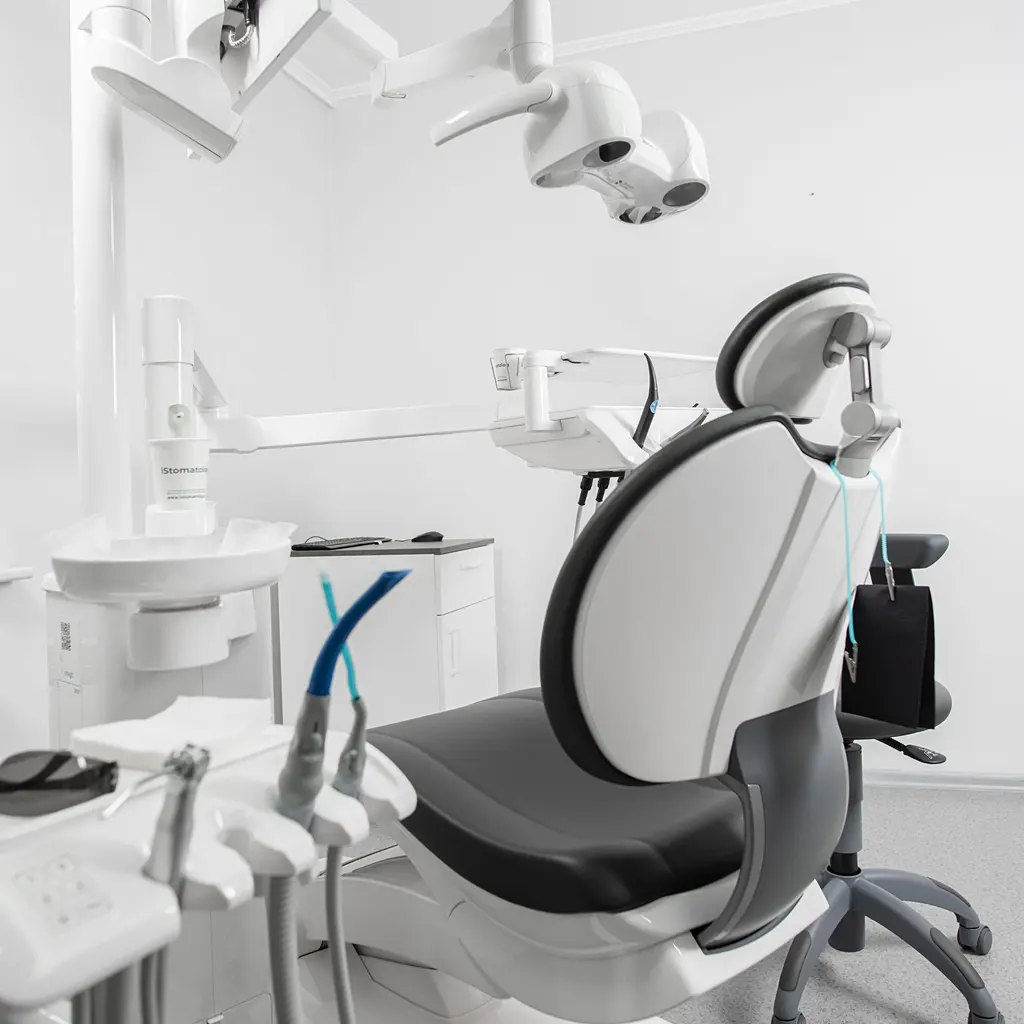
You supply and install dental equipment like sterilizers and imaging units, often providing on-site training and calibration. Installation errors or damage during transit can disrupt a practice and lead to both equipment and premises liability claims.
The Southern Agency can help you review delivery, installation and customer acceptance alongside any calibration or training you provide. We can compare transit and installation protection with liability terms that expressly address those services, rather than assuming generic professional coverage fits.
Imaging and operatory units can be damaged in storage, delivery, or setup. Owned stock, customer property, and installed equipment can need different terms.
Faulty connections can damage a practice. Selection, calibration, or training errors can produce separate financial-loss or injury allegations.
Storage-sensitive or expiring supplies need handling controls. Routine expiry differs from insured stock damage; technicians also travel and lift heavy units.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A unit is damaged en route to a practice. Applicable transit cover may address an insured loss, subject to value, handling, and insured-interest terms.
An incorrect water connection damages the practice. GL may address covered resulting damage, while correcting the connection and the worked-on property can be excluded.
A practice alleges a supplied sterilizer cannot perform as specified and seeks lost revenue. Without covered injury or property damage, product liability may not respond; suitable service/advice terms and contract exclusions need review.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Loss of use can fall within a policy's property-damage definition, even without physical damage, but that does not settle coverage. Review own-product, impaired-property, contract and service exclusions. A demand for lost practice revenue because a unit misses its specifications is not automatically an insured product claim.
It needs explicit service review, including any bodily-injury or professional exclusions.
Vehicle insurance does not automatically insure cargo. Review transit and installation interests.
Ordinary expiry is not the same as insured physical damage or covered spoilage.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.