

Textiles and moisture
Fabric and packaging contribute to fire load and can absorb smoke or water. Gradual moisture, mold, and flood may be excluded.
Try a different word, or check the spelling.
A few damaged rolls can leave a buyer without enough matching fabric for the whole run. Check dye-lot valuation and matching costs separately from an ordinary stock-loss limit.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
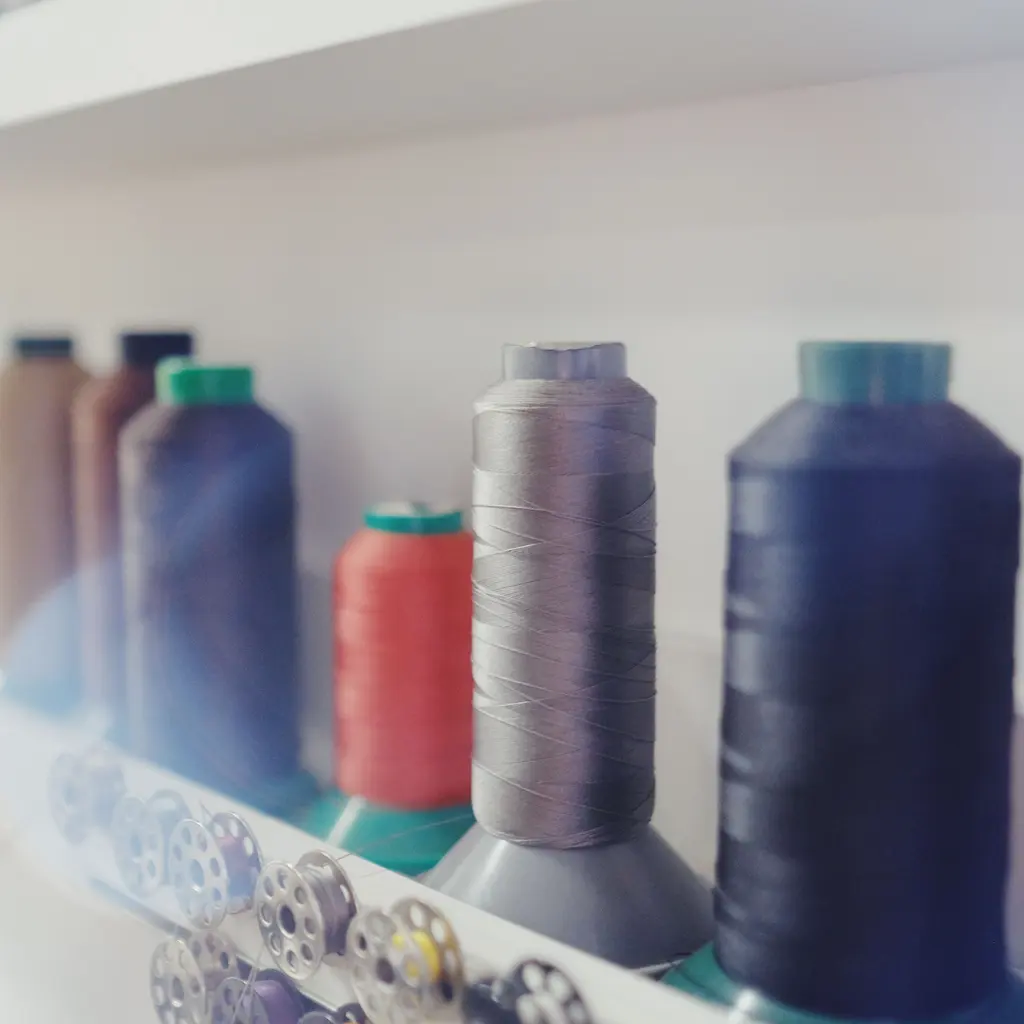
You supply fabrics, trims, and sewing notions to manufacturers, managing complex inventory like specific dye lots and seasonal orders. Damage from a leak in your warehouse or the loss of a specific shipment can disrupt a buyer's production run.
The Southern Agency can review your storage and order fulfillment processes to help you select appropriate insurance. We can discuss how property coverage protects your stock versus how transit insurance covers your mixed orders during delivery.
Fabric and packaging contribute to fire load and can absorb smoke or water. Gradual moisture, mold, and flood may be excluded.
A flawed fabric or fastener can lead to demands. A rejected batch or mismatched color without covered injury/damage may remain a commercial loss.
Small trims can disappear without proof of theft. Rolled fabric and repeated picking create handling injuries; seasonal loads need appropriate transit limits.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A sudden sprinkler leak damages a dye lot. Property may address insured stock loss, but matching remaining stock or paying its selling price requires applicable valuation terms.
A fire damages fabric intended for retailer orders. Property and included income cover may address eligible losses; contract penalties and every missed seasonal sale are not automatic payments.
Stock is stolen during delivery. Applicable transit/theft cover may respond if ownership, security, and unattended-vehicle terms fit; vehicle insurance alone does not insure the order.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
No. A specification dispute without insured physical damage has a different trigger.
Not necessarily. Matching, salvage, partial-loss and valuation terms determine payment.
No. Eligibility, insured damage, income calculation, waiting period, and limits all matter.
Only if facts and evidence fit a purchased agreement. Unexplained count shortages may be excluded.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.