

Trade paperwork is wrong
Classification, value, origin or timing errors can lead to disputes over extra costs.
Try a different word, or check the spelling.
A shipment can become your liability problem without ever becoming your property. Start with the promises you make to buyers, sellers and carriers.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
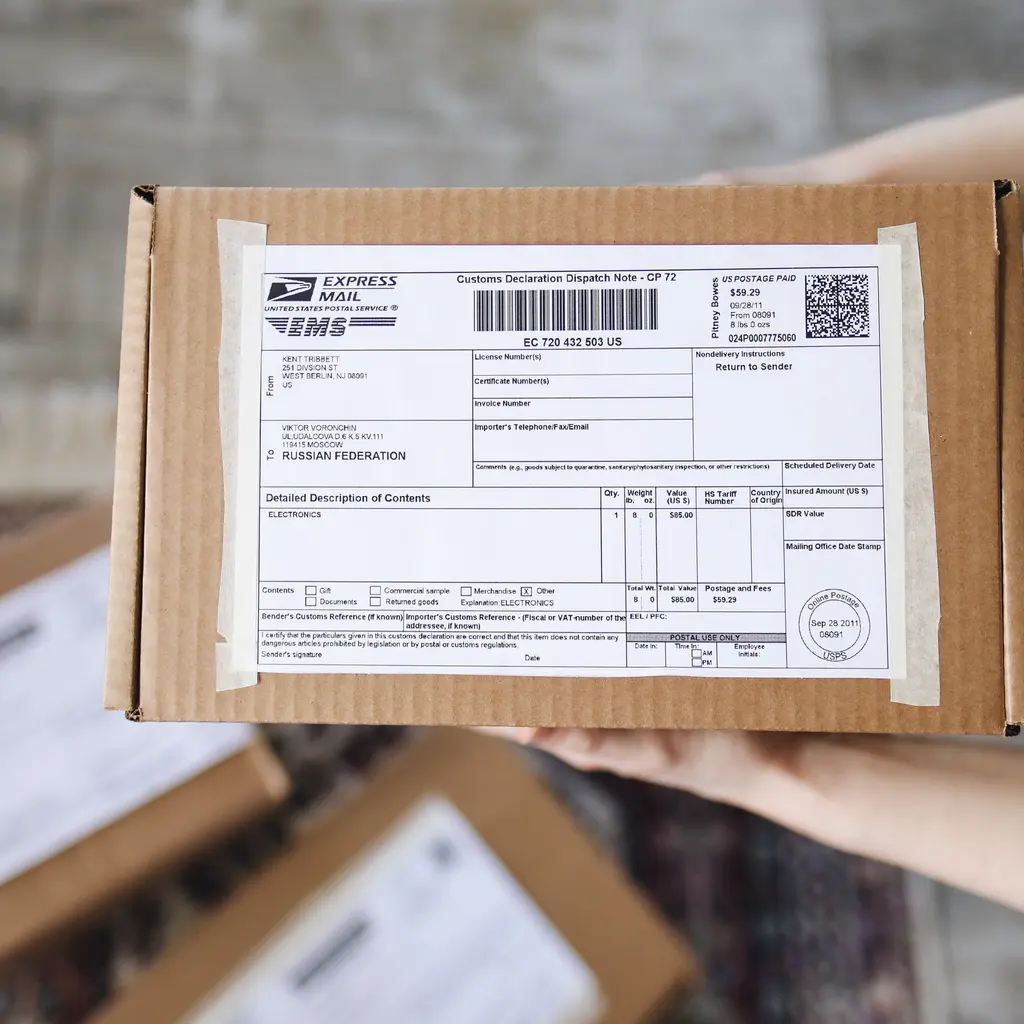
You connect buyers and sellers across borders and may arrange shipments or prepare trade documents. Even when you never own the goods, a missed instruction or filing error can lead to a claim for your client's extra costs.
The Southern Agency can review the services you perform and where your responsibility begins and ends. We can help you compare professional liability with cargo and crime protection so a policy for the goods is not mistaken for protection for your work.
Classification, value, origin or timing errors can lead to disputes over extra costs.
The broker's legal role and contracts determine responsibility for goods handled by others.
False payment instructions can redirect client or business money.
A breach or sanctions/export-control allegation can bring response costs, exclusions, and legal duties.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A client alleges your classification error delayed clearance and caused extra storage charges. Professional liability depends on the services and losses insured; the client's ordinary customs duties and any fines are separate questions.
A false email instructs your employee to send a client's duty payment to a new account. Review whether crime or cyber terms include that transfer, whose money was lost and which verification steps were required.
A truck crash damages a shipment you arranged, and the customer seeks reimbursement from you. Your legal role and broker-specific terms determine your protection; the carrier's cargo policy does not guarantee payment to you or the customer.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Professional mistakes can cause client financial loss. Review the exact authorized customs/trade services and excluded duties or fines.
Cyber may respond to certain fraud events, but transfer-fraud and voluntary-parting terms and controls must be explicit.
Possibly, under the legal role and contracts. Use appropriate broker/contingent protection rather than assuming trucker cargo applies.
Yes, but investigations, sanctions, and penalties are not automatically insurable or covered; qualified legal review may be needed.
Use the actual agreements. Requested E&O, cargo, and liability limits need insurer acceptance, not a certificate alone.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.