

Portable gear is stolen
Warehouse, carrier, and salesperson custody can each hold concentrated values.
Try a different word, or check the spelling.
A new camera model can reduce your older stock's selling value without damaging a lens. Insurance for photographic goods needs that distinction, with fragile-item handling, loans and rental custody reviewed separately from missing gear, battery claims or operating a drone.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
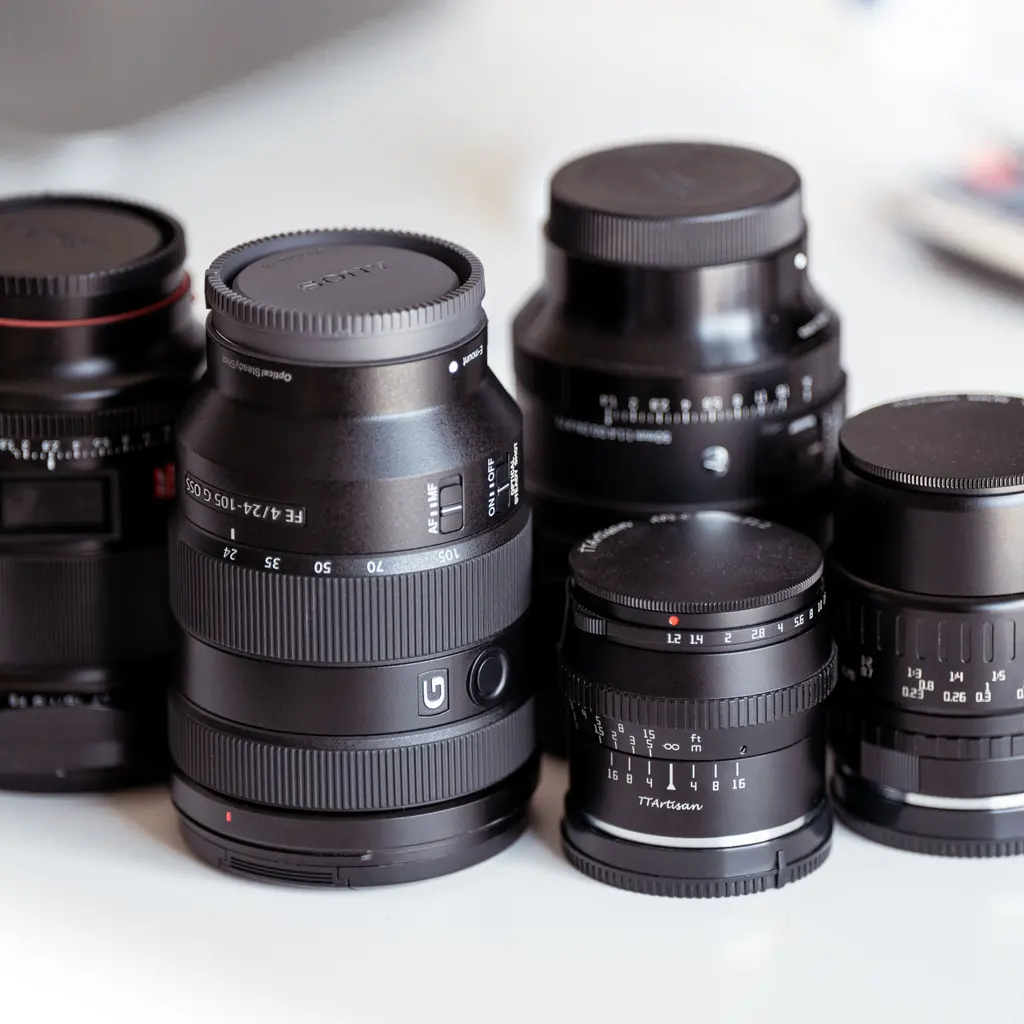
You distribute cameras, lenses, and lighting equipment that often move as small, valuable parcels or leave your warehouse for temporary rental and demos. A theft during transit or a customer injury claim stemming from a battery fire requires specific insurance protections.
The Southern Agency can review your warehouse security, distribution methods, and rental policies to help you select appropriate coverage. For instance, we can discuss how to protect your high-value inventory from theft.
Warehouse, carrier, and salesperson custody can each hold concentrated values.
Drops, moisture, and rough handling can damage cameras and optics.
Batteries and drones create product issues; operating a drone is a separate declared activity.
Model changes can reduce sale value without physical damage; employee theft and account-data losses need separate review.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
Ready to compare options?
Get a quote for Photographic Equipment and Supplies Distributor Or call 1-800-777-1TSAThese hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Premium lenses disappear after a carrier collects a shipment. Transit protection needs to fit the goods, carrier stage and per-parcel value, with evidence of the loss. The carrier's liability may be less than the full stock value.
A supplied battery is blamed for a fire that damages a customer's studio. Product liability may address covered defense and resulting damage if the battery and use are included. Replacing the battery and withdrawing other stock are separate costs.
An employee takes camera bodies from the demo inventory. Employee-theft terms may address a proven covered loss, subject to insured interests and limits. A discrepancy in the stock count alone may not satisfy the evidence requirements.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Use suitable parcel/equipment terms with enough limits for concentration, breakage, and carrier stages.
Employee access creates exposure, but coverage requires appropriate crime terms and evidence, not just a missing count.
They alter product, storage, and shipping risk. Flying a drone also needs separate operational review.
Update values using the policy basis; lost market value without damage is not automatically insured.
Only declared interests, uses, locations, and custody conditions should be relied on.
Ordering and customer records can create privacy and interruption losses distinct from lost equipment.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.