

Slope and lift injuries
Collisions, falls, and loading incidents can harm guests.
Try a different word, or check the spelling.
Your lift and snowmaking repairs may affect the season differently from a shortage of snow. Breakdown and income terms need to distinguish insured equipment failures from weather-driven demand, alongside slope and instruction liability.
The Southern Agency can help you compare lift and snowmaking dependencies, rental-fitting duties and the mountain activities your liability layers accept.
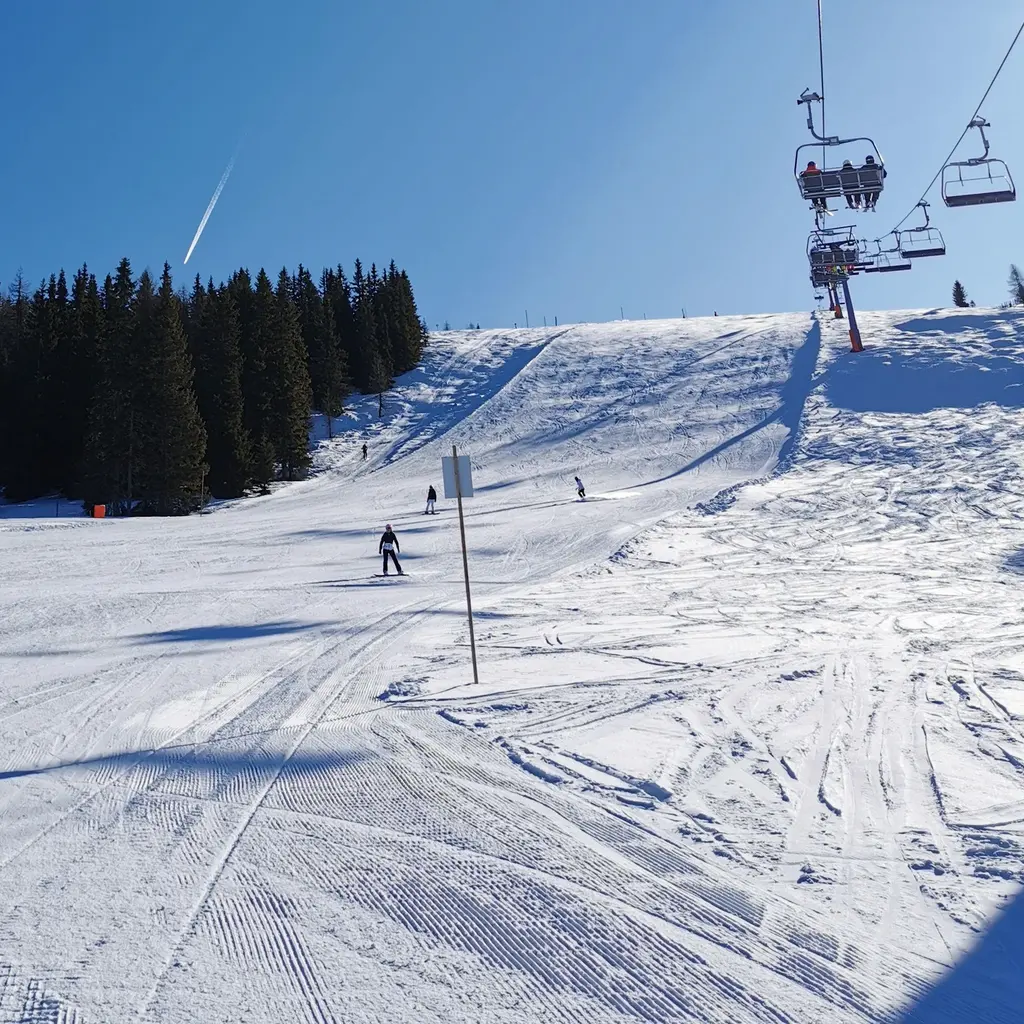
You manage slopes, chairlifts, rental shops, instruction programs, and base lodges. A lift-loading injury or a failure in snowmaking equipment can disrupt your operations and create liability exposure.
The Southern Agency can review your mountain operation, from grooming to instruction, to help select appropriate insurance. For example, we can assist in distinguishing between physical equipment breakdown and seasonal income fluctuations.
Collisions, falls, and loading incidents can harm guests.
Lessons or binding adjustments can lead to allegations about services or equipment.
Lifts, groomers, and snowmaking systems are valuable operational dependencies.
Snow, storms and cold affect access, safety and revenue in different ways.
Lodges, restaurants, bars, and seasonal employees add separate exposures.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Hypothetical: a guest is injured while loading a chairlift and alleges operator error. Liability may address covered defense and damages under accepted lift, rider and operating duties. Preserve incident and maintenance records; a lift inspection or guest waiver does not decide fault, and rider liability is not machinery repair.
Hypothetical: a skier alleges a rental binding was adjusted incorrectly and caused injury. Compare actual fitting duties, insured staff and accepted rental, product and instruction/service terms. Premises cover alone does not establish every fitting allegation; the injury claim differs from replacing equipment or correcting all bindings.
Hypothetical: an internal pump failure stops snowmaking and some terrain remains closed. Breakdown may address qualifying repairs; selected income terms must address the actual interruption, waiting period and measured loss while other slopes operate. Low natural snowfall or every delayed opening is not automatically an insured machinery loss.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
The program depends on slopes, lifts, rentals, and hospitality actually operated, not the resort label alone.
Lift liability to riders and repair of the machinery are distinct interests.
Binding fitting can generate service or product allegations; review the rental operation expressly.
Poor snowfall alone may not trigger ordinary business income. Check any separately offered weather terms.
Where alcohol is served, identify the operator and compare liquor provisions.
Severe insured guest claims may exceed primary limits; compare excess exclusions with the mountain program.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.