

Aquatic injuries
Pools, wave features and slide run-outs expose guests to drowning, collisions, and other serious injuries.
Try a different word, or check the spelling.
Humidity is an everyday operating condition around your indoor pools, not automatically an insured event. Machinery and property protection need to distinguish sudden damage from gradual corrosion, mold, and maintenance.
Describe every water feature, supervision arrangement and shared treatment system when reviewing protection for the park.
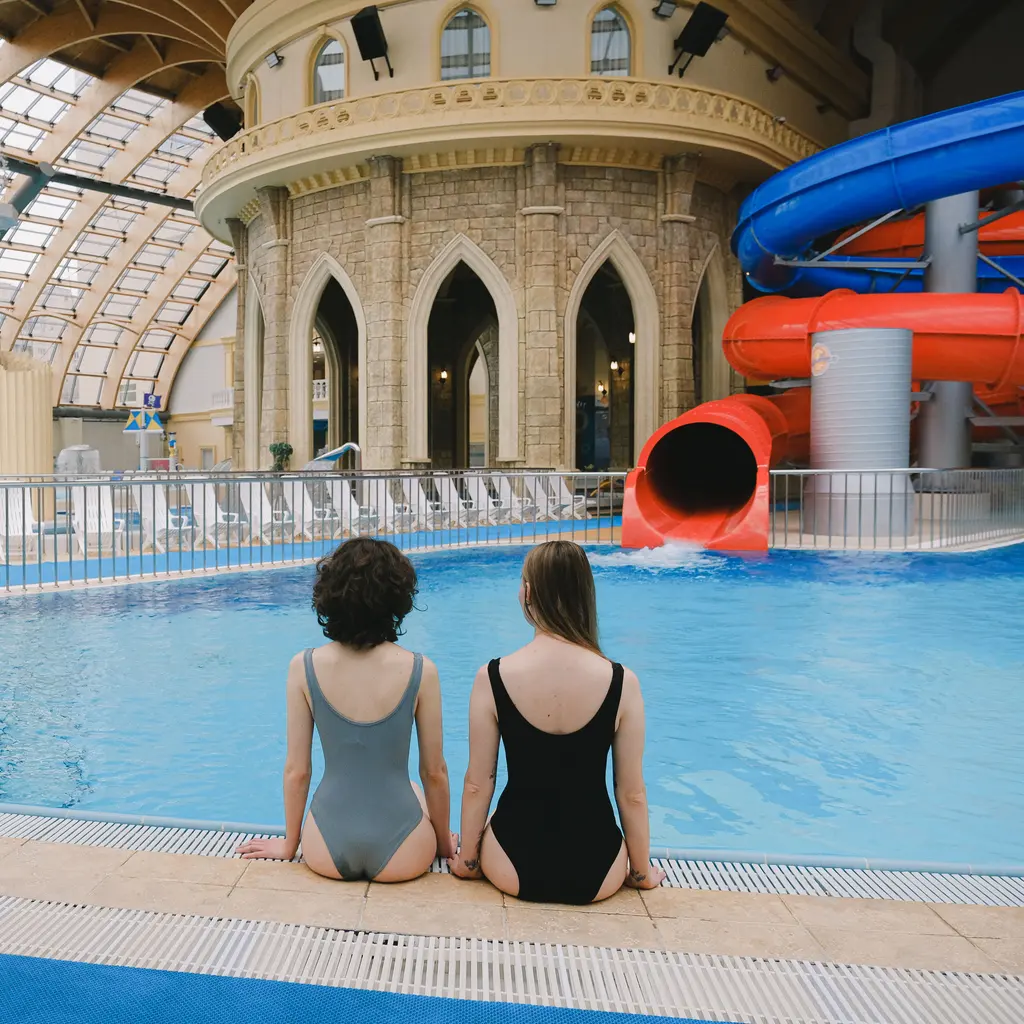
You operate pools, slides, and splash areas inside a facility that relies on specialized water-treatment machinery. A failed pump can force the closure of entire attractions, while a guest could potentially be injured in a wave pool.
The Southern Agency can review your actual pools and slides, who supervises them and the systems needed to keep them open. We can examine guest claims and employee injuries alongside machinery repairs, lost admissions and chemical incidents, distinguishing an insured event from routine upkeep in a humid building.
Pools, wave features and slide run-outs expose guests to drowning, collisions, and other serious injuries.
Decks, stairs and changing areas can become slippery even when the pools operate normally.
Storage or handling of pool chemicals can cause a spill or an allegation about indoor air quality.
Filtration, heaters, and pumps keep attractions open; failure can stop admission until water systems are restored.
Long-term humidity can affect finishes and machinery, while a sudden fire or storm can cause a different property loss.
Lifeguards and maintenance employees can be injured during rescues or while handling equipment.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Suppose a guest needs rescue in the wave pool and the family alleges inadequate supervision. Review whether the wave feature and participant injuries are included, who provided lifeguards and the policy's treatment of the allegation. A staffing plan alone does not establish either coverage or fault.
Suppose two riders collide in a slide run-out and one alleges that dispatch intervals were too short. General liability may address a covered claim involving the disclosed slide. Review the operating facts, responsible attendants and any participant or attraction restrictions rather than assuming ordinary premises terms cover every ride.
Suppose a filtration pump suffers an internal mechanical failure and the pools it serves close while a replacement is sourced. Breakdown terms may address the covered repair; admissions earnings and extra expense need the corresponding grants and restoration period. Maintenance shutdowns and a water-quality closure without insured equipment damage are not automatically the same loss.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
The business may need separate liability, property, breakdown, and employee cover, depending on its actual water features and workforce.
Describe every swimming and slide activity when reviewing liability. The presence of lifeguards does not itself confirm the policy covers a particular claim.
A chemical spill and ordinary pool-water treatment are different exposures. Check pollutant definitions, affected locations, and the chemicals used.
Breakdown may address insured pump repair; lost admission revenue needs purchased income coverage and may have a waiting period.
Slow corrosion or mold from humidity can be treated differently from sudden covered building damage. Read the cause-of-loss and exclusion terms.
Higher limits may be useful for a severe insured claim, but excess wording must be compared with the underlying aquatic liability form.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.