

Guests at the water
Wet piers, ramps, and ladders expose visitors and boaters to falls or drowning.
Try a different word, or check the spelling.
A boat in your lift is still the customer's vessel, and damage to it is not the same as damage to the lift. Custody liability and direct boat protection need to be distinguished from your marina property coverage.
The Southern Agency can help you review when custody starts, which waterfront assets you own and the separate fuel or crew duties involved.
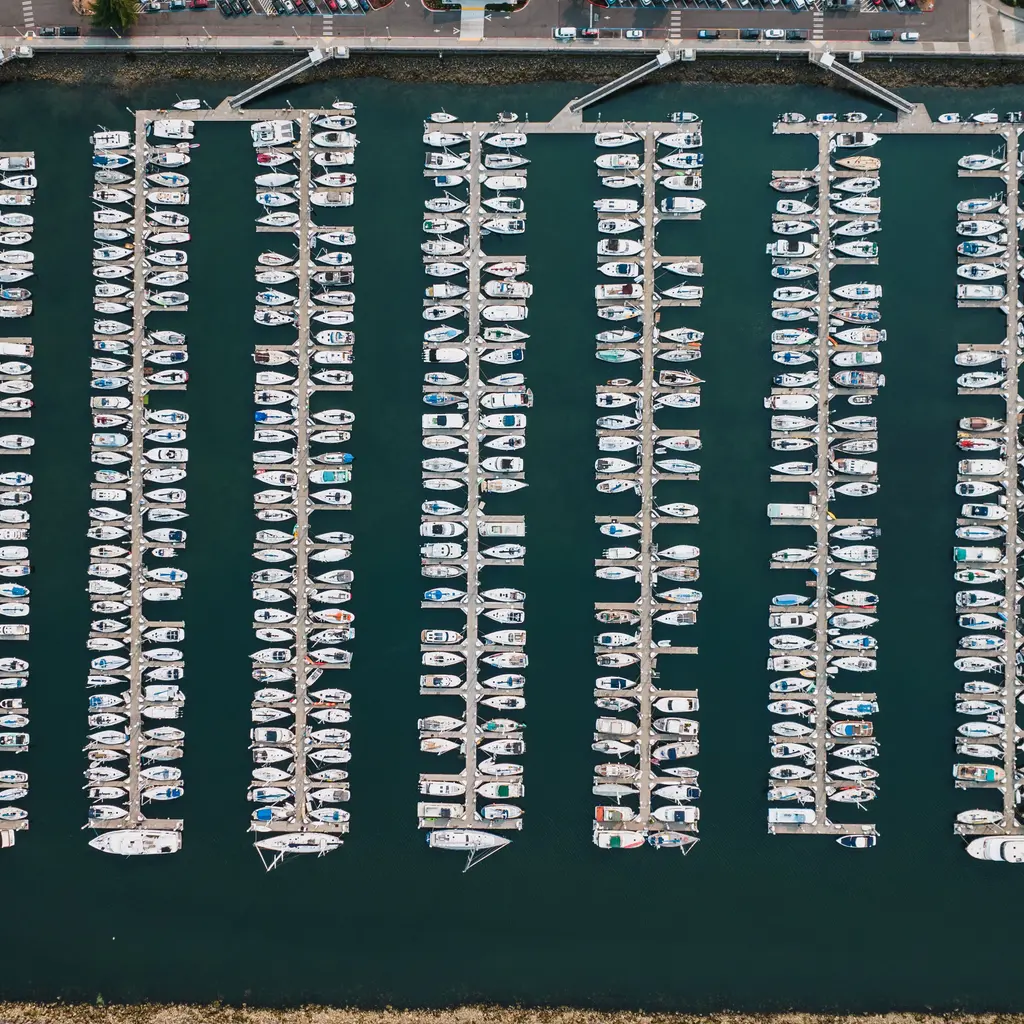
You operate a marina that provides dock access and slip rentals, while potentially fueling, lifting, and repairing customer vessels. A lifting accident could damage a boat in your care, or a fuel spill could impact water beyond your immediate property.
The Southern Agency can review your custody responsibilities and waterfront services to help you select appropriate insurance. We can discuss, for instance, how to address legal liability for customer vessels separately from your own docks and buildings.
Wet piers, ramps, and ladders expose visitors and boaters to falls or drowning.
Fueling, haul-out, storage, and repair can put customer-owned vessels in the operator's custody.
A spill at a fuel dock can lead to cleanup and third-party allegations.
Storm, wind, wave action and flood can damage docks, lifts, racks, and vessels in different ways.
A travel lift can fail, drop a vessel or stop work even without storm damage.
Employees working near water or with boats and equipment can be injured.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Hypothetical: a customer's boat falls during haul-out. Specialist marina legal-liability terms may address covered vessel damage for which the insured operator is responsible under actual custody and handling duties. Identify boat value and lift arrangements; owning lift insurance does not itself provide direct insurance on every customer's boat.
Hypothetical: fuel reaches the water during a fill-up. Accepted pollution terms may address covered response and third-party harm under actual dock/transfer duties, substance, site and reporting. Separate spilled fuel, pump damage, vessel cleanup and regulatory demands; the water release alone does not establish every cost is insured.
Hypothetical: a storm damages piers and boats stored nearby. Compare declared dock/building property with actual vessel ownership and any custody liability or direct boat cover. Wind, wave and flood terms may differ; the marina is not automatically liable for customer storm damage and dock coverage does not insure every stored boat.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
The relevant mix depends on slips, fueling, boat storage, and repair. Premises liability does not alone insure customer vessels or fuel cleanup.
Marina operators legal liability may address damage to a customer's boat where the operator is responsible; inspect custody and activity definitions.
Pollution terms can address some fuel spills. Check the location, pollutant definition, cleanup trigger, and limits.
Wind and flood provisions may differ for buildings, docks, and vessels. Identify who owns the stored boats.
A dropped boat can involve lift repair and liability for the vessel. Breakdown insurance on the lift does not itself establish cover for the boat.
Slip leases may set insurance obligations. Compare the particular lease and any lender request with the proposed policy before promising an insured status.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.