

Freezer breakdown and spoilage
Continuous refrigeration is essential, and a freezer failure or power loss can spoil a large frozen inventory within hours.
Try a different word, or check the spelling.
If you make the ice cream you scoop, your shop has production duties as well as counter service. Coverage should account for those batches and ingredients, not only the freezer and the people visiting.
The Southern Agency can help you review your freezer dependencies, made or supplied desserts and counter service against separate stock and liability terms.
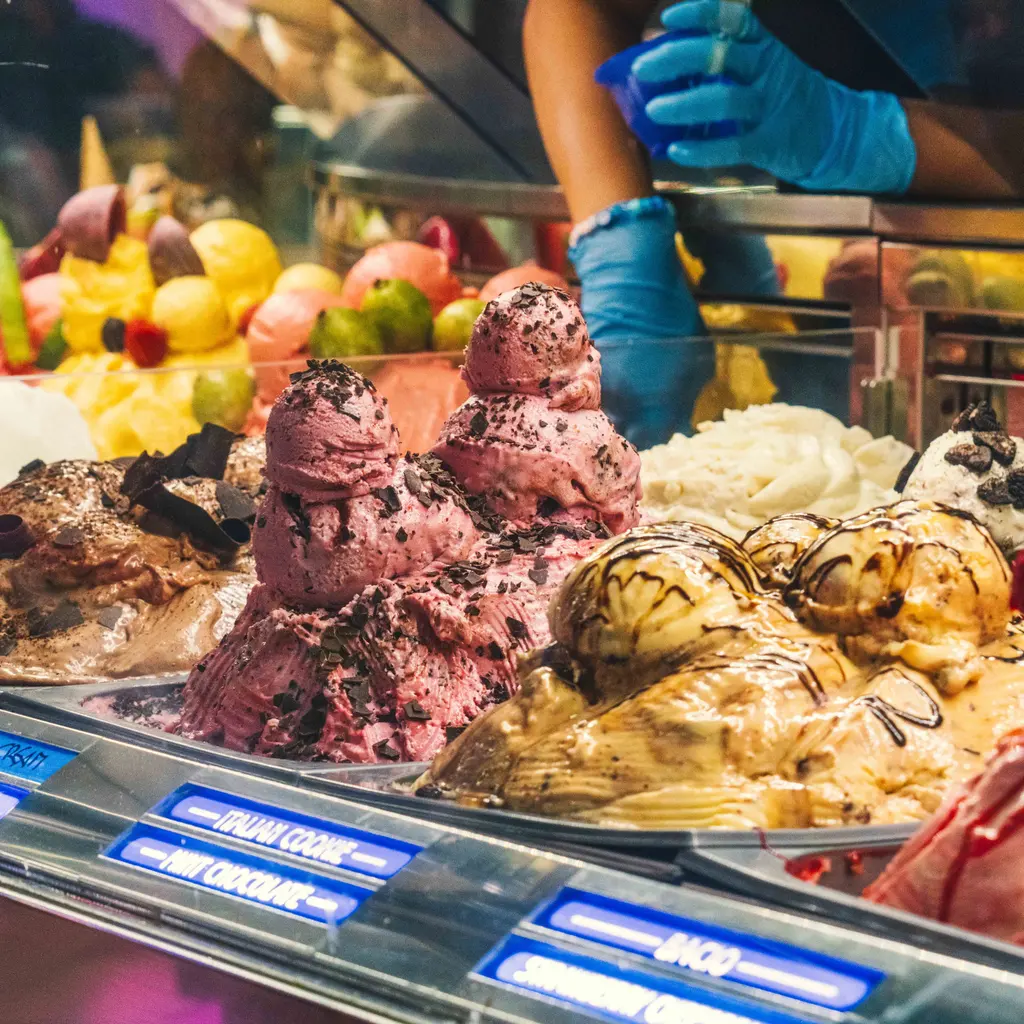
You keep frozen stock ready to scoop while handling toppings, shared utensils and customers at the counter. A freezer outage can melt your summer inventory; an allergen mistake can injure a customer whether you make the ice cream or buy it in.
The Southern Agency can help you review your shop's allergen practices and cooling dependencies to select appropriate insurance, such as a policy covering equipment breakdown and spoilage.
Continuous refrigeration is essential, and a freezer failure or power loss can spoil a large frozen inventory within hours.
Nuts, dairy, eggs, and shared scoops create cross-contact exposure that can cause reactions in sensitive customers.
Melted product, spills, and family foot traffic create slip-and-fall exposure around the counter and seating area.
High card-transaction volume creates cyber and PCI exposure if point-of-sale systems are compromised.
Shops making their own ice cream face batch-quality, contamination, and equipment exposure beyond simple scooping.
Freezers, display cases, furnishings, and tenant improvements are vulnerable to fire, water damage, and theft.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A freezer fails overnight and the inventory melts before opening. Equipment breakdown with spoilage coverage may respond to the lost product, depending on policy terms and the endorsements in place. Check covered freezer/utility cause, stock inclusion, and peak valuation; melted stock alone does not establish a trigger.
A customer has a reaction after a shared scoop transfers nut traces and files a claim. General liability coverage may respond to defense and damages, subject to the specific policy and facts. Check products/food injury terms and facts; pulling flavors or refunds require separate analysis.
A child slips on melted ice cream near the counter and is injured. General liability coverage may help with medical and liability costs, depending on policy terms and conditions. Review actual premises responsibility and injury facts; customer age does not decide coverage.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Frozen inventory melts quickly when refrigeration fails. Equipment breakdown with spoilage endorsements may respond to lost product, depending on the policy, endorsements, and exclusions.
General liability commonly responds to allergen-related injury claims, though strong labeling helps manage the risk. Coverage depends on policy terms, exclusions, and the facts of the incident.
Yes. On-site production adds batch-quality, contamination, and equipment exposure beyond scooping. Coverage should reflect that, and availability depends on underwriting and operations.
Even a small shop should identify who runs the POS, holds card data and can access the processor account. Purchased cyber benefits may help with an eligible breach response. Processor assessments, contractual penalties, refunds and a terminal outage need separate terms.
General liability commonly responds to slip-and-fall injuries around the counter and seating. Coverage depends on policy terms, exclusions, and the facts established.
Business income coverage may respond when a covered breakdown or loss disrupts operations, helping with lost revenue. Coverage depends on the specific policy and exclusions.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.