

Dancing and circulation
Smooth floors, formal footwear, and changing layouts can contribute to falls.
Try a different word, or check the spelling.
Your venue's cash and a guest's wedding gifts do not become the same insured property simply because both are in the ballroom. Crime and property terms need to distinguish those interests from restoring the floors, lighting, and finishes.
Review who holds gifts, who operates the bar and what it would cost to restore your fixtures and finishes.
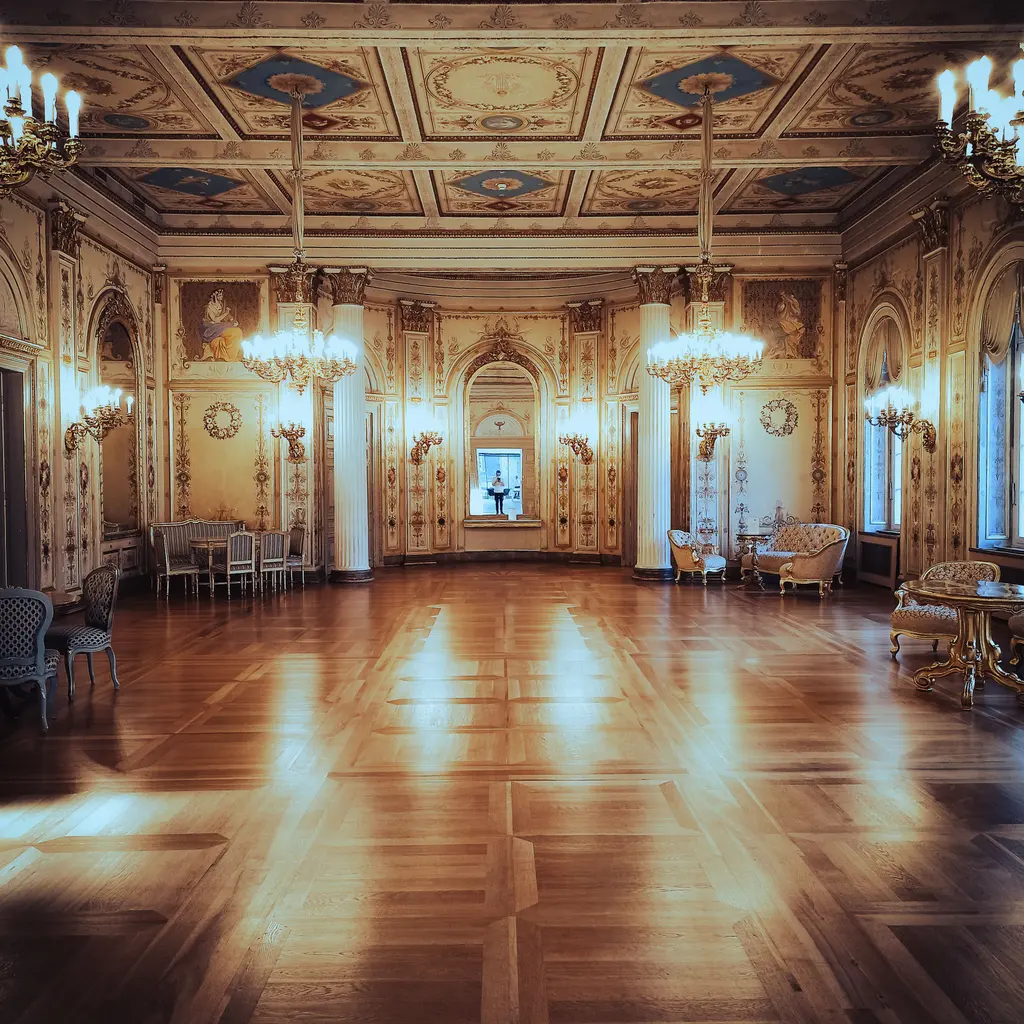
You host events in ballrooms where finishes and lighting are central to your business. A guest fall or a water leak can create significant liability or property damage claims.
The Southern Agency can review your venue's bar service, vendor arrangements, and decorative fixtures to help you select appropriate insurance. For example, we can assist in identifying the coverage distinction between guest injury liability and the repair of your facility's finishes.
Smooth floors, formal footwear, and changing layouts can contribute to falls.
A bar can generate allegations involving an intoxicated guest.
Chandeliers, flooring, and drapery may cost more to restore than ordinary fittings.
Caterers, musicians, and decorators can cause injury or damage.
Gifts, cash, and canceled functions involve interests beyond building repairs.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Suppose a guest falls during a reception and alleges that a polished floor was unsafe. Review the condition, cleanup and layout duties, and the venue's accepted event activities. Liability may address a covered allegation; formal footwear or a fall alone does not establish fault.
Suppose the ballroom is named after a guest allegedly causes harm following bar service. Identify the actual seller, server and venue duties and compare the applicable liquor and liability grants. An outside bartender's certificate does not establish that every allegation against the venue is included.
Suppose a pipe leak damages lighting and closes the ballroom before a gala. Covered property terms determine fixture repair and valuation; purchased income terms determine eligible earnings loss during restoration. A valuable chandelier, postponed gala and promised deposit refund are not the same insured interest.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Alcohol service creates a distinct liability discussion, regardless of how formal the event is.
Schedule the actual fixtures and review valuation, deductibles, and covered perils.
Income needs a covered cause and applicable restoration terms; deposit refunds are not automatically insured.
Outside service does not prevent the venue being named; compare its own duties and vendor protection.
Guest gifts require explicit custody and property wording; venue crime cover may not fit.
A fall can involve floor condition, spills, lighting or the event layout. Describe who maintains the floor and handles cleanup, including during a reception. Actual allegations and liability terms matter more than assuming every dance-floor injury is the venue's fault.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.