

Food and fire
In-house cooking can lead to illness allegations or kitchen damage.
Try a different word, or check the spelling.
Your bar may use outside staff even while the hall provides the food and event space. Liquor and food protection need to match who actually serves, with equipment repairs and deposit disagreements kept separate.
Identify staff and vendor food or bar duties, event dependencies and the actual cancellation promises in function contracts.
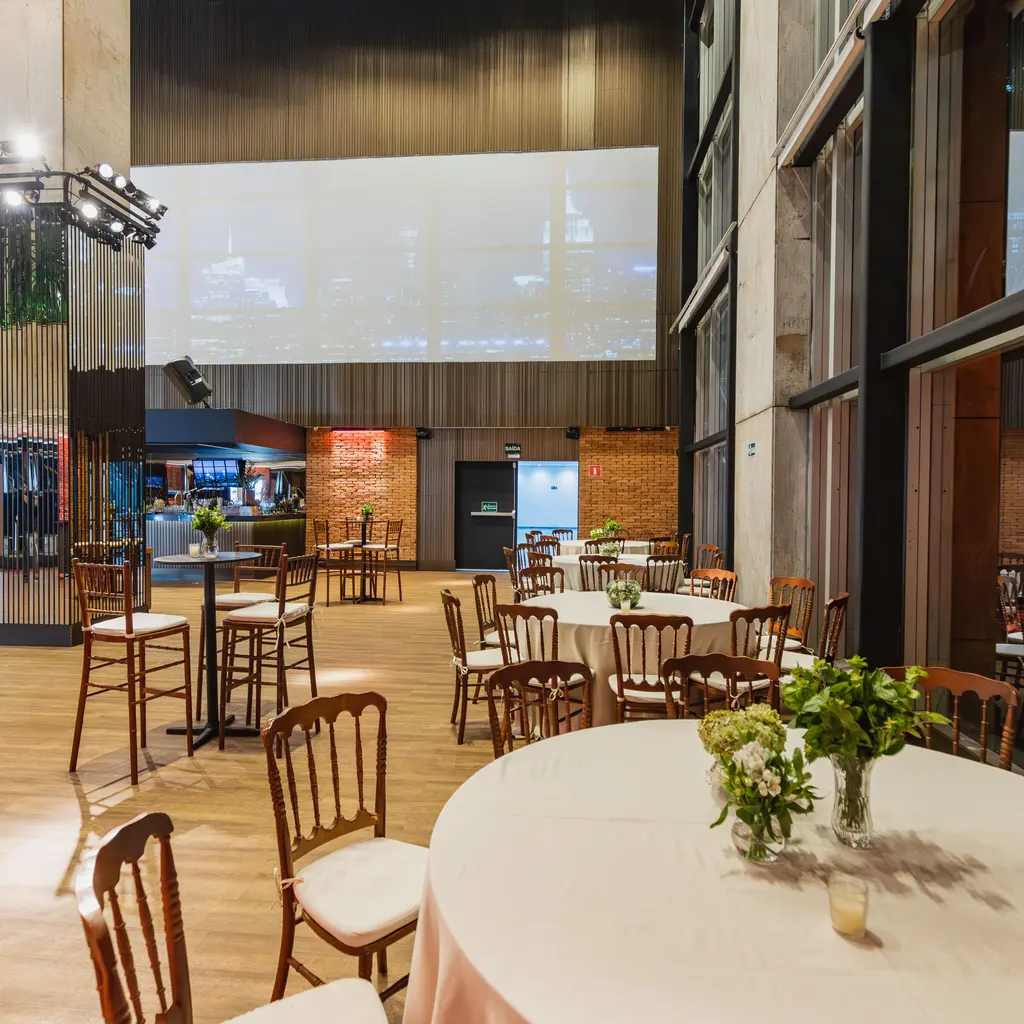
You provide space for celebrations, with food and bar service handled by your staff or outside providers. A spill near a buffet can lead to a guest claim, while a kitchen fire can interrupt the booking schedule and damage your property.
The Southern Agency can review your catering and bar responsibilities to help you select suitable insurance. We can compare liability for guest or food allegations with property, equipment and income terms, so an event commitment is not mistaken for an insured loss.
In-house cooking can lead to illness allegations or kitchen damage.
Buffets, seating, and dancing can create fall claims.
Intoxication allegations may involve the hall and outside staff.
HVAC, sound, and kitchens support the event schedule.
Service injuries and deposit disputes have distinct policy interests.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Suppose the hall is named after a guest allegedly causes harm following bar service. Identify who supplied and served the drinks and the allegations against each party. Applicable liquor terms and endorsements—not an outside server's certificate alone—determine possible protection.
Suppose a guest slips near the buffet and alleges inadequate cleanup. Review actual service and inspection duties across the hall and caterer and the accepted food or premises activities. The fall alone does not establish fault, and a contract does not automatically make every party an insured.
Suppose a kitchen fire prevents the next booked function. Covered property and purchased income terms may address eligible repair and earnings loss during restoration. Review the actual interruption and service alternatives; refunding a deposit or paying the client's replacement venue is not automatically included.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Coverage depends on services provided, people employed, and property interests.
An in-house bar needs liquor review; general liability alone does not establish protection.
Income needs a covered trigger and applicable restoration terms.
Food-illness allegations may fit liability; replacement meals and recalls are separate expenses.
Client and caterer policies can address their duties but do not automatically include the hall.
Guest capacity, services, and contracts inform limits; no universal minimum is assumed.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.