

Reception bars
Hosted or open bars can lead to intoxication allegations.
Try a different word, or check the spelling.
You can remain part of an alcohol-related allegation when an outside bartender pours at your reception. Liquor terms need to match the actual arrangement, separately from property damage, event refunds, and other booking costs.
Bring hosted-bar and vendor arrangements, rented decor interests and the exact date-specific refund commitments in client contracts.
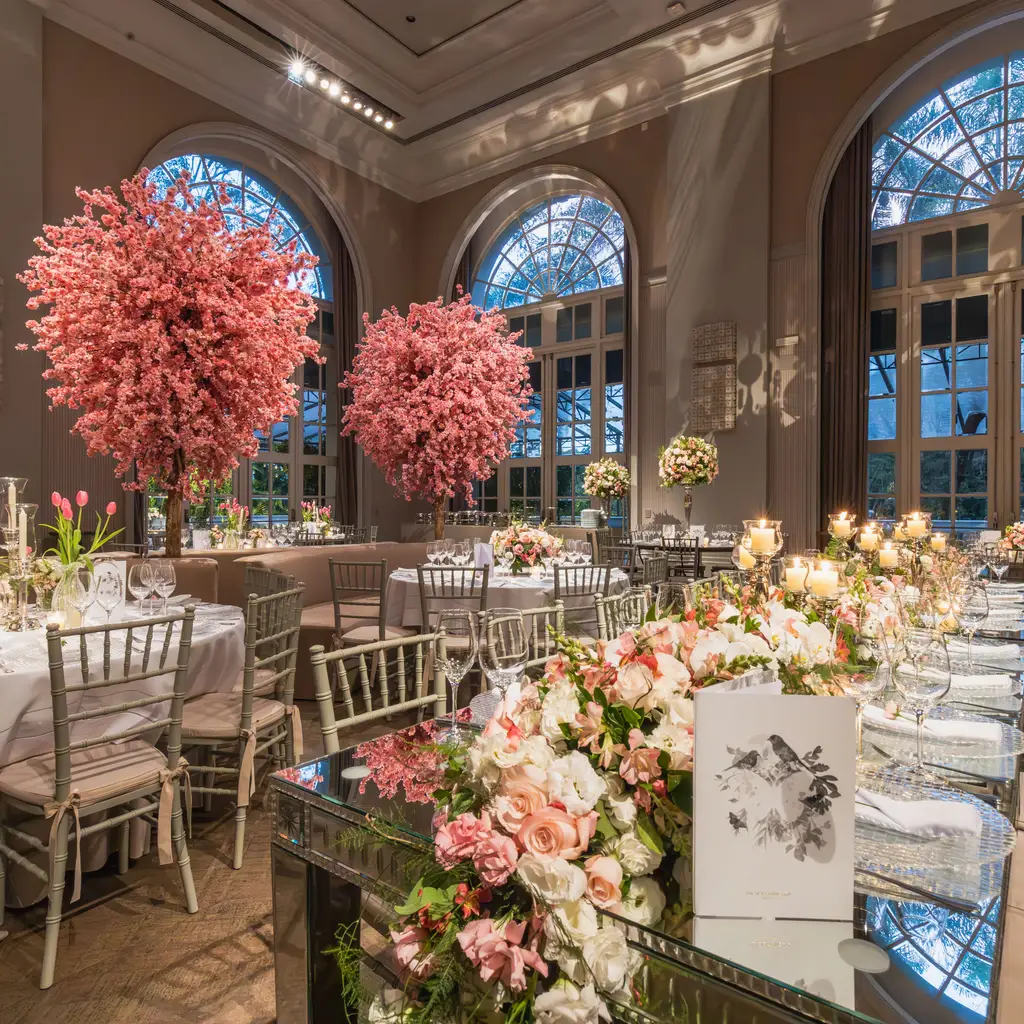
Your reception hall centers on wedding dates and large celebrations. A last-minute cancellation or damage to decor days before a wedding creates disputes and income loss beyond simple building repairs.
The Southern Agency can review your booking contracts and service offerings to help you select appropriate insurance. We can discuss how your policy covers your income versus the potential costs your clients might incur.
Hosted or open bars can lead to intoxication allegations.
Dance floors and service areas can create falls.
Food preparation and cooking depend on who provides the service.
Owned and rented lighting or furnishings have different property interests.
Cancellation, deposits, and staff duties require separate review.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Suppose the hall is named after a guest allegedly causes harm following an open bar. Review the actual supplier, server and venue duties under applicable liquor terms and endorsements. An outside bartender or client policy does not automatically include the hall's own alleged conduct.
Suppose a guest alleges that a spill or temporary dance-floor edge caused a fall. Identify who installed, inspected and cleaned the area and the hall's retained duties. Liability may address a covered allegation, but neither injury nor a vendor agreement alone establishes fault or insured status.
Suppose covered building damage makes the hall unavailable days before a wedding. Property and purchased income terms may address eligible repair and earnings loss during restoration. The couple's replacement venue, deposit refund and other promised cancellation remedies are separate costs, not automatic benefits.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Actual property, services, staff, and bar operations determine the cover mix.
Review liquor provisions for the specific open or hosted-bar arrangement.
Client event cover and vendor policies address their own duties; they do not automatically include the hall.
Income needs a covered cause and relevant restoration terms, not simply a canceled wedding.
Rented items need accepted ownership interests and schedules; owned-property cover may not fit.
Capacity, alcohol duties, and contractual requirements inform limits without establishing a universal minimum.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.