

Location hazards
Wind, flood, wildfire, and snow conditions depend on the site.
Try a different word, or check the spelling.
Your busiest rental weeks can arrive before repairs to a seasonal property are finished. Income protection needs to fit the booking pattern and insured cause of damage, separately from vendor duties, gradual deterioration, and routine upkeep.
Use actual peak-season revenue, local inspection arrangements and site-specific peril terms when reviewing lost-rent protection.
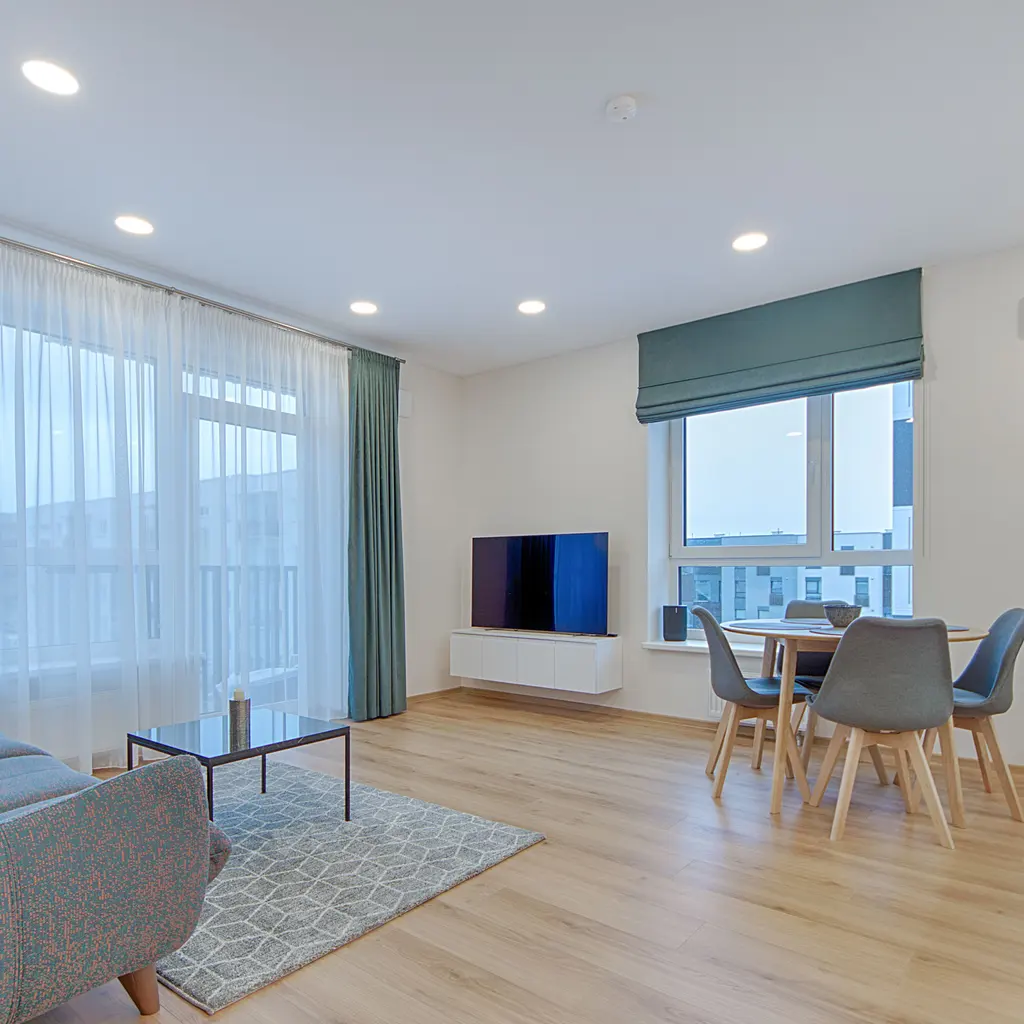
You rent a destination property that may be far from home and earn much of its income in a short season. Storm damage can interrupt bookings, while a leak between stays may grow before anyone discovers it.
The Southern Agency can review your rental schedule, local management and property to help you select insurance. We can discuss building and guest-liability protection together with any accepted rental-income benefits, keeping gradual damage and maintenance separate.
Wind, flood, wildfire, and snow conditions depend on the site.
Docks, pools, decks, and hot tubs create injury questions.
Delayed discovery can increase water or other damage.
Local vendors and managers may retain inspection duties.
Damage during peak bookings can have a concentrated income effect.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Suppose a coastal storm damages the rental before peak weeks. Identify the wind and water causes and applicable deductibles before reviewing covered repairs and purchased income terms. A hurricane label, seasonal demand or canceled reservation does not by itself establish flood protection or full revenue recovery.
Suppose a guest alleges that a defective dock surface caused an injury. Review actual ownership, maintenance duties and accepted dock or waterfront use under liability terms. Disclosing a dock does not establish every boating activity, guest item or property interest is included.
Suppose a cleaner discovers water damage between bookings. Establish the leak's cause and duration, occupancy and inspection facts before comparing property terms. Gradual damage, vacancy or unoccupancy conditions and maintenance can restrict recovery; hiring a manager does not remove those conditions.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Paid guest use must fit the dwelling and liability forms; the building's residential appearance does not establish that.
Each peril needs review; flood or wind may require separate provisions.
Amenities need both property and guest-liability review where relevant.
Income requires a qualifying event and applicable restoration terms, even during peak season.
A manager changes who performs work but not automatically who is insured.
Slow damage and vacancy conditions can restrict recovery; disclose empty periods and inspection arrangements.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.