

Catastrophic heavy-equipment product liability
Rollovers, boom swings, and hydraulic or brake failures on jobsites can cause severe injuries, driving high-severity product claims.
Try a different word, or check the spelling.
Your operator controls, sightlines, and warnings go to the jobsite with each machine. Liability protection should account for those features and actual dealer commitments without treating warranty service, machine correction, or recall as automatic benefits.
The Southern Agency can help you review coverage for machinery production, dealer liabilities, and fabrication equipment.
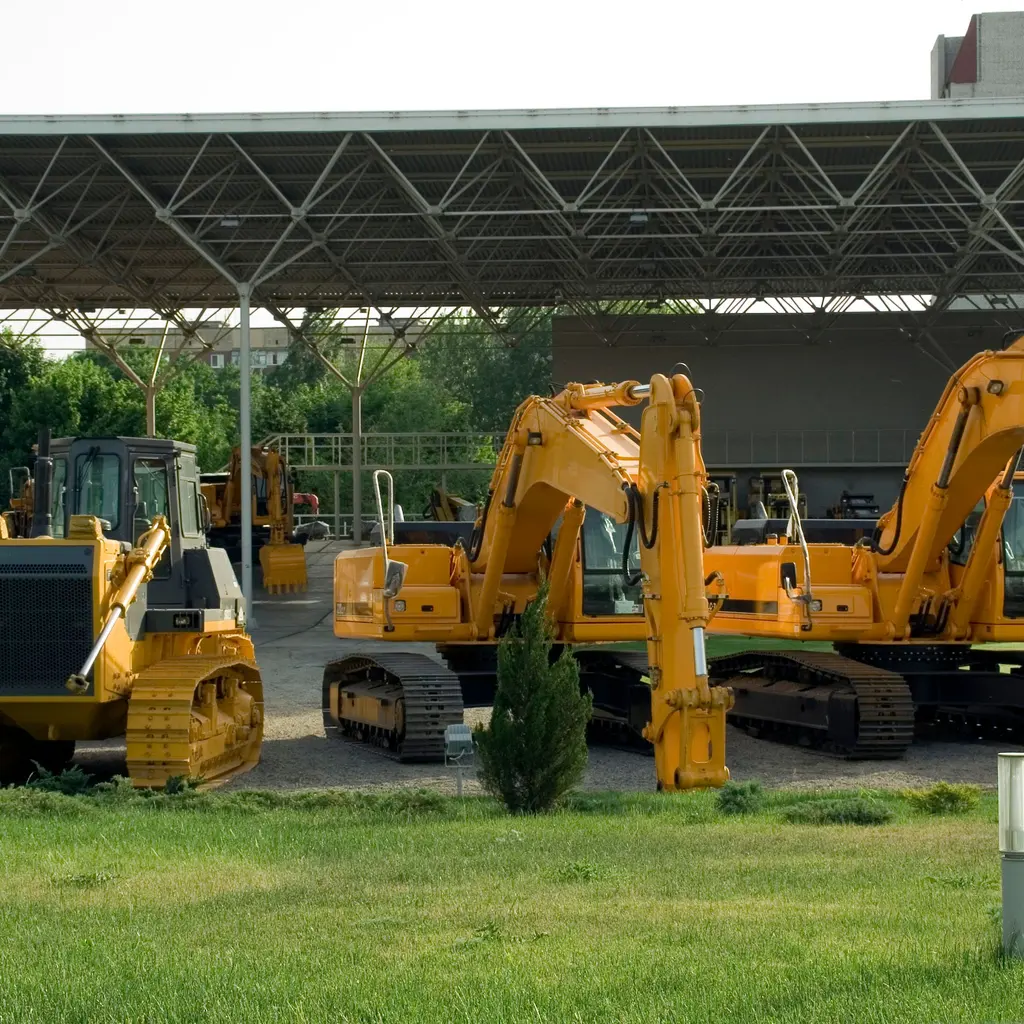
Your machinery production involves large-scale steel fabrication, welding, and assembly, where a design flaw or equipment failure can cause catastrophic injuries on a jobsite. The high value of your materials and heavy machinery makes fire or breakdown a threat to your operations.
The Southern Agency can review your fabrication, testing and dealer contract requirements to help select insurance for your business. For instance, we can discuss coverage for your finished machinery and manufacturing tools while addressing the liability associated with equipment used on construction sites.
Rollovers, boom swings, and hydraulic or brake failures on jobsites can cause severe injuries, driving high-severity product claims.
Injury claims often focus on operator controls, guarding, visibility, and warnings on complex high-power machines.
Large steel handling, hot work, and machining create fire, crush, and burn exposure across the plant floor.
Large CNC machines, presses, and hydraulic test rigs can fail, halting production on a backlog of expensive units.
Steel, drivetrain components, and finished machines represent very high property values exposed to fire and damage.
Dealers and fleets impose demanding insurance and indemnity terms, and a safety defect can trigger major recall costs.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
An operator is injured when a machine tips on a slope and alleges a stability or warning defect. Product liability may respond to defense and claim costs, depending on the policy, endorsements, and exclusions. Check the machine, end use and injury allegation included, then review own-product, warnings and design, contract, and recall terms. The operator's injury alone does not establish that the claim is covered.
A large fabrication press fails and stalls assembly of finished units. Equipment breakdown and business income may help, depending on the policy and exclusions. Establish the covered internal press event and stock and income protection purchased, including waiting and restoration periods. Backlogs, proof-test costs, and missed orders need separate review.
Hot work ignites materials and damages equipment and inventory. Property insurance may help with repairs and replacement, subject to the policy and selected limits. Check the covered fire, machine and stock owners, valuation and any purchased income protection. Faulty products and promised output are separate questions rather than payments assured by the fire.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Powerful equipment operated on crowded jobsites can cause catastrophic injuries from rollovers and crush hazards. Product liability may help respond, subject to policy terms and underwriting.
Evaluate the machines, end uses, plausible claim accumulation, and customer requests against underlying and excess terms. There is no universal limit or essential minimum for every construction machinery maker. Excess does not automatically add recall, own-machine, or professional design protection or insure every contract.
Documented controls, guarding, and stability testing are central to underwriting heavy equipment and can influence terms and availability, depending on operations and loss history.
Equipment breakdown coverage may help with repair and lost production when major CNC machines, presses, or test rigs fail, depending on the specific policy and exclusions.
Bring dealer or fleet requests for limits, indemnity, the products included, and additional-insured status. Compare them with issued terms and endorsements. A demand or certificate neither assures an available matching program nor insures every repair or recall obligation assumed.
Workers' compensation commonly responds to heavy-steel, hot-work, and machinery injuries, subject to policy terms and applicable state law.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.