

Customers
Wet floors and hot machines can cause injuries.
Try a different word, or check the spelling.
Your coin box, changer and washing machine can be affected in the same theft attempt without sharing one coverage grant. Money and property terms should distinguish those interests, alongside unattended customer use and any solvent-based cleaning you actually offer.
Describe actual staffing and hours, machine and cash values, lease duties and any attended garment or solvent services.
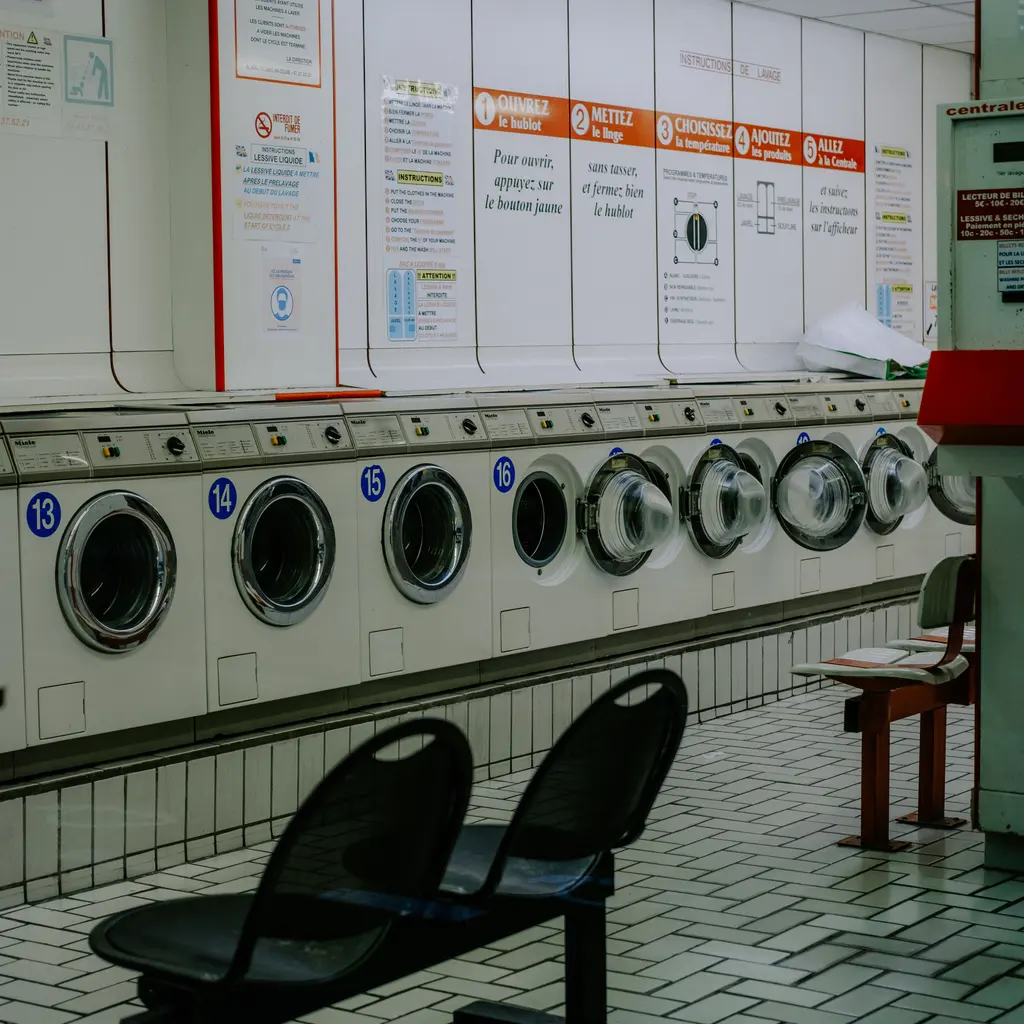
You provide self-service machines for customers, often operating without an attendant on site. A leak or a boiler failure can result in extensive damage to your building and neighboring units.
The Southern Agency can review your unattended operations and machine maintenance to help you choose insurance for your equipment. We can also clarify coverage for collected payments and potential environmental issues.
Wet floors and hot machines can cause injuries.
Leaks or overflow can affect the shop and neighbors.
Boilers, motors, and machines are income dependencies.
Coin boxes and changers can be targeted.
Solvents and any attended garment services add different interests.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
Ready to compare options?
Get a quote for Coin-Operated Laundries and Drycleaner Or call 1-800-777-1TSAThese hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A failed hose could flood your laundry and the neighboring unit. Property terms determine eligible damage to your machines and improvements; liability for a neighbor's loss depends on actual responsibility and exclusions. Lease duties and the label 'water damage' do not establish that both losses are insured.
Liability depends on the condition and circumstances.
Thieves might force open coin boxes and damage the machines while taking cash. Compare accepted money limits, collection locations and theft conditions with property terms for the equipment. Replacing a damaged lock or washer does not establish reimbursement of every claimed cash balance.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Unattended customers still create injury claims; disclose actual operating hours and controls.
Leak and overflow treatment depends on cause, maintenance, and water exclusions.
Money needs appropriate crime limits, locations, and accepted theft conditions.
A failure can interrupt receipts, but insured income requires a qualifying trigger.
Actual solvent use adds property and pollution questions; availability is not assumed.
Responsibility and cover depend on machine use, facts, and any custody terms; damaged clothing is not automatically paid.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.