

Skip to content

Personal Services Insurance

An appointment or service record can hold sensitive information as well as the details of the work. Your protection should fit the service and any custody you accept, alongside the premises, equipment, and people involved.

The Southern Agency can help you review coverage for your personal-service business operations.
Explore insurance for 15 business types.

Find your business

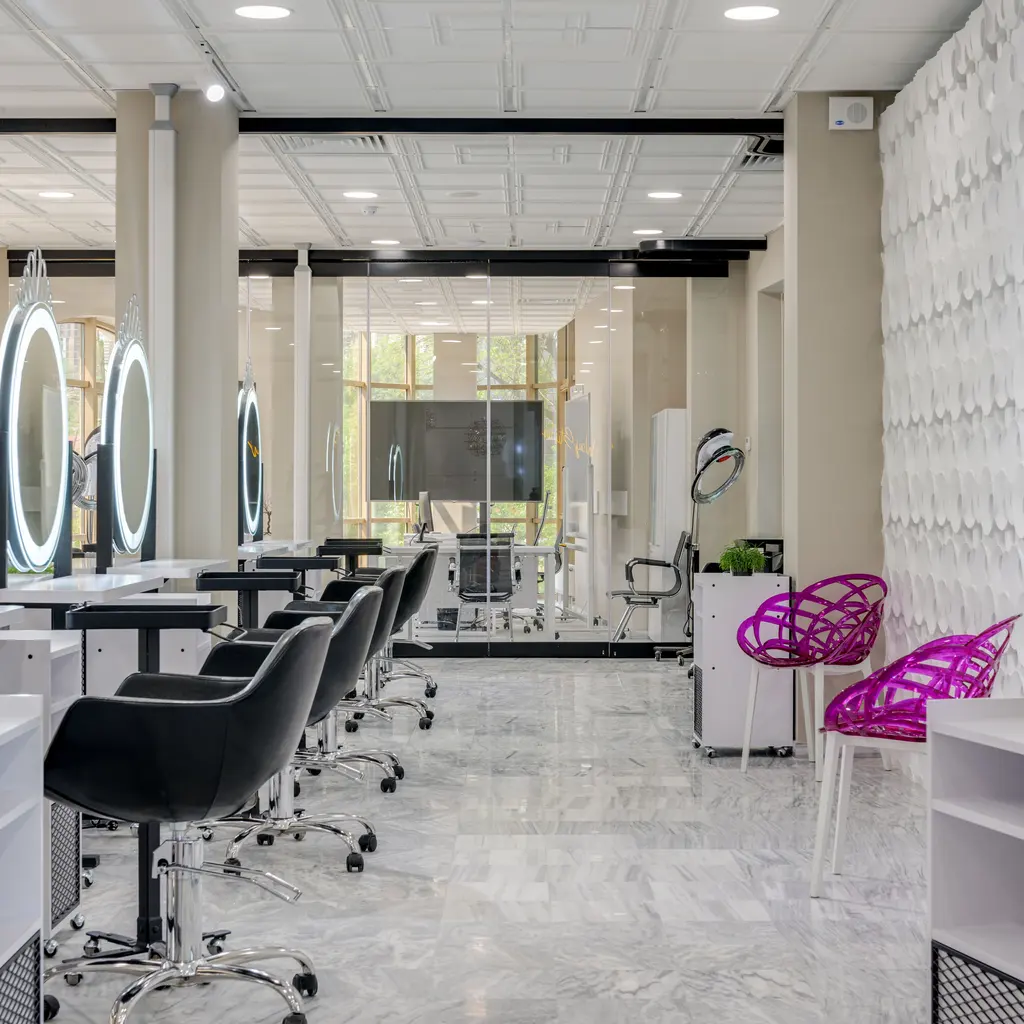
Empty salon styling stations with hydraulic chairs, counters and illuminated mirrors.

Operations within this group

You may care for people, animals or customers' belongings through services such as grooming, laundry or funeral work. A treatment injury or damage to an item in your care can lead to a claim that depends on the service and responsibility involved.

The Southern Agency can review your services and custody arrangements to help you choose insurance. We can discuss accepted treatment or professional liability and customer-property protection alongside your own premises and equipment needs.

Find your business

Choose your business type to discuss insurance with The Southern Agency. If it isn’t listed, call an agent to ask whether we can place it.

  1. Barber ShopBarber shop insurance considers razor services, customer visits, chairs, and independent chair renters.
  2. Beauty SalonBeauty salon insurance considers chemical treatments, heat styling, retail products, and chair-rental arrangements.
  3. Cemeteries and CrematoryCemetery and crematory insurance considers interment duties, visitor grounds, memorials, and high-temperature equipment.
  4. Coin-Operated Laundries and DrycleanerSelf-service laundry insurance considers unattended customers, machine failures, water damage, and collected payments.
  5. Diet and Weight Reducing CenterWeight-loss center insurance considers coaching advice, sold consumables, client records, and advertised outcomes.
  6. Drycleaning and Laundry ServiceDrycleaner and laundry insurance considers customer garments, cleaning processes, solvents, and delivery routes.
  7. Funeral Homes and Funeral ServiceFuneral home insurance considers preparation duties, family services, transport, and sensitive entrusted interests.
  8. Industrial LaundererIndustrial laundry insurance considers continuous plant machinery, contaminated textiles, customer goods, and route fleets.
  9. Linen Supply ProviderLinen supply insurance considers owned rental stock circulating through client sites, laundering, and delivery.
  10. Nail SalonNail salon insurance considers infection allegations, enhancement services, chemicals, and station renters.
  11. Parking Lots and GarageParking facility insurance considers vehicle custody, pedestrians, structures, and access equipment.
  12. Personal Care ServicePersonal care insurance considers hands-on treatments, applied products, client visits, and mobile appointments.
  13. Personal ServicePersonal service insurance considers errands, household assistance, client property, and entrusted access.
  14. Pet Care ServicePet care insurance considers animals in custody, public bites, grooming work, and in-home services.
  15. Photo Printing LabPhoto lab insurance considers image custody, processing equipment, customer privacy, and finished products.

Risks across this group

Client injuries

Treatments and services can cause burns, reactions, or other bodily injuries.

Professional liability

A service that goes wrong can lead to claims of professional error or negligence.

Premises injuries

Clients in the space create slip-and-fall and general injury exposure.

Product reactions

Chemicals and products used in treatments can cause allergic or adverse reactions.

Property and equipment

Fire, water, and theft threaten the premises, fixtures, and equipment.

Appointment and client data

Booking systems and client records create some data exposure.

Situations to think through

These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.

  1. Hypothetical: Treatment reaction

    A client has an adverse reaction to a product used during a service. Professional and general liability may help respond, subject to policy terms.

  2. Hypothetical: Slip in the salon

    A client slips on a wet floor and is injured. General liability may help respond to the bodily-injury claim, subject to terms.

  3. Hypothetical: Equipment fire

    A fire damages salon equipment and fixtures. Property coverage may help with repair and replacement, subject to terms.

Before you talk to an agent

What to have ready

Tick items as you gather them. Nothing here is saved or sent.

Questions to raise

  • For grooming or personal care, list each treatment and product used or sold. Compare premises and professional liability with the exact services, practitioner credentials, and any restrictions.
  • For laundry, parking, pet care, or photo services, identify the customer property in custody, maximum values, and what happens if it is damaged or lost. A company's own contents coverage does not establish protection for entrusted goods.
  • If space is shared, identify employees, booth renters, and independent businesses and their separate policies. Include mobile and off-site services and compare them with lease or service-agreement terms.
  • List machines and portable equipment separately. Internal breakdown, external damage, routine maintenance, and customer compensation for a failed service are different questions.

Contract terms to check

  • Bring premises and booth-rental leases, customer custody terms, mobile-service contracts, and equipment finance or rental agreements that apply. Review insurance requests and responsibility for other people's property. Check practitioner licensing and worker-injury obligations for the actual service and jurisdiction.

What the agent conversation looks like

Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.

  1. ListenReview your operations, current coverage, and past claims.
  2. AssessIdentify potential hazards and discuss ways to reduce risk.
  3. BuildDiscuss policy and carrier options, premium costs, and audits.
  4. SupportReview changes and help you plan ahead as your needs develop.

Questions owners ask

Do salons need professional liability in addition to general liability?

Many do. General liability addresses premises injuries, while professional liability addresses claims that a treatment or service caused harm.

Are booth renters covered by the salon's policy?

Independent booth renters commonly need their own coverage, as a salon's policy may not extend to their separate services.

Is a BOP a good fit for personal-service businesses?

A BOP fits many small salons and studios by bundling liability and property, though professional liability is commonly added separately.

Do product reactions count as professional claims?

Reactions to products used in a service can lead to both bodily-injury and professional allegations, depending on the circumstances and policy.

Do personal trainers need coverage?

Trainers and instructors face client-injury and professional exposure, so they commonly carry general and professional liability.

Tell us what your personal services business does

Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.

How can we help you get started?

Choose the quote that fits, and we’ll take it from there.

Have a question? Contact us