

Guests and amenities
Pools, hot tubs, and stairs expose unfamiliar visitors to injury.
Try a different word, or check the spelling.
Damage discovered at turnover can affect both the furnishings and your next booking. Review guest-caused losses and rental-income terms before assuming a platform program will reimburse you.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
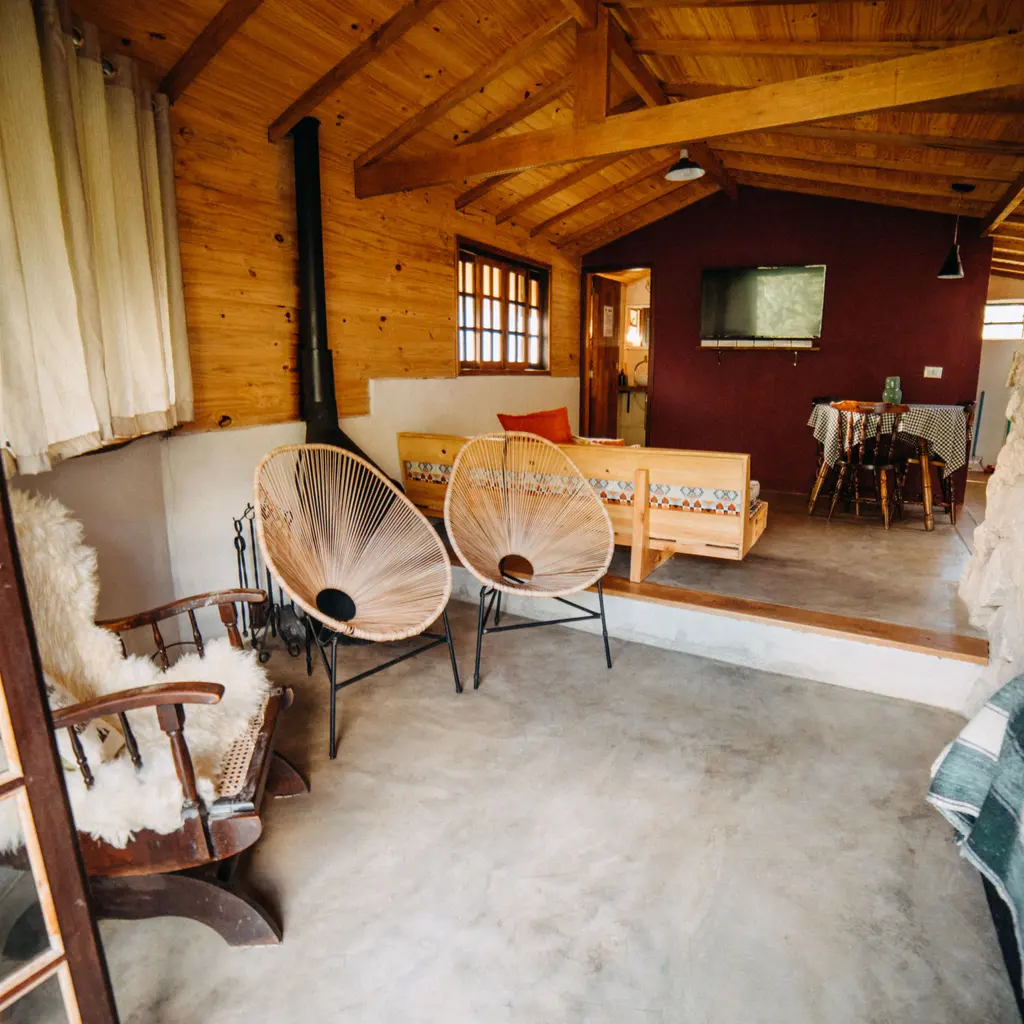
You prepare furnished homes for short-term stays, managing turnover and guest experience. A guest injury or property damage can occur while your home is being rented.
The Southern Agency can review your rental business model and amenities to help you select appropriate insurance. We can help you protect your building and furnishings while addressing specific liability concerns for guest-occupied properties.
Pools, hot tubs, and stairs expose unfamiliar visitors to injury.
Theft or damage can affect furniture and finishes between stays.
Damaged units can stop earning while expenses continue.
Rental rules and insurance acceptance are separate questions.
Online reservations involve guest data and account access.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A guest is injured using the hot tub and alleges poor maintenance. Liability coverage may address a covered claim if the rental and amenity are accepted. Review the operator's and maintenance provider's duties and any pool or hot-tub exclusions.
After a party, you find broken furniture and missing household items. Property recovery depends on the cause, evidence and guest-damage, theft and intentional-act provisions. Replacing everything on the repair list is not an automatic benefit.
A kitchen fire makes the unit unfit for guests and forces cancellations. Property coverage may address covered repairs, while rental-income protection has its own trigger, waiting period and restoration terms. Future bookings and ongoing expenses need documented review.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Confirm the insurer accepts transient rental use; do not assume an owner-occupied form fits.
Compare the platform's current terms with the property, amenities, and own insurance.
Pools and hot tubs need direct acceptance and relevant exclusions reviewed.
Guest-caused damage depends on cause and wording, not simply a repair bill.
Lost booking income requires a covered trigger and applicable restoration period.
Data response, account recovery, and money reimbursement are different protections.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.