

Custody
Shoes or bags can be mixed up, lost, or damaged.
Try a different word, or check the spelling.
A pair sent home with the wrong customer creates a different question from proven theft or rejected stitching. Your bailee and shop protection need the actual customer-goods, processing, and unexplained-loss terms, without treating every missing item or refund demand as a crime claim.
The Southern Agency can help review how you record and value customer items, with separate attention to your machines and staff duties.
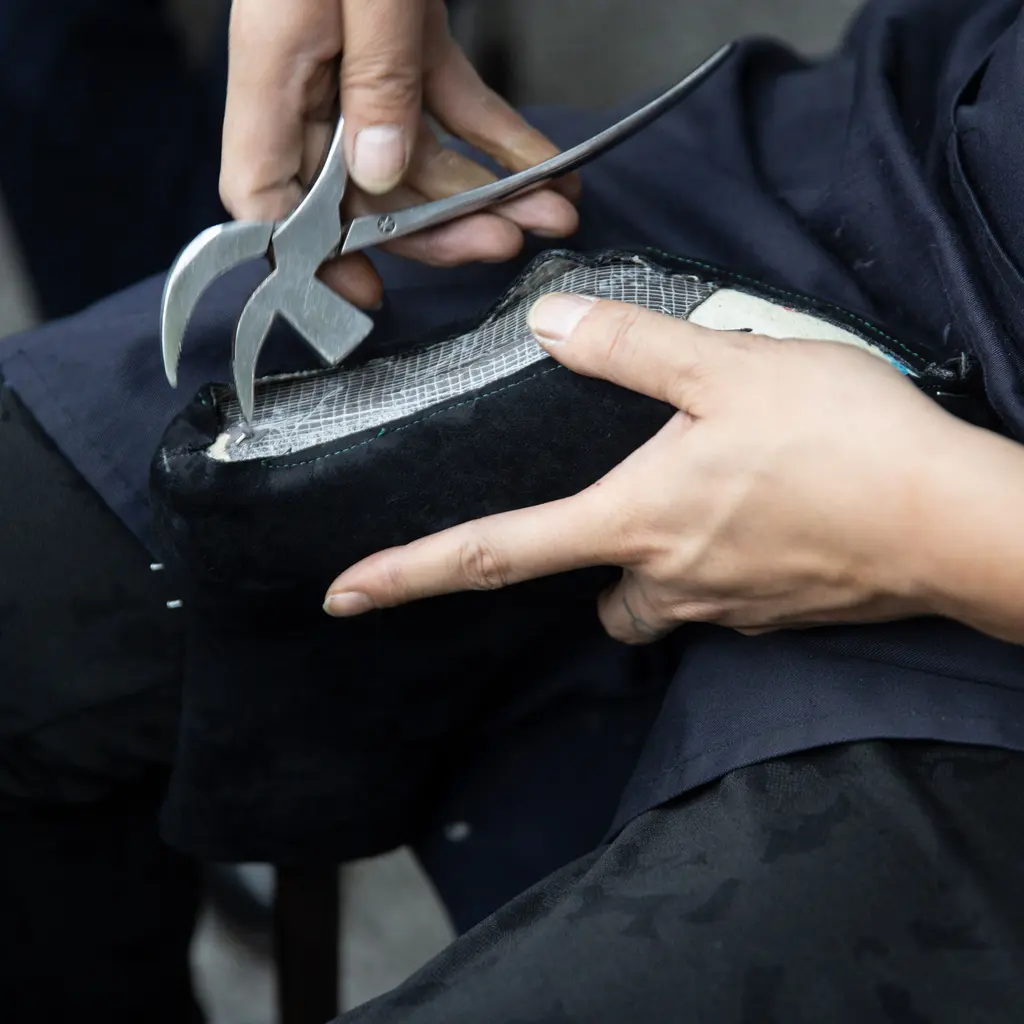
You resole shoes, replace zippers, and repair leather goods left at your counter. A missing designer bag creates a custody question, while an employee injury involving a trimming machine concerns your staff benefits.
The Southern Agency can review your shop processes, condition documentation, and machinery to help you select appropriate insurance. We can discuss how to protect client property while addressing liabilities for retail visits and bench work.
Shoes or bags can be mixed up, lost, or damaged.
Sanders, trimmers, and stitchers create hand injuries.
Some adhesives and dressings add fire concerns.
Rejected stitching or color work can lead to refund demands.
Visitors, money, and payment records create different interests.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A customer returns with a repair ticket, but a designer handbag cannot be found and no theft is established. Review custody, unexplained-disappearance and valuation provisions, plus the item's recorded condition and receipt limit. Neither a crime limit nor a claimed retail price proves payment.
A bench employee injures a hand on a trimming wheel. Review workers compensation for the covered injury, actual employer and applicable benefit rules. The machine repair bill or a customer's damaged shoe does not fall into that same injury-benefit payment.
Adhesive vapors ignite at the shop, damaging workbenches and customer shoes awaiting pickup. Check the accepted materials, cause of loss and separate limits/valuation for shop property and entrusted goods. A repair ticket or storefront limit does not establish payment for every customer's item.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Check the actual customer-property grant for shoes and bags, including custody, processing damage, valuation and any legal-liability trigger. A shop/property or crime limit alone is not proof that every missing or damaged item is covered.
Machines affect worker duties and property values; guarding does not guarantee any particular premium.
Actual materials and storage inform fire underwriting.
A poor result or redo bill is not automatically liability damage.
Cash theft and client-goods loss need appropriate property definitions and causes.
Values, machinery, materials, payroll, and claims affect terms.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.