

Custody
Antiques may have disputed or hard-to-replace values.
Try a different word, or check the spelling.
The value you agree with a client for an antique may not be the value your insurer accepts. Establish the custody valuation and processing terms before stripping or sanding an irreplaceable piece.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
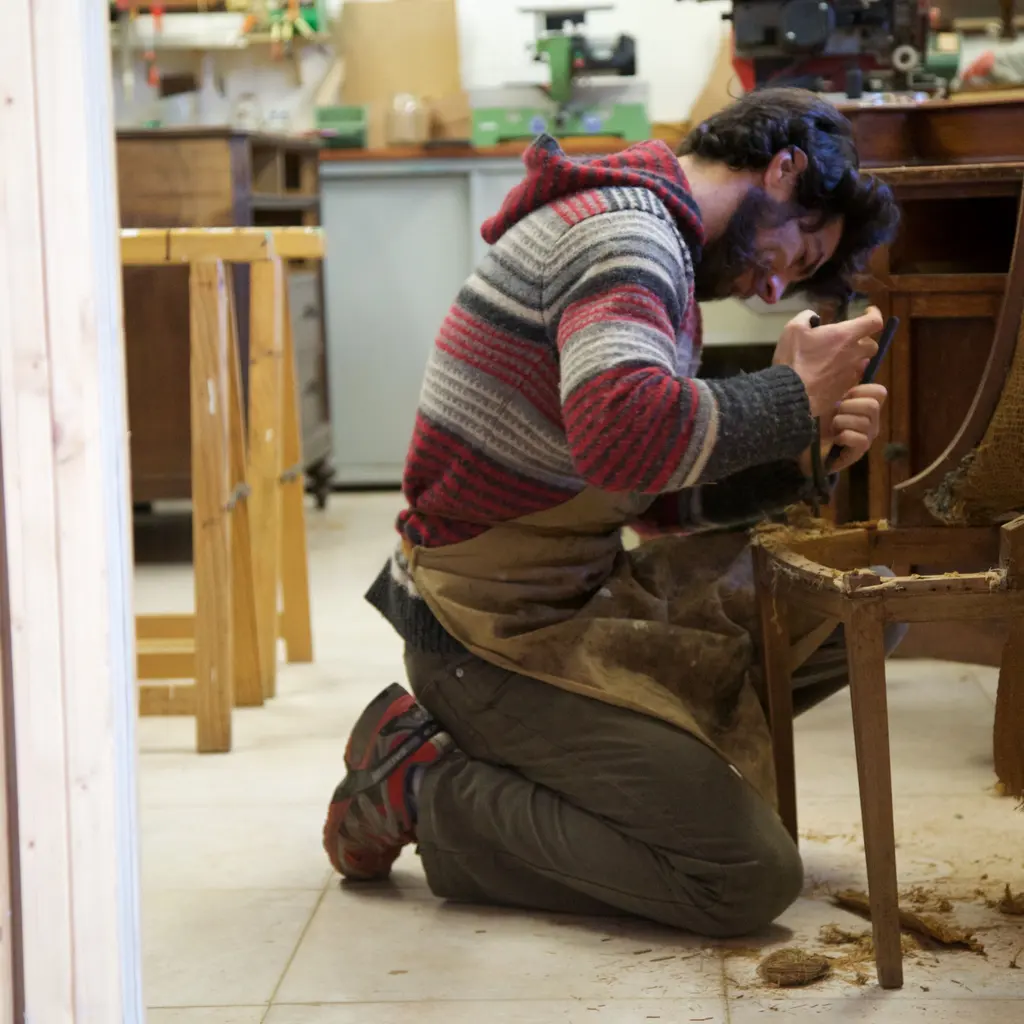
You repair joints, veneer and finishes on pieces that clients may be unable to replace. Fire can damage multiple heirlooms at once, while sanding through veneer during restoration creates a claim about the work itself.
The Southern Agency can review your finishing processes, shop storage, and pickup services to help you select appropriate insurance. We can discuss how to protect high-value customer items and manage liability for your craftsmanship.
Antiques may have disputed or hard-to-replace values.
Stripping or sanding can irreversibly alter a piece.
Finishes, solvents, and some oil-soaked rags create ignition concerns.
Chemical residues can create release or disposal claims.
Tools and furniture transport can injure staff or damage goods.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Oily rags ignite and damage shop equipment and several clients' furniture. Own-property terms may address covered workshop losses, while entrusted pieces need suitable custody protection. Confirm the fire cause, peak values and accepted valuation for each interest rather than assuming a building limit replaces the heirlooms.
Sanding cuts through the veneer on a client's cabinet. Any payment depends on express damage-during-processing terms, accepted valuation and exclusions. A larger custody limit does not remove a processing exclusion, and dissatisfaction with the finish alone is not proof of insured damage.
Spent stripper leaks from a waste container beside the workshop and contaminates soil. Accepted environmental terms may address covered investigation or cleanup. Substance, discovery, location and disposal duties matter; repairing the container or paying every disposal bill is not automatically the same covered expense.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Document pieces and values, then confirm an accepted valuation and custody basis.
Chemical and rag practices affect fire review; materials differ.
Actual waste and releases need environmental review without assuming all materials share one legal classification.
Processing damage may be excluded; dissatisfaction alone is not automatically covered.
Auto protects accepted vehicle interests while antiques need transit protection.
Values, processes, building, staffing, transport, and losses affect terms.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.