

Devices
Customer machines can be damaged in custody or transit.
Try a different word, or check the spelling.
A recovery job can leave you responsible for information as well as the machine brought in for repair. Your service, data, and customer-property terms should fit that work, with processing damage distinguished from a warranty of success or the tools you carry to a client.
Bring your actual repair and recovery services, entrusted-device values and locations, file access and customer promises.
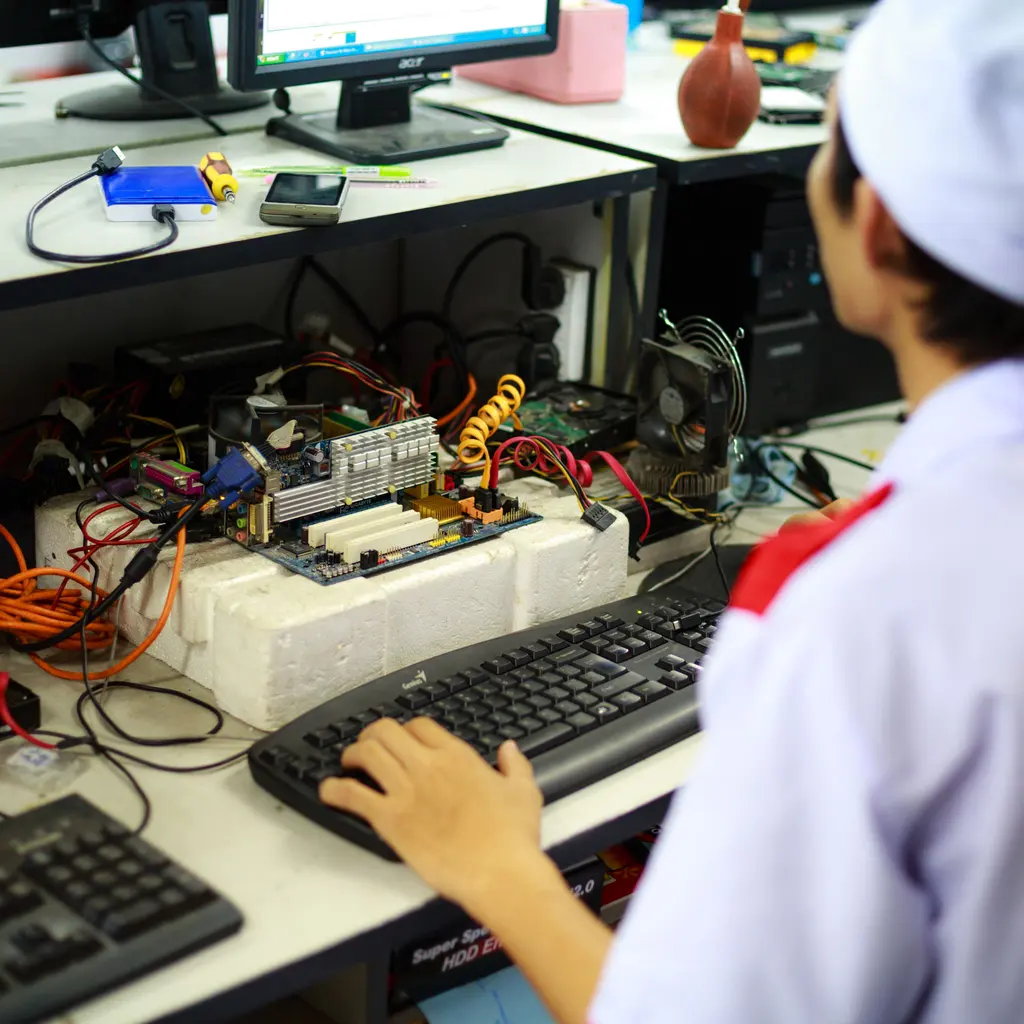
You may repair computers, remove malware, set up systems or train users, in your shop or at a client's site. Dropping a laptop can damage hardware, while overwriting files can lead to a different service-error or data-loss claim.
The Southern Agency can review your mix of services to help you choose insurance. We can compare customer-property protection with professional and cyber terms, so physical repairs and work on client data receive separate attention.
Customer machines can be damaged in custody or transit.
Recovery or configuration can erase data.
Incorrect settings can cause client disruption.
Technicians may access personal or business information.
Installations, travel, and tools create physical exposure.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
You could drop a customer's laptop while moving it to the repair bench. Explicit customer-equipment terms may help with covered physical damage under accepted custody and processing conditions. Ownership, valuation and deductible matter; replacing hardware is not automatically the same benefit as restoring its files.
A recovery attempt could overwrite files and lead to a client claim about your work. Review accepted recovery services, negligence allegations and actual E&O or data-restoration provisions. The client's stated value for irreplaceable files, a refund and your promise of successful recovery are not automatically covered damages.
A customer could trip over a cable you placed during a home installation. GL may help defend a covered injury claim if the actual site work is accepted. Responsibility, cause and exclusions matter; any medical-payment benefit has its own conditions rather than an automatic payment for every trip.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Customer gear needs explicit custody and processing scope.
Repair errors can produce financial-loss claims beyond ordinary GL.
Data loss requires accepted services and definitions; cyber and E&O are not interchangeable.
Tools need off-site and transit values and conditions.
Device access can create privacy responsibility even without hosting client systems.
Review personal-auto business use and business-owned or non-owned protection for the actual driving.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.