

Dense-route driving
Stopping, reversing, and entering driveways can lead to pedestrian or vehicle claims.
Try a different word, or check the spelling.
Your delivery is still your responsibility at the doorstep. Review where parcel custody ends and how your insurance treats an injury or damage during the handoff.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
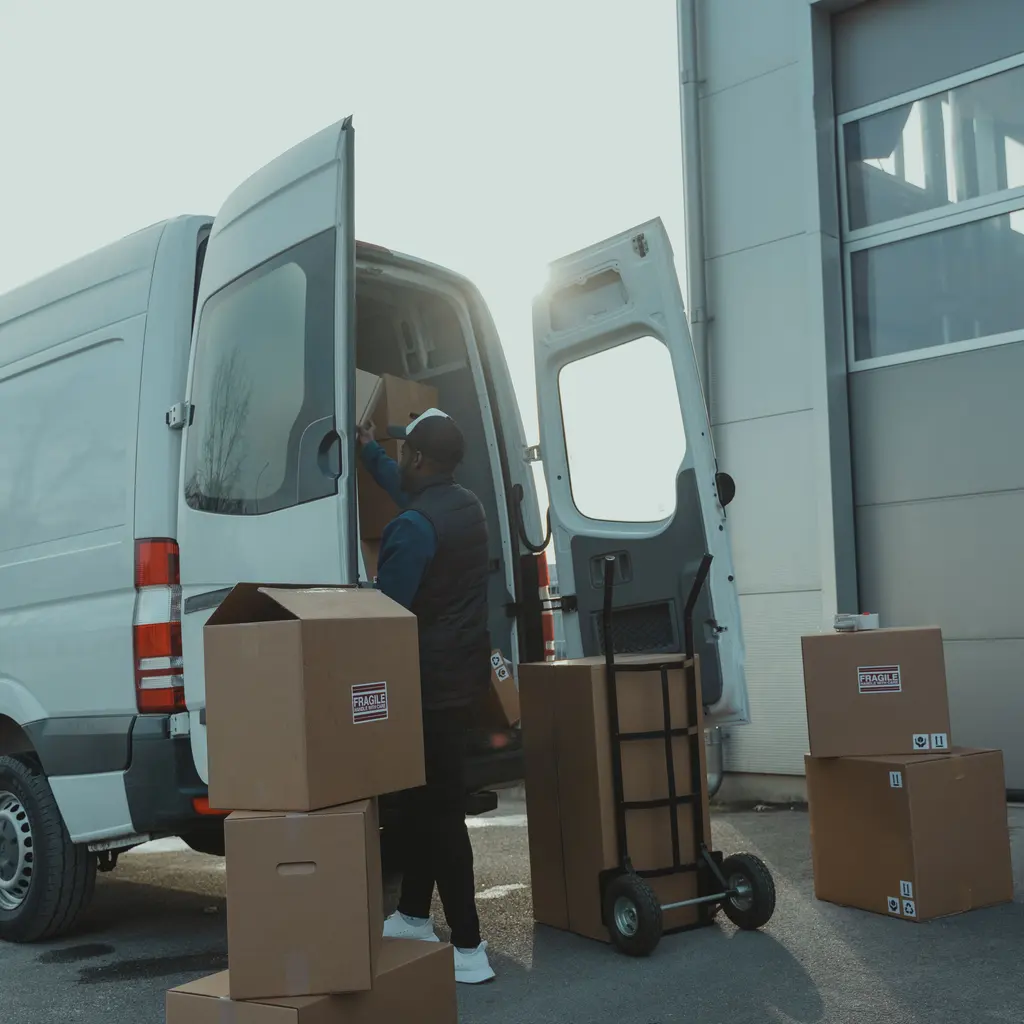
You collect parcels and hand them off to homes and businesses, a process where damage can occur in the van or during the final delivery. A driver slipping on a customer's stairs can be as disruptive to your work as a package damaged in transit.
The Southern Agency can review your collection and delivery flow to help you select appropriate insurance. We can discuss how to maintain protection for goods from pickup through handoff, while keeping vehicle-related risks distinct from delivery-site liability.
Stopping, reversing, and entering driveways can lead to pedestrian or vehicle claims.
Packages can be stolen in transit or after being left outside. Coverage may end before the customer retrieves them.
A poorly placed parcel can obstruct a walkway; dogs, stairs, and uneven ground also threaten driver safety.
A depot fire or stolen scanner can disrupt routing. Owned equipment and customer parcels require different values.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A driver backs a delivery van into a customer's parked car. Business auto liability may address the resulting damage claim. Repairing your van requires its own physical-damage coverage.
A thief takes parcels while the driver is making another delivery. Cargo coverage depends on the policy's theft and unattended-vehicle conditions, package values and custody period. A customer's refund demand does not determine the insured amount.
An employee carrying a parcel slips on icy porch steps and needs medical treatment. Workers' compensation may provide benefits for a qualifying work injury. An independent driver's benefits require a separate review of employment status and applicable arrangements.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Auto, cargo, employee injury, and premises liability address different parts of delivery. Review the whole collection-to-handoff service.
Coverage depends on the cargo form's property, valuation, and custody terms. Porch theft after completed delivery may be outside cover.
Review delivery-approved personal insurance and company non-owned liability separately. Company HNOA does not automatically repair the driver's car.
Employee on-route injuries may fall within applicable compensation protection, depending on employment facts and jurisdiction.
GL or auto may be relevant depending on the activity. Custody and loading exclusions require review.
Consider accident severity and customer requirements. Excess needs compatible underlying delivery policies and does not insure every service penalty.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.